 Cloud Printing Market
: Size, Share & Forecast 2025-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 279

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Cloud Printing Market
Srinwanti Kar
Senior Research Analyst
| Year | Market Size |
|---|---|
| 2024 | 1.700 B |
| 2025 | 1.900 B |
| 2026 | 2.100 B |
| 2027 | 2.400 B |
| 2028 | 2.600 B |
| 2029 | 2.900 B |
| 2030 | 3.000 B |

The Cloud Printing Market encompasses software, services, and managed solutions that enable users to send print jobs over the internet to remote printers without direct device connections or local drivers. It supports centralized management, secure release, and analytics across distributed workforces.
This report covers cloud print software, managed cloud print services, and associated connectivity and security solutions across public, private, and hybrid cloud deployments. It includes segmentation by connectivity, industry vertical, and region. This analysis does not cover traditional on-premises print servers, standalone printer hardware sales, or consumer-grade home printing solutions.
The market size varies significantly across published estimates due to differences in scope definition, with some analyses including managed services and others focusing narrowly on software. The table below compares key estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 1.7 Billion | 2024 | 2030 | 11.6% | Cloud printing software and services | One published estimate |
| USD 2.65 Billion | 2024 | 2034 | 13.6% | Cloud printing services incl. managed print | Competing analysis |
| USD 6.5 Billion | 2024 | 2034 | 17.8% | Cloud-based printing incl. solutions and services | Alternative published estimate |
Our analysis suggests the USD 1.7 billion figure for 2024 is the most defensible baseline, as it aligns with enterprise adoption patterns and excludes broader managed print services that inflate the total. The higher estimates likely capture adjacent managed print operations and hardware-adjacent services, which have different growth dynamics and competitive structures.
The Cloud Printing Market is segmented by cloud deployment type, connectivity, and industry vertical, each reflecting distinct buyer priorities and adoption drivers.
| Parent Segment | Children |
|---|---|
| By Cloud Type | Public, Private, Hybrid |
| By Connectivity | Wi-Fi, TCP-IP, Bluetooth |
| By Industry | BFSI, Government, Education, IT & Telecommunications, Manufacturing, Healthcare, Retail & Logistics |
Public cloud leads with 46.6% share, favored for scalability and lower upfront costs. Private cloud is the fastest-growing segment as regulated industries prioritize data control and compliance. Wi-Fi connectivity dominates due to its range and multi-device support, while Bluetooth is gaining traction in mobile and retail settings for short-range, low-energy printing.
North America leads the global Cloud Printing Market with 36.4% revenue share in 2024, driven by advanced IT infrastructure and widespread hybrid-work adoption. Asia Pacific is the fastest-growing region, propelled by digital transformation and expanding SME adoption.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.26% |
| Asia Pacific | 0.24% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
Europe follows North America with strong regulatory-driven adoption in BFSI and healthcare. Asia Pacific is expected to register the highest CAGR, supported by rapid cloud migration and government digitization initiatives.
The primary growth drivers are hybrid work adoption, cloud migration, and sustainability initiatives, while security concerns and internet dependency are the main restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Hybrid and remote work | Driver | High | Demand for flexible, secure print access from any location |
| Cloud migration and serverless printing | Driver | High | Eliminates on-premises servers, lowers TCO |
| Sustainability and ESG goals | Driver | Medium | Print quotas and pull printing reduce paper waste |
| Security and compliance requirements | Driver | High | Regulated industries require secure release and audit trails |
| Data security concerns | Restraint | Medium | Sensitive data may favor on-premises solutions |
| Internet dependency | Restraint | Medium | Outages disrupt printing operations |
| Declining office print volumes | Restraint | High | Structural decline in page volumes reduces growth potential |
Our analysis suggests the driver-restraint balance favors growth, but vendors must address security and reliability concerns to unlock the full potential of regulated industries. The decline in office print volumes is a structural headwind that will push vendors toward value-added services and workflow automation.
The competitive landscape is moderately concentrated, with Microsoft and Google leveraging their cloud ecosystems, while specialized vendors like Vasion and Pharos compete on security and workflow features.
| Company | Focus Area | Differentiation |
|---|---|---|
| Microsoft | Universal Print | Deep integration with Microsoft 365, serverless architecture |
| Cloud Print (deprecated) / Workspace | Ecosystem integration, but reduced direct print focus | |
| HP | Managed Print Services | End-to-end managed services, hardware integration |
| Star Micronics | StarIO.Online | Retail-focused cloud printing, hosted server management |
| Vasion | Cloud print platform | Serverless printing, output automation, document workflows |
| Pharos | Cloud print management | Security controls, distributed environment management |
| Konica Minolta | KPAX multi-brand fleet | Dealer network, multi-brand fleet management |
Differentiation hinges on security certifications, integration with enterprise SaaS platforms, and the ability to support hybrid work environments. Vendors with strong security credentials and flexible deployment options are best positioned to capture regulated industry demand.
Buyers must prioritize security and compliance when selecting cloud printing solutions. Regulated industries require time-stamped logs, controlled release, and encryption both in transit and at rest. Integration with existing identity management systems is critical to avoid operational disruption.
Procurement risks include vendor lock-in, data residency constraints, and reliance on internet connectivity. Organizations should evaluate providers' SLAs for uptime and disaster recovery. Switching costs can be significant due to driver deployment and user training, so pilot programs and phased rollouts are recommended.
Operators should consider total cost of ownership beyond subscription fees, including potential reductions in IT support and print server maintenance. Sustainability goals can be supported through print analytics and quotas, aligning with ESG reporting requirements.
The balance of evidence favors a market poised for sustained double-digit growth, with public cloud and North America leading near-term adoption. However, the strongest counter-argument is that declining office print volumes could cap long-term growth, forcing vendors to pivot toward workflow automation and document management to sustain revenue.
Our analysis suggests vendors should prioritize security-first, subscription-based offerings to capture regulated industry demand. Investment in AI-driven analytics and predictive maintenance can differentiate solutions and reduce operational costs for buyers. Partnerships with hardware manufacturers and system integrators will be essential to reach SMEs and distributed workforces.
Actionable Strategy:
What would change our conclusion: A faster-than-expected decline in office print volumes or a major security breach in a leading cloud print platform could dampen adoption and shift buyer preferences toward on-premises solutions.

| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.6% from 2020-2034 |
| Segmentation |
|
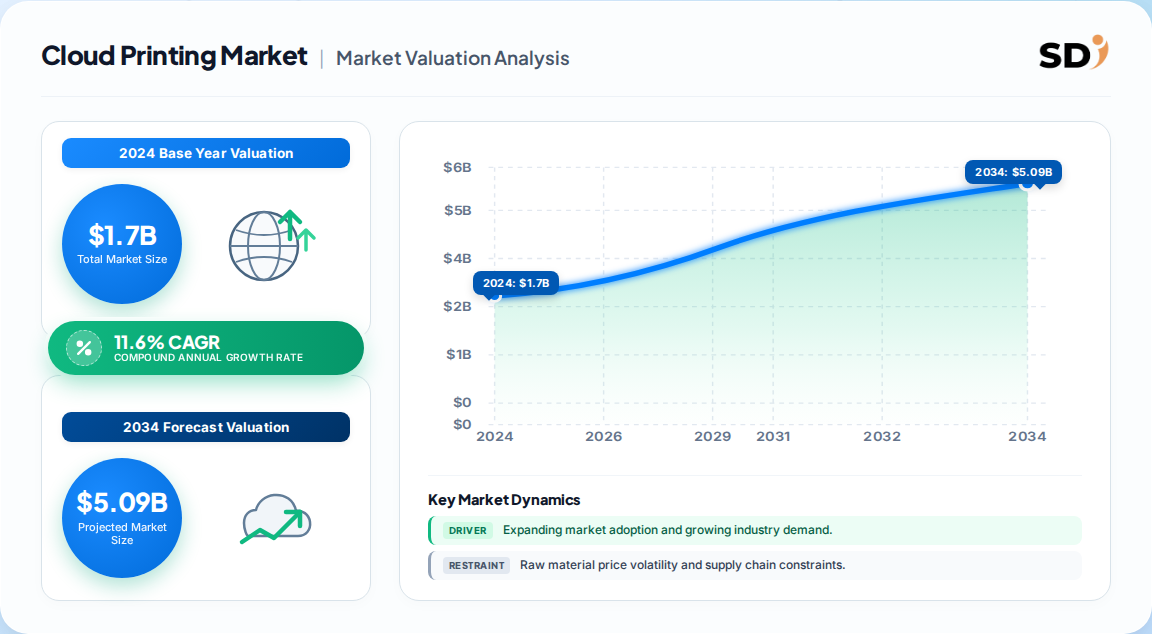
The global Cloud Printing Market was valued at USD 1.7 billion in 2024 and is projected to reach USD 3.0 billion by 2030, growing at an 11.6% CAGR.
North America leads with a 36.4% revenue share in 2024, driven by advanced cloud infrastructure and early hybrid-work adoption.
The market is segmented by cloud type (public, private, hybrid), connectivity (Wi-Fi, TCP-IP, Bluetooth), and industry vertical (BFSI, IT & telecom, healthcare, etc.).
Key vendors include Microsoft, HP, Star Micronics, Vasion, Pharos, and Konica Minolta, competing on security, workflow automation, and integration.
Growth is driven by hybrid work adoption, cloud migration, and sustainability initiatives, while security concerns and internet dependency are key restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split. We conducted in-depth interviews with key stakeholders across the value chain, including cloud print software vendors, managed print service providers, printer manufacturers, system integrators, and enterprise IT buyers. Decision-maker designations interviewed include VP of IT Infrastructure, Heads of Print Management, Procurement Directors, and Compliance Officers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| IT Infrastructure Leads | 35% |
| Procurement Directors | 30% |
| Compliance & Security Officers | 20% |
| Operations Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Cloud Print Software Vendors | 40% |
| Managed Print Service Providers | 30% |
| Printer Manufacturers | 20% |
| System Integrators & Resellers | 10% |
We leveraged official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings), patent databases, and recognized industry associations such as CompTIA and the Mopria Alliance to validate market sizing and trends.
Our simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (vendor revenue, device shipments, and end-use consumption) data triangulation ensures robust market sizing.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up revenue triangulation | High |
| Forecast Horizon | 2025-2030 compound projection | Historical CAGR, regression analysis | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping | High |