 AI Based Climate Modelling Market
 2026: Size, CAGR & Leaders
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 198

Srinwanti Kar

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 AI Based Climate Modelling Market
Srinwanti Kar
Senior Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 410.0 M |
| 2026 | 492.0 M |
| 2027 | 600.0 M |
| 2028 | 733.0 M |
| 2029 | 895.0 M |
| 2030 | 1.090 B |
| 2031 | 1.330 B |

The AI based climate modelling market covers software, platforms and services that apply machine learning, deep learning and computer vision to simulate, downscale and forecast climate and weather outcomes. It spans weather forecasting, climate prediction, disaster risk reduction and environmental monitoring, delivered as cloud, hybrid or on-premise deployments to agencies, insurers, utilities and enterprises.
Scope is global, covering commercial and public-sector spending on AI-enhanced climate and weather modelling software, API tools, managed platforms and associated services across weather forecasting, climate prediction, disaster risk reduction and environmental monitoring. It includes cloud, on-premise and hybrid deployment models and both SME and large-enterprise buyers.
This analysis does not cover conventional physics-only climate simulation licences sold without AI components, general-purpose geospatial analytics platforms, carbon accounting and ESG reporting software, hardware-only Earth observation constellations, or professional services engagements where no modelling software is deployed. Hardware revenue from satellites and high-performance computing is excluded, although it materially shapes demand.
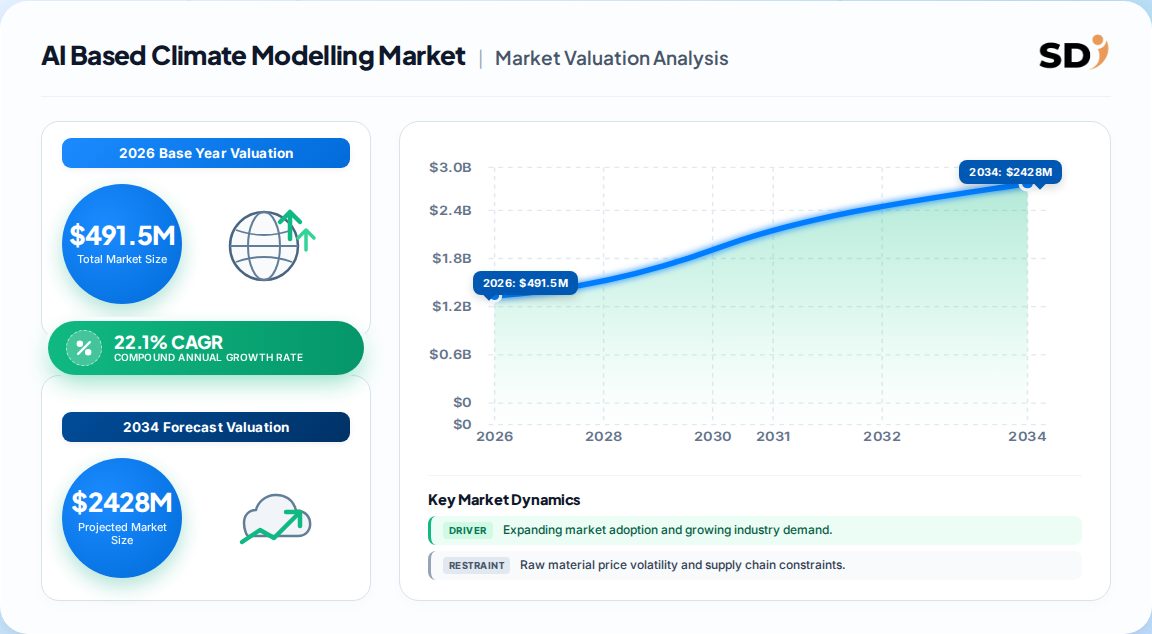
The most defensible base figure is USD 491.5 million for 2026, because it sits within a continuous 2025–2033 series at a single stated CAGR and is corroborated by two independent 2026 estimates within 9% of it.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 491.5M (2026); USD 1,992.1M (2033) | 2025 at USD 409.8M | 2033 | 22.1% | Software + services; ML, DL, CV; weather, disaster, risk, carbon | One published estimate |
| USD 535.5M (2026); USD 3,879.7M (2036) | 2025 at USD 439.3M | 2036 | 21.9% | Adds deployment, org-size and end-use (BFSI) splits | A competing analysis |
| USD 266.4M (2024); ~USD 2B (2034) | 2024 | 2034 | 23.1% | Narrower commercial-tool definition | A competing analysis |
| USD 339.08M (2024); USD 1.48B (2032) | 2024 | 2032 | 20.6% | Includes carbon emission tracking | A competing analysis |
| USD 314.2M (2025); USD 1.2B (2032) | 2025 | 2032 | 21.2% | Software/services only, narrower application set | A competing analysis |
The spread is explained by scope, not by disagreement on growth. Our analysis suggests the 2025 base values cluster into two camps: roughly USD 310–340M for software-and-services-only definitions, and USD 410–440M where workflow automation and financial-sector risk use cases are included. Growth rates, by contrast, are tightly convergent at 20.6–23.1%, which is the more reliable signal for planning. Buyers should treat the CAGR as robust and the base value as definition-dependent.
Segmentation is consistent across sources on components and technology, but diverges on application breadth and end-use depth — the latter is where the fastest-growing revenue actually sits.
| Parent | Children |
|---|---|
| Component | Software (API tools, connectors, managed platform), Services (model calibration, validation, integration, consulting) |
| Technology | Machine Learning, Deep Learning, Computer Vision, Hybrid AI-Physics / Foundation Models |
| Application | Weather Forecasting, Climate Prediction, Disaster Risk Reduction, Climate Risk Assessment, Carbon Emission Tracking, Environmental Monitoring, Workflow Automation |
| Deployment | Cloud, On-Premise, Hybrid |
| Organization Size | SMEs, Large Enterprises, Public Sector |
| End Use | BFSI, Agriculture, Energy & Utilities, Government & Weather Agencies, Insurance, Transportation & Logistics |
North America leads with roughly 39–40% of global revenue in 2025, but Asia Pacific is compounding fastest at national CAGRs above 23%, making it the decisive battleground for 2026–2033 share shifts.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.24% |
| Asia-Pacific | 0.24% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
| Parent | Children |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Rest of Europe |
| Asia Pacific | China, India, Japan, South Korea, Australia |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
Our analysis suggests the regional story is really a procurement story. North America's lead reflects entrenched public weather budgets and hyperscaler proximity; Asia Pacific's growth reflects monsoon-sensitive planning demand in India (about 23.7% CAGR) and national observation buildouts in China (about 23.0% CAGR). Europe sits between the two, with insurance analytics and climate-service depth in the UK and Germany anchoring steady rather than explosive demand. The practical implication: vendors should not assume North American pricing power persists — Asia Pacific buyers index heavily on API access and low infrastructure overhead.
Growth is driven less by climate concern in the abstract than by three concrete forces: cheaper high-resolution inference, an explosion of observation data, and enterprise mandates to put physical risk into operational workflows.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Extreme-weather losses and disclosure pressure | Driver | High | Insurers and BFSI buyers need location-level hazard scenarios for underwriting and credit |
| Observation data proliferation (satellites, IoT) | Driver | High | NASA archive above 123 PB and new sensing constellations feed model training |
| Hybrid AI-physics downscaling | Driver | High | Cuts compute cost up to ~85% at ~10 km resolution, expanding addressable buyers |
| Open model stacks (NVIDIA Earth-2, ECMWF Anemoi) | Driver | Medium-High | Lowers entry barriers and accelerates specialist vendor formation |
| Data quality and interoperability gaps | Restraint | High | Fragmented satellite, met and historical records raise integration cost |
| Compute cost and scarce climate-science talent | Restraint | Medium-High | Limits scaling in developing regions and SME segments |
| Explainability and audit-trail demands | Restraint | High | Public agencies and banks require validation records before adoption |
The balance favors growth, but the binding constraint has moved. Two years ago the bottleneck was model skill; today it is validation and workflow integration. That reframes competitive advantage: the winners will not be those with the best benchmark score, but those who can produce event-level validation evidence and clean records of model versions inside a buyer's risk system.
Competition is unusually collaborative at the research layer and unusually intense at the platform layer, with hyperscalers and chip designers capturing the infrastructure economics while specialists own hazard-specific credibility.
| Vendor | Positioning | Differentiation |
|---|---|---|
| NVIDIA | Infrastructure + open model stack | Earth-2 open weather AI stack; cBottle generative climate model; GPU compute moat |
| Hybrid AI-physics modelling | 10 km downscaling at up to 85% lower compute; research credibility | |
| Microsoft | Foundation models + cloud | Aurora trained on 1M+ hours of atmospheric data; Azure distribution |
| AWS | Cloud + marketplace | Consumption-based access; broad enterprise footprint |
| IBM | Enterprise integration | Weather-linked analytics embedded in enterprise workflows |
| ClimateAi | Applied climate risk | FICE linking climate to economic outcomes; agri and supply-chain focus |
| Jupiter Intelligence | Physical risk analytics | Portfolio-level asset exposure screening for financial clients |
| Tomorrow.io | Observation + forecasting | DeepSky satellite constellation; AI-native operational forecasting |
| Spire Global, DTN, The Weather Company | Data and forecasting | Proprietary observation networks and operational delivery |
Differentiation is bifurcating. Hyperscalers compete on cost of inference and distribution; specialists compete on hazard-specific validation and domain workflow. Our analysis suggests the durable moat is documented forecast skill tied to a specific decision — a catastrophe bond trigger, a grid dispatch rule, a planting window — because that is what buyers can defend internally and to regulators.
Selection criteria have shifted decisively toward validation, auditability and integration cost. Buyers should demand event-level back-testing against operational baselines rather than aggregate accuracy claims, because a model that performs well on average but poorly during rare events is a liability in exactly the scenarios the purchase is meant to address.
Procurement risk concentrates in three areas. First, data provenance — models trained on regionally sparse data degrade silently in developing markets, so buyers should require regional skill disclosure. Second, version control — climate outputs increasingly feed credit and underwriting decisions, which means model updates must be logged and reproducible for audit. Third, switching costs — API-first deployments are cheap to start but expensive to leave once outputs are embedded in alert routing and planning cycles, so contract terms should cover output portability.
Regulatory exposure is rising. Physical-risk disclosure regimes and public-sector procurement rules increasingly require explainability, which penalizes opaque foundation models used without calibration layers. Operators should also watch compute economics: cloud deployment captures about 40% of demand precisely because training loads are bursty, but repeated large-scale inference can quietly erode the business case unless architectures are right-sized.
The balance of evidence favors strong, durable growth at roughly 22% CAGR through the early 2030s, with the market crossing USD 1.9–2.0 billion by 2033 on the most recent series. The convergence of five independent estimates within 2.5 percentage points on CAGR — despite base values differing by up to 65% — is a rare and reassuring signal. We treat demand growth as the high-confidence conclusion and absolute market size as the low-confidence one.
The strongest counter-argument is that open model stacks from NVIDIA, ECMWF and Google could commoditize forecasting fast, compressing software pricing and pushing value into services and data. That risk is real. Our assessment, however, is that commoditization at the model layer expands the market by lowering entry costs for SMEs (about 48% of buyers), while shifting margin toward validation, integration and workflow automation — where Workflow Automation already holds about a third of application revenue. The moat migrates; it does not disappear.
Actionable strategy:
What would change our conclusion: a sustained multi-year plateau in public weather-agency budgets, or evidence that open models have collapsed commercial software pricing, would push us toward the lower end of the estimate range and a mid-teens CAGR.

| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 22.1% from 2020-2034 |
| Segmentation |
|
The market is estimated at USD 491.5 million in 2026, up from USD 409.8 million in 2025. Competing published estimates range from roughly USD 314 million to USD 439 million for 2025, depending on whether workflow automation and financial-sector risk use cases are counted.
Published forecasts converge tightly on 20.6% to 23.1% CAGR. The most recent series projects 22.1% CAGR from 2026 to 2033, reaching about USD 1,992.1 million by 2033 — the highest published horizon and the anchor used in this analysis.
North America accounted for roughly 39–40% of global revenue in 2025, supported by public weather budgets and hyperscaler proximity. Asia Pacific is the fastest-growing region, with India at about 23.7% CAGR and China at about 23.0% CAGR through the forecast period.
NVIDIA, Google, Microsoft and AWS lead on infrastructure and foundational models. Specialists such as ClimateAi, Jupiter Intelligence, Tomorrow.io, IBM, Spire Global and DTN compete on hazard-specific validation, operational forecasting and portfolio risk analytics.
Software is the largest component at roughly 70% of 2025 revenue, machine learning leads technology at about 58%, and weather forecasting is the largest application. Workflow automation is the fastest-rising application as outputs move into alert routing and planning systems.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain with climate modelling software developers, Earth observation and satellite data providers, cloud and high-performance computing platform operators, specialist climate risk analytics firms, and public weather agencies and research institutions. Within these organizations we engaged decision-makers holding titles including Chief Technology Officer, Head of Climate Science, VP of Product for Risk Analytics, and Director of Public Sector Programs to capture procurement criteria, validation requirements and deployment economics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CTOs & Heads of Climate Science | 36% |
| Product & Risk Analytics Leads | 30% |
| Public Sector Program Directors | 20% |
| Procurement & Compliance Managers | 14% |
| Company Type | Representation (%) |
|---|---|
| Climate Modelling Software Developers | 38% |
| Earth Observation & Data Providers | 27% |
| Cloud & HPC Platform Operators | 21% |
| Public Weather Agencies & Research Institutes | 14% |
Secondary validation draws on official multilateral and regulatory sources, including UN Comtrade and WTO trade statistics for computing and Earth observation equipment, Eurostat and US International Trade Commission filings, corporate annual reports and SEC 10-K filings from listed technology providers, patent databases for machine learning and downscaling methods, and recognized technical standards bodies and non-profit industry associations active in meteorological and geospatial data governance. No competitor market-research publications are cited as validation sources.
Sizing is triangulated simultaneously from the top down and bottom up. The top-down track allocates macroeconomic technology spend and public meteorological budgets across application and end-use segments. The bottom-up track models vendor-level software licence, API consumption and managed-platform revenue alongside service engagement values, reconciled against disclosed segment revenues and deployment counts.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up revenue triangulation against disclosed segment data | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Public budget analysis and regional consumption modelling | High |
| Competitive Landscape | Leading market players | Annual reports, product filings and deployment mapping | High |