 Edge Ai Market
Edge AI Market Size, Growth & Forecast to 2035
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 237

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Edge Ai Market
Srinwanti Kar
Senior Research Analyst

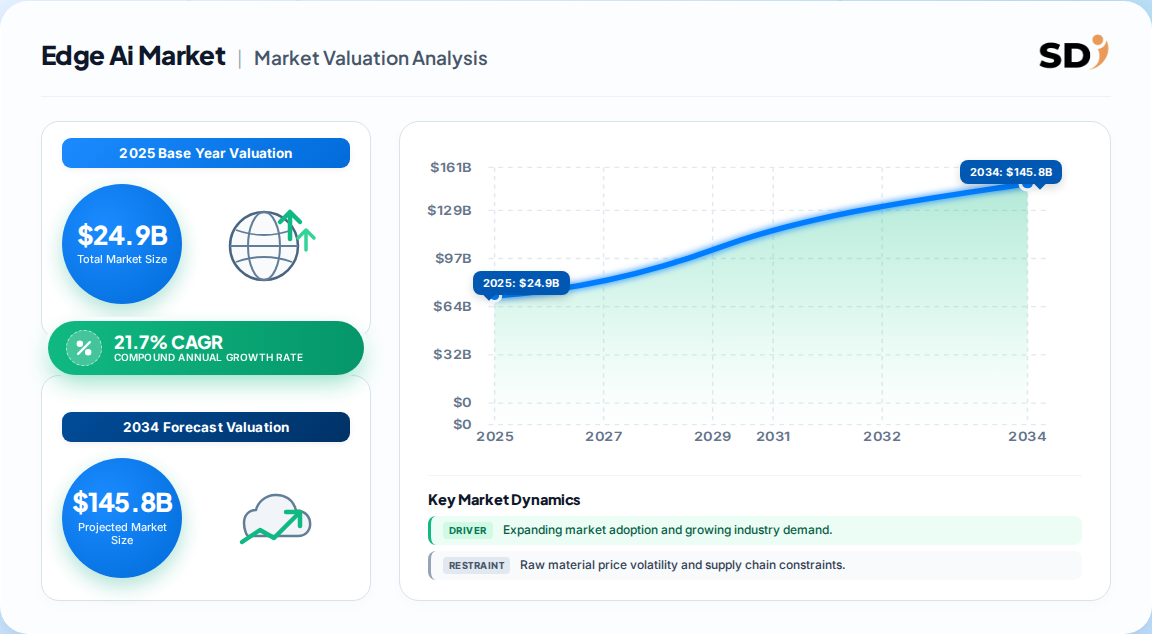
| Year | Market Size |
|---|---|
| 2025 | 24.90 B |
| 2026 | 30.00 B |
| 2027 | 36.50 B |
| 2028 | 44.40 B |
| 2029 | 54.10 B |
| 2030 | 65.80 B |
| 2031 | 80.10 B |

The Edge AI market covers hardware, software, edge cloud infrastructure and services that execute trained AI models locally — on devices, gateways and on-premise servers near the data source — to deliver low-latency inference, localized decision-making and reduced raw-data transfer to centralized cloud environments.
This analysis covers global Edge AI spending across four components (hardware, software, edge cloud infrastructure, services) and four primary end-use verticals (consumer electronics, smart cities, manufacturing, automotive), with regional splits for North America, Europe, Asia-Pacific, Latin America and Middle East & Africa. This analysis does not cover centralized data-center AI training infrastructure, general cloud computing spend, or classical (non-AI) embedded control electronics.
Estimates converge tightly on the 2025 base year but diverge sharply on the horizon, so buyers should anchor on the base and treat long-range figures as directional.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 24.9 Billion | 2025 | 2033 (USD 118.7B) | 21.7% | Edge AI hardware, software, edge cloud, services | One published estimate |
| USD 25.2 Billion | 2025 | 2035 (USD 225.5B) | 24.7% | Device, gateway and local-server inference; silicon through orchestration | A competing analysis |
| USD 30.0–30.9 Billion | 2026 | Mid-2030s | ~22–25% | Same architecture, differing service and integration inclusion | Synthesized range |
Our analysis suggests the 2025 base figures (~USD 25 Billion) are defensible because two independent estimates land within 1.2% of each other. The ten-year divergence to USD 225.5 Billion implies aggressive assumptions about managed-fleet services and software attach rates rather than silicon volume alone. The 21.7% path is the more conservative planning basis.
Segmentation splits along component and end-use lines, with hardware monetizing earliest and services compounding latest as fleets scale.
| Parent Segment | Children |
|---|---|
| By Component | Hardware, Software, Edge Cloud Infrastructure, Services |
| By End Use | Consumer Electronics, Smart Cities, Manufacturing, Automotive |
Hardware's 51.8% share reflects the capital intensity of inference silicon. However, services — consulting, training, lifecycle support — are the margin-accretive layer, and our analysis suggests services will outgrow hardware on a percentage basis post-2028 as installed fleets require model versioning and security patching.
North America leads with 36.0% of 2025 revenue, but Asia-Pacific is the fastest-growing region, driven by device manufacturing concentration and rapid 5G deployment.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.22% |
| Asia-Pacific | 0.31% |
| South America | 0.05% |
| Middle East & Africa | 0.06% |
The U.S. lead rests on enterprise platform investment and hyperscaler-adjacent hybrid architectures. This divergence implies Asia-Pacific's growth will be hardware-weighted, while North America's is software- and governance-weighted — a distinction that changes which vendors win each region.
Connected endpoints and operational AI workloads are the dominant driver, while security exposure and multi-vendor fleet complexity are the binding restraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Proliferating connected endpoints | Driver (+~9.4% CAGR impact) | High | 18.5B IoT connections end-2024; operational decisions need local interpretation |
| 5G and hybrid-cloud infrastructure | Driver (+~7.8%) | High | 2.25B 5G connections; private networks in ports and factories |
| Capital formation and platform investment | Driver (+~5.6%) | Medium | Vendor R&D and governance tooling lower deployment risk |
| Security, privacy, compliance exposure | Restraint (−~3.1%) | High | Distributing risk across physically accessible, hard-to-patch devices |
| Interoperability and fleet complexity | Restraint (−~2.4%) | Medium | Multi-vendor industrial and enterprise deployments |
Our analysis suggests the net balance is strongly positive but structurally uneven: drivers scale with endpoint count, while restraints scale with fleet heterogeneity. That means the constraint tightens fastest exactly where value is highest — large multi-vendor industrial estates.
Qualcomm led 2025 with over 15.6% share, and the top five players collectively held roughly 48.5%, indicating a concentrated but not closed oligopoly.
| Vendor | Position | Core moat |
|---|---|---|
| Qualcomm | Leader, >15.6% share | Mobile/embedded SoC integration and IoT roadmap |
| NVIDIA | Top five | Accelerator performance and AI software ecosystem |
| Intel | Top five | Broad edge portfolio (Core Ultra, Atom, Arc, Gaudi) and lifecycle support |
| MediaTek | Top five | Cost-efficient consumer and connectivity silicon |
| AMD | Top five | Compute density and adaptive SoC portfolio |
Differentiation is shifting from raw TOPS to lifecycle tooling. Our analysis suggests the durable moat is silicon-plus-runtime-plus-orchestration bundled as one stack, because a benchmark-leading device that cannot be securely updated across a fleet becomes an operational liability.
Selection criteria should weight updateability, security posture and validation evidence above headline inference performance. Buyers in safety-sensitive or regulated environments must separate a proof of concept from a deployable architecture on three dimensions: patch lifecycle, model version control and validated behavior across the fleet.
Procurement risk concentrates in multi-vendor interoperability. Switching costs rise steeply once orchestration tooling and model pipelines are embedded in operational technology, so lock-in is less about silicon price and more about management-plane integration. Regulatory exposure — particularly in Europe — adds compliance burden on data locality and firmware integrity. Federated learning reduces raw-data transfer but does not eliminate gradient-level information exposure, so security review must cover the training loop, not just inference.
The balance of evidence favors the conservative 21.7% CAGR path anchored on the ~USD 25 Billion 2025 base, not the 24.7% long-horizon extrapolation to USD 225.5 Billion. Both base estimates agree within 1.2%, which is strong corroboration; the horizon gap reflects differing assumptions about software attach and managed services rather than disagreement about silicon demand. The strongest counter-argument is that service-layer monetization could compound faster than hardware, in which case the aggressive path proves right — but that thesis depends on fleets becoming managed, which is precisely where interoperability and security restraints bite.
For operators, the second-order effect is a margin migration: silicon becomes commoditized at the low end while orchestration, security and lifecycle tooling capture durable value. Vendors that ship only accelerators face price competition from lower-cost developer hardware; vendors that bundle runtime and fleet management convert pilots into recurring revenue and higher switching costs.
Actionable strategy:
What would change our conclusion: sustained evidence that managed-fleet attach rates exceed hardware growth by 2028, or regulatory clarity that lowers compliance cost in Europe, would justify shifting to the aggressive forecast.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 21.7% from 2020-2034 |
| Segmentation |
|
The global Edge AI market is estimated at USD 30.0 Billion in 2026, up from roughly USD 24.9–25.2 Billion in 2025. Growth reflects enterprise deployment of local inference across manufacturing, automotive and consumer devices.
Published estimates range from 21.7% to 24.7% over the 2026–2035 horizon. We anchor planning on 21.7% because two independent base-year estimates agree within 1.2%, making the conservative path more defensible.
North America holds 36.0% of 2025 revenue, driven by enterprise platform investment and mature hybrid-cloud architectures. Asia-Pacific is the fastest-growing region on device manufacturing and rapid 5G deployment.
Hardware accounts for 51.8% of 2025 revenue, led by NPUs and inference-capable SoCs. Consumer electronics is the largest end-use vertical, with manufacturing and automotive growing fastest.
Qualcomm leads with over 15.6% of 2025 revenue. NVIDIA, Intel, MediaTek and AMD complete a top five that collectively held roughly 48.5%, indicating a concentrated but competitive landscape.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured in-depth interviews were conducted across the Edge AI value chain with semiconductor and module suppliers, edge-compute platform developers, system integrators and OEMs, and enterprise and industrial end users. Interviewees included VP-level Sourcing and Procurement leads, Heads of AI and Embedded Engineering, Technical Directors, and Commercial Operations Leads responsible for edge deployment budgets.
| Stakeholder Role | Interview Share (%) |
|---|---|
| AI & Embedded Engineering Heads | 38% |
| Procurement & Sourcing Leads | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 12% |
| Company Type | Representation (%) |
|---|---|
| Semiconductor & Module Suppliers | 32% |
| Edge Platform & Software Vendors | 28% |
| System Integrators & OEMs | 24% |
| Industrial & Enterprise End Users | 16% |
Secondary validation draws on official multilateral trade and standards databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K and equivalent disclosures), patent filing databases, and recognized technical standards bodies and industry associations. No third-party market-research publications are used as source inputs.
We run simultaneous top-down and bottom-up models. Top-down allocates macroeconomic and industry-segment spend to edge inference workloads; bottom-up models supplier capacity, device pricing and end-use consumption. Convergent results are accepted; divergences are re-interrogated against interviews.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |