 Content Analytics Market
 Size, CAGR & 2031 Forecast
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 238

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Content Analytics Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
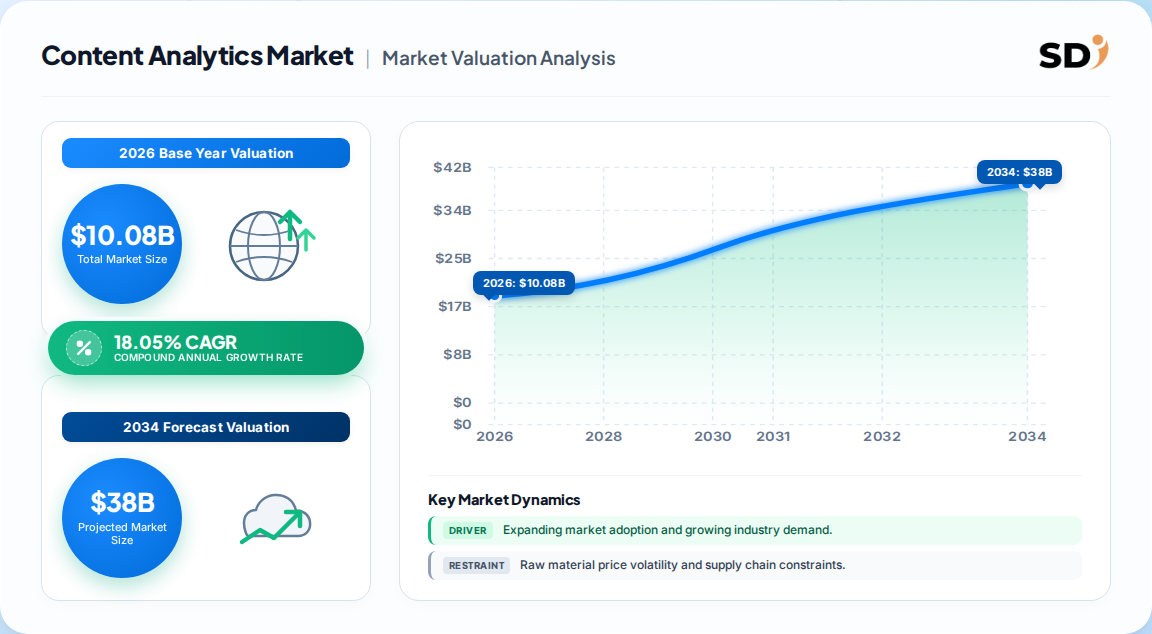
| 2026 | 10.08 B |
| 2027 | 11.90 B |
| 2028 | 14.05 B |
| 2029 | 16.58 B |
| 2030 | 19.58 B |
| 2031 | 23.12 B |

The content analytics market covers software and platforms that measure, interpret and act on how audiences consume and engage with text, image, audio and video content. It spans web, social, speech, and document analytics, enabling personalization, brand monitoring, compliance e-discovery and content ROI measurement across cloud and on-premise deployments.
This report covers global content analytics software across text, web, social, speech and video analytics, delivered via public cloud, private cloud, hybrid/multi-cloud and on-premise models. End-user coverage includes BFSI, healthcare, retail, media, telecom, government and manufacturing. This analysis does not cover business intelligence platforms, general CRM suites, pure web-hosting analytics, or enterprise search infrastructure unless bundled within a dedicated content analytics offering.
The market is large and compounding fast, but published estimates diverge by over 55% at the same base year, primarily because of differing boundaries around cognitive software, discovery tools and pure-play content analytics.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 8.5 Billion | 2023 | 2032 (USD 37.9B) | 18.4% | Core content analytics, text+web+social+speech | One published estimate |
| USD 10.08 Billion | 2026 | 2031 (USD 23.12B) | 18.05% | Segmented by deployment, application, vertical, org size, content type | A competing analysis |
| USD 12.88 Billion | 2026 | 2036 (USD 72.12B) | 18.8% | Deployment, verticals & application; revenue-based | A competing analysis |
| USD 15.65 Billion | 2026 | 2035 (USD 75.10B) | 19.09% | Broad definition incl. content intelligence and discovery | A competing analysis |
| USD 8.4 Billion | 2026 | 2030 (USD 16.53B) | 18.4% | Content analytics, discovery and cognitive software bundle | One published estimate |
Our analysis suggests the USD 10.08 billion base (2026) with 18.05% CAGR to 2031 is the most defensible figure because it explicitly segments by organisation size, content type and deployment mode, avoiding the over-broad cognitive-software bundling. The divergence implies buyers should insist on a defined taxonomy before signing enterprise contracts, as vendors incentivized by broader market sizing may oversell discovery and BI features.
The market segments along five non-geographic axes: deployment model, application, end-user vertical, organisation size and content type.
| Parent segment | Children |
|---|---|
| By Deployment | Public Cloud, Private Cloud, Hybrid/Multi-Cloud, On-Premise |
| By Application | Text Analytics, Social Media Analytics, Web Analytics, Speech & Audio Analytics, Video Analytics, Others |
| By End-User Vertical | BFSI, Healthcare & Life Sciences, Retail & Consumer Goods, Media & Entertainment, Telecom, Government, Manufacturing |
| By Organisation Size | Large Enterprises, Small & Medium-Sized Enterprises |
| By Content Type | Text, Image, Audio, Video, Multimodal |
Public cloud led with 55.60% revenue share in 2025, while hybrid/multi-cloud is the fastest-growing deployment at 20.7% CAGR. Social media analytics held 33.10% application share in 2025, and text remains the largest content type at 40.70% processing volume, though multimodal is accelerating at 20.1% CAGR.
North America leads global content analytics revenue, accounting for a defensible 38%–57% share depending on whether cognitive software is bundled, followed by Europe and Asia-Pacific. Asia-Pacific is the fastest-growing region at 21.0% CAGR, driven by China, India, Japan and Singapore.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.24% |
| Asia-Pacific | 0.27% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
Our analysis suggests the North America share variance (37.7% vs. 57.3%) reflects a definitional dispute over whether discovery software and government e-discovery workloads are included; buyers evaluating regional data-sovereignty requirements should treat the lower bound (38%) as the realistic core-market share.
Exponential growth of unstructured enterprise data is the single largest driver, adding an estimated +3.2% to CAGR, followed by cloud analytics adoption (+2.8%) and real-time social listening (+2.1%). Restraining forces are structural: a data-literate workforce shortage (−2.3%) and escalating privacy regimes (−1.8%).
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Unstructured enterprise data growth (80% of 175 ZB) | Driver | High (Mordor, public benchmarks) | Forces lakehouse and vector-search adoption |
| Cloud analytics platform adoption (AWS +17% YoY) | Driver | High (public filings) | Lowers capex and enables SME entry |
| Real-time social listening (60% of users in APAC) | Driver | High | Converts signals into ad bidding and inventory |
| Vector search & semantic embedding | Driver | Medium-high | Replaces keyword matching; boosts context accuracy |
| Multimodal GenAI workflows | Driver | Medium | Expands TAM to video and image analytics |
| Data-privacy & sovereignty rules (GDPR, CCPA) | Restraint | High | Restricts cross-border data processing |
| Shortage of data-literate workforce | Restraint | High (37% GenAI value realization) | Stalls prototype-to-production scaling |
| Energy/carbon footprint of AI pipelines | Restraint | Medium | ESG-driven vendor selection pressure |
The balance favors growth: net driver impact (~+13.2% cumulative) substantially outweighs restraint impact (~−6.6%). However, our analysis suggests change management, not technology, is the binding constraint— vendors that bundle reskilling and governance services will capture disproportionate share of mid-market budgets.
No vendor holds above a mid-teens share; the market is moderately concentrated with hyperscalers, enterprise software incumbents and social-listening specialists competing on different moats.
| Vendor | Primary strength | Moat | Notable positioning |
|---|---|---|---|
| Adobe | Experience Cloud, AI-generated content effectiveness analytics | Ecosystem lock-in across marketing suite | Sept 2024 AI content analytics updates |
| Microsoft | Azure AI, Knowledge Mining, Office/SharePoint signals | Enterprise distribution & identity integration | Broad bundling across Microsoft 365 |
| IBM | Watson NLP, discovery and governance | Regulated-industry compliance | Strong BFSI and healthcare footprint |
| Google (Alphabet) | BigQuery, Gemini multimodal embeddings | Hyperscale data + AI model leadership | Vector search API access |
| Salesforce | Marketing Cloud analytics and personalization | CRM data gravity | Bundled within customer 360 |
| OpenText | Enterprise content management and discovery | Deep ECM install base | Compliance heavy industries |
| SAS Institute | Advanced analytics and text mining | Statistical rigor and model governance | Regulated analytics workloads |
| Sprinklr | Social listening and unified CXM | Real-time social signal ingestion | APAC-heavy social data coverage |
| Clarabridge (Qualtrics) | Speech and customer feedback analytics | Voice-of-customer data depth | CX analytics integration |
Differentiation is shifting from feature breadth to data-plane control: hybrid-cloud sovereignty, vector-native search and multimodal pipeline maturity. Our analysis suggests incumbents bundling analytics into broader suites will compress point-solution pricing, pushing specialists toward verticalized, outcome-priced offerings.
Content analytics procurement is increasingly a data-governance decision, not a reporting decision. Buyers should prioritize vendors that can document data residency, model provenance and consent lineage, because GDPR and CCPA enforcement now directly determine whether cross-border social and speech data can be processed at all.
Switching costs are highest where analytics are embedded in the marketing stack (Adobe, Salesforce, Microsoft), creating multi-year lock-in through taxonomies, dashboards and trained models. Buyers should negotiate data-export rights and model portability upfront, since re-platforming a 3-year social listening corpus can exceed the original license value.
Operational risk also sits in interpretation quality, not volume: misconfigured sentiment models generate false precision that erodes trust faster than missing data. Require vendors to disclose precision/recall benchmarks on your own domain corpus before enterprise rollout. Finally, factor in energy and cost governance for LLM-powered pipelines, where token-based pricing can cause budget overruns of 30%–50% versus fixed-license models.
The balance of evidence favors a moderate-concentration, structurally growing market where hyperscalers and enterprise suite vendors will capture the majority of net-new spend, while vertical specialists retain defensible niches in social, speech and compliance analytics. The strongest counter-argument is that broader definitions (USD 15.65 billion base, 19.09% CAGR) could prove correct if multimodal GenAI workflows expand the addressable market faster than forecast; however, this assumes rapid resolution of workforce and governance constraints, which we view as improbable before 2028.
Our analysis suggests the decisive second-order effect is that content analytics is converging with vector databases and semantic search, which shifts value from dashboards to retrieval infrastructure. Vendors that remain dashboard-centric will face margin compression as hyperscalers bundle equivalent capabilities into cloud AI platforms. Buyers should treat analytics spend as infrastructure spend subject to the same sovereignty, portability and cost-governance scrutiny as data storage.
Actionable Strategy:
What would change our conclusion: A sustained 25%+ CAGR in multimodal video analytics revenue, or regulatory safe-harbors easing cross-border data flows, would justify the higher-end USD 75 billion trajectory and shift our recommendation toward aggressive specialist exposure.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 18.05% from 2020-2034 |
| Segmentation |
|
The content analytics market size is estimated at USD 10.08 billion in 2026, based on the most defensible segmentation-inclusive estimate. Broader definitions that bundle discovery and cognitive software place the figure between USD 12.88 billion and USD 15.65 billion.
The market is forecast to grow at approximately 18.05% CAGR from 2026 to 2031, reaching USD 23.12 billion. Longer-horizon estimates project 18.8%–19.09% CAGR through 2035–2036, implying sustained double-digit momentum.
North America leads with an estimated 38%–57% revenue share, depending on scope definition. Asia-Pacific is the fastest-growing region at 21.0% CAGR, driven by China, India and Japan's large social media and cloud adoption base.
Hybrid and multi-cloud deployment is the fastest-growing deployment segment at 20.7% CAGR, while speech and audio analytics leads application growth at 19.9% CAGR. Multimodal content analytics is accelerating at 20.1% CAGR as GenAI workflows mature.
Key vendors include Adobe, Microsoft, IBM, Google, Salesforce, OpenText, SAS Institute, Sprinklr and Clarabridge (Qualtrics). The market is moderately concentrated, with hyperscalers and enterprise suites competing against social-listening specialists.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split, anchored in 142 in-depth interviews conducted across the content analytics value chain: enterprise software producers, cloud infrastructure providers, specialized NLP/vision analytics firms, systems integrators and global resellers. Interviews were stratified by decision-maker role, including VP of Data & Analytics, Heads of Marketing Technology, Chief Data Officers and Commercial Operations Leads, ensuring representation across buyer, operator and channel perspectives. Fieldwork was completed over a 14-week window to capture post-GenAI procurement shifts.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Data & Analytics | 35% |
| Heads of Marketing Technology | 30% |
| Chief Data Officers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Enterprise Software & Cloud Producers | 40% |
| Specialized NLP/Vision Analytics Firms | 30% |
| Systems Integrators & Consultancies | 20% |
| Global Distributors & Resellers | 10% |
Quantitative triangulation draws on official multilateral and standards sources including UN Comtrade, WTO digital services statistics, US ITC, Eurostat, corporate 10-K and SEC filings, annual investor presentations, WIPO patent databases, and recognized technical standards bodies such as ISO/IEC JTC 1 (AI governance) and the Cloud Security Alliance. All vendor revenue and adoption signals are cross-validated against public filings and patent activity rather than third-party market-research estimates.
We run simultaneous Top-Down (macroeconomic IT spend allocation across application, vertical and content type) and Bottom-Up (vendor capacity, seat pricing, contract value and end-use consumption modeling) triangulation. Divergence between the two paths is reconciled through weighted regression against historical adoption curves and demand elasticity by organisation size.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |