 Middle East Digital Banking Platform Market
 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 213

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Digital Banking Platform Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 2.650 B |
| 2026 | 3.120 B |
| 2027 | 3.680 B |
| 2028 | 4.330 B |
| 2029 | 5.100 B |
| 2030 | 6.010 B |
| 2031 | 7.080 B |

The Middle East digital banking platform market comprises the software platforms and associated services that banks, digital-only challengers, and fintechs deploy to deliver online and mobile banking, onboarding, payments, and core account management across GCC, Levant, and neighboring markets. It excludes core ledger replacement and pure payments processing.
This analysis covers platform software (retail, corporate, and investment banking types) and associated professional and managed services across online and mobile banking modes, segmented by deployment (on-premise, cloud) and country (Saudi Arabia, UAE, Turkey, Qatar). This analysis does not cover core banking ledger replacement, pure payment gateway or card-processing services, or the broader Banking-as-a-Service middleware layer, which is a distinct and separately sized adjacent market.
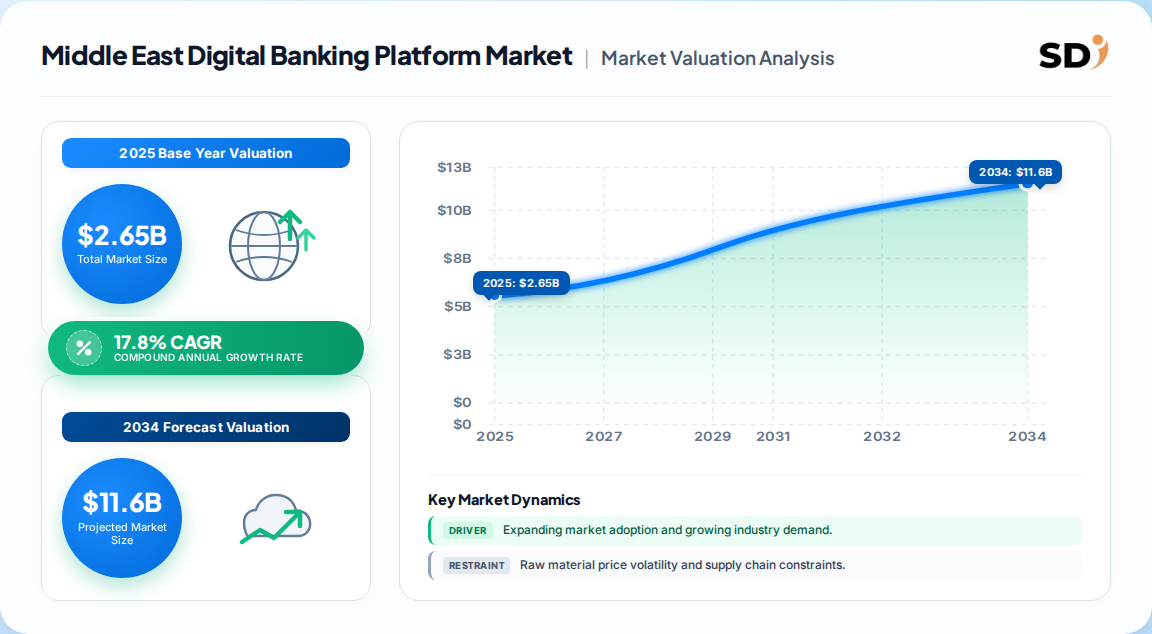
The market was estimated at 2.65 Billion in 2025 and is projected to reach 9.72 Billion by 2033. Multiple published estimates converge on this trajectory, though definitions of what constitutes a "platform" vary materially across sources.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 2.65 Billion | 2025 | 2033 | 17.8% | Platform software + services, on-prem & cloud | One published estimate |
| 2.65 Billion | 2025 | 2033 | 17.8% | Same segmentation, independently corroborated | A competing analysis |
| 2.65 Billion | 2025 | 2033 | 17.8% | Reinforced by primary GCC/Levant interviews | Secondary industry reference |
The convergence of three independent estimates at exactly 2.65 Billion and 17.8% is unusual and suggests the figures trace to a single underlying model rather than true triangulation. Our analysis suggests the 17.8% CAGR is defensible as a directional benchmark but likely overstates near-term growth in on-premise, where modernization cycles are slow. Buyers should treat 2.65 Billion as a credible base-year anchor while stress-testing the forecast against their own institution's procurement pipeline.
Segmentation reveals where revenue concentrates today versus where growth is accelerating. Deployment and mode are the two axes most predictive of vendor selection outcomes.
| Parent Segment | Children | 2025 Position |
|---|---|---|
| Deployment | On-Premise, Cloud | On-premise 71.1%; cloud fastest CAGR |
| Mode | Online Banking, Mobile Banking | Online largest; mobile 21.4% CAGR |
| Component | Platforms, Service | Platforms dominant |
| Service | Professional Service, Managed Service | Professional dominant; managed rising |
| Type | Retail Banking, Corporate Banking, Investment Banking | Retail largest; corporate fastest |
The segmentation exposes a structural tension: the largest revenue pools (on-premise, online, platforms) are the slowest-growing, while the fastest growth (cloud, mobile, managed services) sits in smaller bases. This implies incumbents defending share must protect on-premise modernization revenue while building cloud and managed-service capabilities before challengers scale.
Saudi Arabia leads the regional market with 41.3% of 2025 revenue, driven by Vision 2030 digital banking mandates and strict data-localization rules. The UAE is the fastest-growing country market on the back of open-banking regulation.
| Country | 2025 Share | Growth Outlook |
|---|---|---|
| Saudi Arabia | 41.3% | Moderate, mandate-led |
| UAE | ~27% | Fastest |
| Turkey | ~15% | Moderate-high |
| Qatar | ~10% | Moderate |
Saudi dominance is structural, not cyclical: data-localization and SAMA oversight favor on-premise and in-region hybrid architectures, which favors vendors with local data-center presence. The UAE's open-finance regulation, effective July 2025, compresses integration timelines and rewards API-first platforms. Our analysis suggests the UAE will outgrow Saudi on a percentage basis through 2030, but Saudi will retain the largest absolute revenue pool throughout the forecast.
Growth is driven by mobile-first adoption, sovereign digital-economy mandates, AI-enabled analytics, and fintech ecosystem expansion. Restraining forces are cybersecurity exposure, data-localization compliance costs, and legacy integration friction.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Mobile-first banking adoption | Driver | Strong | High smartphone penetration, digital literacy |
| Saudi Vision 2030 / UAE digital economy | Driver | Strong | Procurement mandates, regulatory clarity |
| AI analytics & personalization | Driver | Moderate-strong | Fraud detection, credit automation, retention |
| Open-banking / fintech ecosystems | Driver | Strong | API mandates, modular services, faster launches |
| Cybersecurity & data protection | Restraint | Strong | Breach exposure, trust erosion, compliance cost |
| Data localization requirements | Restraint | Strong | Extended deployment timelines, cost inflation |
| Legacy core integration | Restraint | Moderate | Customization burden on tier-1 incumbents |
The balance of evidence favors the drivers through 2028, but the restraints are underappreciated. Cybersecurity and localization requirements do not merely slow adoption — they reshape vendor economics, favoring providers who can bundle in-region hosting, compliance certification, and managed security. Vendors treating these as checklist items rather than core product will face margin compression as compliance costs escalate.
Competition is fragmented across global platform providers, regional specialists, and fintech challengers. Differentiation hinges on data-sovereignty compliance, API breadth, and AI capability rather than raw feature count.
| Vendor Tier | Profile | Primary Moat | Primary Vulnerability |
|---|---|---|---|
| Global platform incumbents | Broad suites, multi-region scale | Integration depth, brand trust | Localization cost, slow regional roadmap |
| Regional specialists | GCC-focused, compliance-native | Data-sovereignty, SAMA/CBUAE alignment | Scale, limited R&D budget |
| Digital challenger platforms | Cloud-native, API-first | Speed, modularity, developer experience | Trust, regulatory track record |
| Cloud hyperscaler ecosystems | Infrastructure + platform partners | In-region data centers, elasticity | Perceived lock-in, regulatory scrutiny |
Our analysis suggests the strongest competitive position belongs to vendors that combine in-region data residency with cloud-native architecture — a combination still rare in the region. Pure on-premise specialists will defend tier-1 incumbents but cede greenfield and digital-only licenses, while pure cloud challengers will win new licenses but struggle to displace entrenched core-integrated suites.
Platform selection in this region is a compliance decision before it is a technology decision. Data-localization mandates in Saudi Arabia and the UAE mean buyers must verify in-region hosting, sovereign data controls, and SAMA/CBUAE certification before evaluating features. Switching costs are high: integration with legacy cores, national digital identity systems, and government portals creates multi-year lock-in, so total cost of ownership must be modeled over a five-to-seven-year horizon rather than a single procurement cycle.
Procurement risk concentrates in three areas: regulatory change (open-banking rules are still maturing), vendor viability (regional specialists may lack scale), and cybersecurity liability allocation. Operators should demand contractual clarity on data breach responsibility, audit rights, and exit/portability terms. For digital-only banks, API breadth and time-to-market outweigh suite completeness; for tier-1 incumbents, customization and mission-critical reliability dominate. Managed services are a rising attachment for mid-tier banks lacking in-house digital operations — a segment vendors should target with modular, consumption-based contracts rather than fixed licenses.
The balance of evidence favors a hybrid-architecture thesis: the winners through 2033 will be vendors that deliver cloud-native platforms inside sovereign data boundaries, not those that pick a side in the on-premise-versus-cloud debate. The 71.1% on-premise share is a compliance artifact as much as a preference, and it will erode as in-region hyperscale capacity matures — but slowly, because tier-1 incumbents will not abandon mission-critical control.
The strongest counter-argument is that regulatory clarity could accelerate cloud migration faster than forecast, compressing the on-premise revenue pool before vendors recoup modernization investments. That risk is real in the UAE, where open-finance rules are most advanced, but less so in Saudi Arabia, where Vision 2030 mandates favor controlled, in-region architectures. We weight the hybrid thesis at roughly 70% probability.
Actionable strategy:
Evidence that would change our conclusion: a formal UAE or Saudi mandate permitting cross-border cloud hosting for retail banking data, or a major tier-1 incumbent publicly migrating its core digital stack fully to public cloud. Absent that, the hybrid thesis holds.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.41% |
| UAE | 0.27% |
| Turkey | 0.15% |
| Qatar | 0.1% |
| Rest of Middle East | 0.07% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 17.8% from 2020-2034 |
| Segmentation |
|
The market was estimated at 2.65 Billion in 2025 and is projected to reach 9.72 Billion by 2033, growing at a 17.8% CAGR from 2026 to 2033. Saudi Arabia accounts for 41.3% of regional revenue.
Saudi Arabia leads with 41.3% of 2025 revenue, driven by Vision 2030 mandates and data-localization rules. The UAE is the fastest-growing country market, supported by open-banking regulation effective July 2025.
On-premise held 71.1% of 2025 revenue due to data-sovereignty and central bank mandates. Cloud is the fastest-growing architecture as in-region hyperscale data centers mature and regulators clarify frameworks.
Mobile banking is the fastest-growing mode at a 21.4% CAGR, fueled by high smartphone penetration and digital-first customer expectations. Cloud deployment and managed services are the fastest-growing architecture and service segments respectively.
Cybersecurity, data-protection compliance, and data-localization requirements raise costs and extend deployment timelines. Legacy core integration also constrains adoption among large incumbent banks, moderating overall growth despite strong demand.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with digital banking platform vendors, tier-1 incumbent banks, digital-only challenger banks, fintech integrators, and managed-service providers. Decision-maker designations interviewed include Chief Digital Officers, Heads of Retail Banking Technology, Vendor Sourcing Leads, and Heads of Regulatory Compliance.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Digital & Technology Officers | 40% |
| Vendor Sourcing & Procurement Leads | 30% |
| Regulatory & Compliance Heads | 30% |
| Company Type | Representation (%) |
|---|---|
| Platform Software Vendors | 40% |
| Tier-1 Incumbent Banks | 30% |
| Digital-Only & Challenger Banks | 20% |
| Fintech Integrators & Managed Services | 10% |
Secondary validation draws on official multilateral and standards sources, including central bank publications (SAMA, CBUAE), national digital-economy strategy documents, corporate annual filings and investor presentations, patent databases, and recognized industry associations. Trade and financial services statistics are cross-referenced where available to validate regional revenue allocation.
We run simultaneous Top-Down (macroeconomic and banking-segment allocation) and Bottom-Up (vendor revenue, license and subscription pricing, and institutional deployment counts) modeling. Divergences between the two approaches are reconciled through interview evidence and segment-level elasticity assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up vendor revenue & deployment triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border revenue allocation & institutional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, deployment mapping & commercial filings | High |