Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Medical Terminology Software Market: 2024–2030 Outlook
Medical Terminology Software Market: 2024–2030 Outlook
Medical Terminology Software Market
Medical Terminology Software Market: 2024–2030 Outlook
Medical Terminology Software Market by Product Type (Platforms, Services, Integrated Platforms), by Application (Clinical Guidelines, Clinical Trials & RWE, Data Aggregation, Data Integration, Decision Support, Public Health Surveillance, Quality Reporting, Reimbursement), by End User (Healthcare Providers, Healthcare IT Vendors, Healthcare Payers, Others), by Deployment Mode (Cloud-Based, On-Premise), by Organization Size (Large Enterprises, SMEs), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Nordics), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 217
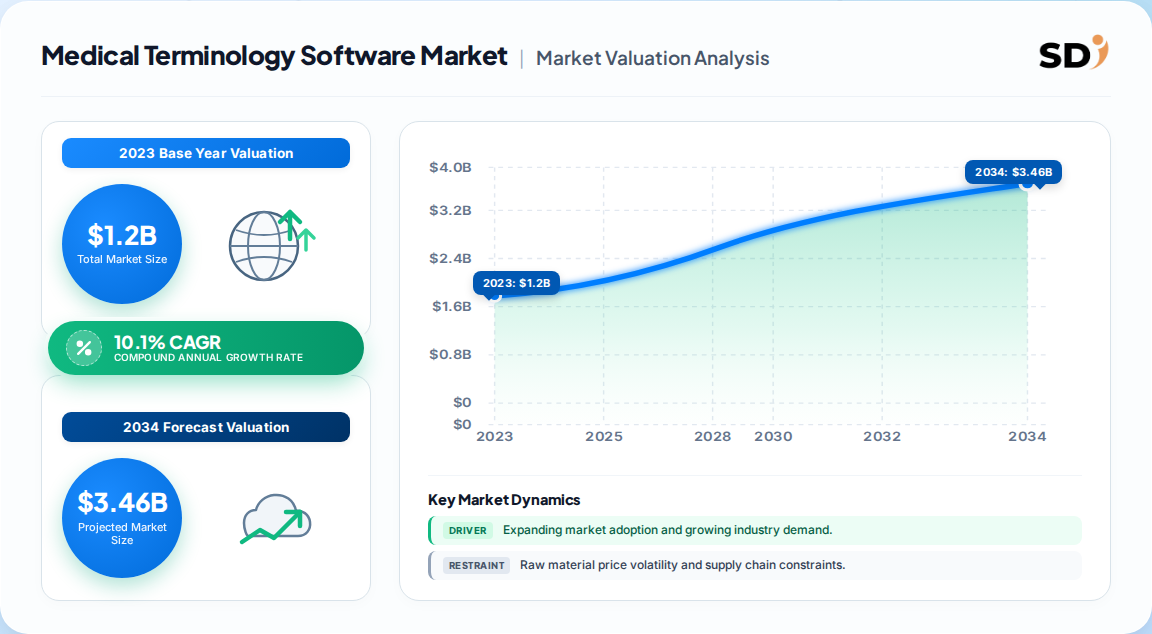
The global medical terminology software market was valued at USD 1.2 billion in 2023 and is projected to reach USD 2.3 billion by 2030, growing at a 10.1% CAGR (2024–2030).
The healthcare providers end-use segment dominates demand, supported by EHR rollouts, clinical error reduction and compliance obligations.
Quality reporting and clinical decision support are the largest application pockets, with decision support growing fastest as AI-assisted clinical workflows scale.
North America remains the largest regional market at roughly 40–46% revenue share; Asia-Pacific is the fastest-growing region.
Platform-based products hold roughly 64% of product revenue, while services are the faster-growing component as outsourcing accelerates.
Cloud-based deployment now represents about two-thirds of revenue, reflecting the shift from legacy on-premise terminology servers.
Leading vendors include Wolters Kluwer N.V., Intelligent Medical Objects, Clinical Architecture, InterSystems, Solventum (formerly 3M Health Information Systems) and Apelon.
Why this matters for decision-makers: buyers should prioritize FHIR-native, cloud-ready terminology platforms with automated mapping and continuous content updates to avoid compliance and interoperability penalties.
Medical Terminology Software Market Size (In Billion)
2.5B
2.0B
1.5B
1.0B
500.0M
0
1.200 B
2023
1.320 B
2024
1.450 B
2025
1.600 B
2026
1.760 B
2027
1.940 B
2028
2.130 B
2029
Medical Terminology Software Market Size (In Billion)
Year
Market Size
2023
1.200 B
2024
1.320 B
2025
1.450 B
2026
1.600 B
2027
1.760 B
2028
1.940 B
2029
2.130 B
What is the Medical Terminology Software Market?
The medical terminology software market covers platforms and services that normalize, map and manage clinical vocabularies such as SNOMED CT, ICD-11, LOINC and RxNorm across EHR, decision support and revenue-cycle workflows. The economic thesis is simple: standardized terminology is the substrate for interoperability, safe care and value-based reimbursement.
Scope: what this report covers and excludes
This analysis covers platform and service revenue from medical terminology management deployed by healthcare providers, payers, healthcare IT vendors, CROs and research institutions globally. It addresses clinical guidelines, clinical trials, data aggregation, data integration, decision support, public health surveillance, quality reporting and reimbursement applications. This analysis does not cover broader EHR/EMR systems, general clinical documentation software, or revenue-cycle management platforms, except where terminology modules attach.
How big is the market for Medical Terminology Software Market?
The most defensible reading is a market near USD 1.2–1.35 billion in the 2023–2025 base period, growing at a low-teens CAGR to roughly USD 2.3–5.5 billion by 2030–2035, depending on definition breadth and forecast horizon. The dispersion across published estimates reflects differences in scope (platform-only vs. platform+services) and horizon rather than genuine disagreement on direction.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 1.2B → USD 2.3B
2023
2030
10.1%
Platforms + services; end-use and application segments; global
Platforms (incl. integrated) + services; application and end-user split
A competing analysis
USD 1.38B → USD 2.30B
2026
2031
10.72%
Solutions + services; deployment, org size and end-user split
A competing analysis
Our analysis suggests the ~10–11% CAGR cluster is the most credible near-term anchor because it aligns with observed EHR/HCIT budget growth and the measured 6.1% pandemic-year uptick. The 15–20% forecasts embed aggressive AI-driven decision-support attach rates and a longer horizon, which are plausible but not yet evidenced at scale. Buyers should use the 10–11% band for planning and treat higher figures as upside scenarios.
How is the market segmented?
The market segments cleanly along product type, application, end user, deployment mode and organization size. Platform revenue dominates today, but services and cloud-based delivery are the fastest-growing slices, which materially changes vendor economics and buyer procurement models.
Parent segment
Children
By Product Type
Platforms, Services, Integrated Platforms
By Application
Clinical Guidelines, Clinical Trials & RWE, Data Aggregation, Data Integration, Decision Support, Public Health Surveillance, Quality Reporting, Reimbursement
By End User
Healthcare Providers, Healthcare IT Vendors, Healthcare Payers, Others (CROs, research institutes)
By Deployment Mode
Cloud-Based, On-Premise
By Organization Size
Large Enterprises, SMEs
Which region leads in Medical Terminology Software Market?
North America leads with roughly 40–46% revenue share, anchored by a mature EHR footprint, ONC HTI-1 mandates pushing USCDI v3/v4 migration, and the TEFCA exchange framework. Asia-Pacific is the fastest-growing region as public-sector digitization expands the addressable base.
Medical Terminology Software Market Regional Market Share
Loading chart...
Medical Terminology Software Market Regional Market Share
Region
Market Share (%)
North America
0.4%
Europe
0.27%
Asia-Pacific
0.24%
Latin America
0.05%
Middle East & Africa
0.04%
Global
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Nordics
Asia-Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Region
Share
North America
40%
Europe
27%
Asia-Pacific
24%
Latin America
5%
Middle East & Africa
4%
The divergence between North America's ~40% share and 46% in some estimates is definitional: broader application scopes dilute North America's share by adding emerging-market clinical-trial volume. This implies vendors should hedge US concentration risk by building EU Health Data Space and IDMP-ready capabilities early.
What is driving growth — and what is holding it back?
Growth is driven by government HCIT mandates, the need to reduce preventable medical errors (est. USD 122B annual US cost) and value-based care's demand for normalized, risk-adjustable data. Restraints are integration friction, high license cost and vocabulary customization gaps for specialty and multilingual workflows.
Factor
Direction
Evidence strength
Mechanism
Government HCIT incentives and mandates
Driver
High
ONC HTI-1, USCDI v3/v4, TEFCA and EU EHDS compel terminology upgrades
Medical error reduction imperative
Driver
High
Real-time terminology validation cut documentation errors up to 25% in year one
Value-based care data aggregation
Driver
Medium-High
Risk-bearing contracts require precise HCC capture and quality reporting
AI/NLP-enabled coding and mapping
Driver
Medium
Ambient documentation and auto-coding raise terminology attach rates
Interoperability and integration friction
Restraint
Medium
Legacy HL7 V2 to FHIR migration disrupts EHR workflows
High software and customization cost
Restraint
Medium
Deters SME adoption; specialty vocabularies require bespoke mapping
The balance favors growth: mandates are non-discretionary and penalty-backed (information-blocking fines up to USD 1M per infraction), while integration friction is a timing issue rather than a demand issue. Our analysis suggests the restraint most likely to cap near-term upside is buyer budget sequencing, not technology readiness.
Who are the leading vendors?
The vendor field is medium-concentration, with Wolters Kluwer's Health Language, Intelligent Medical Objects and Clinical Architecture holding strong content and EHR-integration positions. Differentiation rests on vocabulary breadth, update cadence, FHIR-native architecture and payer/provider workflow depth.
Vendor
Core offering
Differentiation
Moat
Wolters Kluwer N.V.
Health Language CIT/platform
Broad terminology content, EHR integrations (e.g., Henry Schein MicroMD)
Content library and installed base
Intelligent Medical Objects
Clinical interface terminology
Deep EHR partnerships (Epic, Cerner, Allscripts)
Workflow embedment; PE-backed (Thomas H. Lee)
Clinical Architecture
Nomentys (formerly Nomad)
USCDI v2 normalization, FHIR output, 21st Century Cures compliance
SaaS innovation and mapping engine
InterSystems
HealthShare terminology services
Interoperability and data platform adjacency
Enterprise data platform lock-in
Solventum (3M HIS)
Coding and terminology
Coding/classification heritage
Payer and provider coding trust
Apelon
Terminology management
Standards-focused deployments
Niche standards expertise
What do buyers and operators need to know?
Buyers should prioritize FHIR-native, cloud-ready platforms with automated mapping, real-time vocabulary updates and audit-ready compliance logs, because these directly determine interoperability certification and reimbursement eligibility. Procurement risk concentrates in integration effort and vocabulary customization—specialty and multilingual gaps frequently surface post-contract. Switching costs are high once terminology is embedded in EHR and analytics workflows, so pilots should test update latency, mapping accuracy and workflow disruption before enterprise commitment. Regulatory exposure (HIPAA/GDPR, information blocking, USCDI versioning) means compliance features are table stakes, not differentiators. Operators should model total cost including services, which grow at ~12% CAGR and can erode platform margin advantages.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the ~10–11% CAGR scenario, but the more important insight is structural: value is migrating from static terminology content to continuously updated, FHIR-native terminology services embedded in clinical and payer workflows. The strongest counter-argument is that AI-driven coding could commoditize basic mapping, compressing prices for standalone terminology tools; however, compliance-grade auditability and curated content remain defensible moats.
Our analysis suggests vendors that pair high-fidelity content with cloud-native delivery and automated update services will capture disproportionate share as USCDI v4 and EU EHDS timelines bite. Buyers who defer cloud migration risk penalty exposure exceeding 4% of Medicare revenue and face rising switching costs later.
Actionable strategy: vendors should prioritize FHIR-native terminology servers with automated USCDI/IDMP mapping to capture mandate-driven procurement in North America and EU.
Actionable strategy: investors should favor services-attached platform models, where recurring update and mapping revenue offsets platform pricing pressure.
Actionable strategy: providers should pilot real-time terminology validation in EHR workflows, targeting measurable documentation-error reduction within 12 months.
What would change this conclusion: evidence of faster-than-expected AI auto-coding commoditization, or a sharp slowdown in mandate enforcement, would lower the growth outlook and shift value toward services and compliance consulting.
Medical Terminology Software Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Medical Terminology Software Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.1% from 2020-2034
Segmentation
By Product Type
Platforms
Services
Integrated Platforms
By Application
Clinical Guidelines
Clinical Trials & RWE
Data Aggregation
Data Integration
Decision Support
Public Health Surveillance
Quality Reporting
Reimbursement
By End User
Healthcare Providers
Healthcare IT Vendors
Healthcare Payers
Others
By Deployment Mode
Cloud-Based
On-Premise
By Organization Size
Large Enterprises
SMEs
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Nordics
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Platforms
5.1.2. Services
5.1.3. Integrated Platforms
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Clinical Guidelines
5.2.2. Clinical Trials & RWE
5.2.3. Data Aggregation
5.2.4. Data Integration
5.2.5. Decision Support
5.2.6. Public Health Surveillance
5.2.7. Quality Reporting
5.2.8. Reimbursement
5.3. Market Analysis, Insights and Forecast - by End User
5.3.1. Healthcare Providers
5.3.2. Healthcare IT Vendors
5.3.3. Healthcare Payers
5.3.4. Others
5.4. Market Analysis, Insights and Forecast - by Deployment Mode
5.4.1. Cloud-Based
5.4.2. On-Premise
5.5. Market Analysis, Insights and Forecast - by Organization Size
5.5.1. Large Enterprises
5.5.2. SMEs
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Platforms
6.1.2. Services
6.1.3. Integrated Platforms
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Clinical Guidelines
6.2.2. Clinical Trials & RWE
6.2.3. Data Aggregation
6.2.4. Data Integration
6.2.5. Decision Support
6.2.6. Public Health Surveillance
6.2.7. Quality Reporting
6.2.8. Reimbursement
6.3. Market Analysis, Insights and Forecast - by End User
6.3.1. Healthcare Providers
6.3.2. Healthcare IT Vendors
6.3.3. Healthcare Payers
6.3.4. Others
6.4. Market Analysis, Insights and Forecast - by Deployment Mode
6.4.1. Cloud-Based
6.4.2. On-Premise
6.5. Market Analysis, Insights and Forecast - by Organization Size
6.5.1. Large Enterprises
6.5.2. SMEs
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Platforms
7.1.2. Services
7.1.3. Integrated Platforms
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Clinical Guidelines
7.2.2. Clinical Trials & RWE
7.2.3. Data Aggregation
7.2.4. Data Integration
7.2.5. Decision Support
7.2.6. Public Health Surveillance
7.2.7. Quality Reporting
7.2.8. Reimbursement
7.3. Market Analysis, Insights and Forecast - by End User
7.3.1. Healthcare Providers
7.3.2. Healthcare IT Vendors
7.3.3. Healthcare Payers
7.3.4. Others
7.4. Market Analysis, Insights and Forecast - by Deployment Mode
7.4.1. Cloud-Based
7.4.2. On-Premise
7.5. Market Analysis, Insights and Forecast - by Organization Size
7.5.1. Large Enterprises
7.5.2. SMEs
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Platforms
8.1.2. Services
8.1.3. Integrated Platforms
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Clinical Guidelines
8.2.2. Clinical Trials & RWE
8.2.3. Data Aggregation
8.2.4. Data Integration
8.2.5. Decision Support
8.2.6. Public Health Surveillance
8.2.7. Quality Reporting
8.2.8. Reimbursement
8.3. Market Analysis, Insights and Forecast - by End User
8.3.1. Healthcare Providers
8.3.2. Healthcare IT Vendors
8.3.3. Healthcare Payers
8.3.4. Others
8.4. Market Analysis, Insights and Forecast - by Deployment Mode
8.4.1. Cloud-Based
8.4.2. On-Premise
8.5. Market Analysis, Insights and Forecast - by Organization Size
8.5.1. Large Enterprises
8.5.2. SMEs
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Platforms
9.1.2. Services
9.1.3. Integrated Platforms
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Clinical Guidelines
9.2.2. Clinical Trials & RWE
9.2.3. Data Aggregation
9.2.4. Data Integration
9.2.5. Decision Support
9.2.6. Public Health Surveillance
9.2.7. Quality Reporting
9.2.8. Reimbursement
9.3. Market Analysis, Insights and Forecast - by End User
9.3.1. Healthcare Providers
9.3.2. Healthcare IT Vendors
9.3.3. Healthcare Payers
9.3.4. Others
9.4. Market Analysis, Insights and Forecast - by Deployment Mode
9.4.1. Cloud-Based
9.4.2. On-Premise
9.5. Market Analysis, Insights and Forecast - by Organization Size
9.5.1. Large Enterprises
9.5.2. SMEs
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Platforms
10.1.2. Services
10.1.3. Integrated Platforms
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Clinical Guidelines
10.2.2. Clinical Trials & RWE
10.2.3. Data Aggregation
10.2.4. Data Integration
10.2.5. Decision Support
10.2.6. Public Health Surveillance
10.2.7. Quality Reporting
10.2.8. Reimbursement
10.3. Market Analysis, Insights and Forecast - by End User
10.3.1. Healthcare Providers
10.3.2. Healthcare IT Vendors
10.3.3. Healthcare Payers
10.3.4. Others
10.4. Market Analysis, Insights and Forecast - by Deployment Mode
10.4.1. Cloud-Based
10.4.2. On-Premise
10.5. Market Analysis, Insights and Forecast - by Organization Size
10.5.1. Large Enterprises
10.5.2. SMEs
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Medical Terminology Software Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Medical Terminology Software Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Medical Terminology Software Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Medical Terminology Software Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Medical Terminology Software Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Medical Terminology Software Market Revenue (Billion), by End User 2026 & 2034
Figure 7: North America Medical Terminology Software Market Revenue Share (%), by End User 2026 & 2034
Figure 8: North America Medical Terminology Software Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 9: North America Medical Terminology Software Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 10: North America Medical Terminology Software Market Revenue (Billion), by Organization Size 2026 & 2034
Figure 11: North America Medical Terminology Software Market Revenue Share (%), by Organization Size 2026 & 2034
Figure 12: North America Medical Terminology Software Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Medical Terminology Software Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Medical Terminology Software Market Revenue (Billion), by Product Type 2026 & 2034
Figure 15: Europe Medical Terminology Software Market Revenue Share (%), by Product Type 2026 & 2034
List of Tables
Table 1: Medical Terminology Software Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Medical Terminology Software Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Medical Terminology Software Market Revenue Billion Forecast, by End User 2020 & 2034
Table 4: Medical Terminology Software Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 5: Medical Terminology Software Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 6: Medical Terminology Software Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Medical Terminology Software Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 8: North America Medical Terminology Software Market Revenue Billion Forecast, by Application 2020 & 2034
Table 9: North America Medical Terminology Software Market Revenue Billion Forecast, by End User 2020 & 2034
Table 10: North America Medical Terminology Software Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 11: North America Medical Terminology Software Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 12: North America Medical Terminology Software Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Medical Terminology Software Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Medical Terminology Software Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Medical Terminology Software Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the medical terminology software market?
The market was valued at approximately USD 1.2 billion in 2023 and is projected to reach USD 2.3 billion by 2030, growing at a 10.1% CAGR. Broader-scope estimates place the figure higher, but the ~10–11% growth band is the most defensible near-term anchor.
2. Which region leads the medical terminology software market?
North America leads with roughly 40–46% revenue share, driven by mature EHR adoption and ONC HTI-1 and TEFCA mandates. Asia-Pacific is the fastest-growing region as public-sector digitization expands the addressable base.
3. What are the main drivers of medical terminology software adoption?
Government HCIT mandates, the imperative to reduce preventable medical errors, value-based care's demand for normalized data, and AI-enabled clinical documentation are the primary drivers. Interoperability penalties make compliance non-discretionary for US providers.
4. Who are the leading vendors in the medical terminology software market?
Leading vendors include Wolters Kluwer N.V., Intelligent Medical Objects, Clinical Architecture, InterSystems, Solventum and Apelon. Differentiation rests on vocabulary breadth, update cadence, FHIR-native architecture and deep EHR workflow integrations.
5. What is the fastest-growing segment in medical terminology software?
Services and cloud-based deployment are the fastest-growing slices, with services expanding around a 12% CAGR and cloud platforms near 11%. Clinical decision support is the fastest-growing application as AI-assisted workflows scale.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis is built on a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including platform developers, clinical content providers, EHR/IT vendors, healthcare payer organizations and specialist terminology consultancies. Decision-maker designations interviewed include VP-level Clinical Informatics leads, Chief Medical Information Officers, Health IT Procurement Directors, and Regulatory Affairs Managers, ensuring demand signals are validated at both operational and executive levels.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Clinical Informatics & CMIO Leads
35%
Health IT Procurement Directors
30%
Regulatory & Compliance Managers
20%
Clinical Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Platform & Software Vendors
40%
Clinical Content Providers
25%
EHR/Health IT Vendors
20%
Payer & Consultancy Organizations
15%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral and standards sources, including UN Comtrade and WTO trade statistics, US ITC filings, Eurostat healthcare IT data, corporate annual reports and SEC 10-K filings, patent databases, and recognized technical standards bodies such as HL7, SNOMED International, WHO (ICD-11) and ONC certification registries. These sources anchor market sizing in verifiable regulatory and commercial activity rather than unverified estimates.
Demand Modeling & Market Sizing Triangulation
We triangulate Top-Down macroeconomic and healthcare IT segment allocation against Bottom-Up vendor revenue modeling, platform pricing, seat/enterprise licensing and end-use consumption patterns. Cross-checks against observed EHR adoption rates, mandate timelines and published contract values reconcile discrepancies across published estimates.
 Medical Terminology Software Market