Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Multimodal Artificial Intelligence Ai Market 2026
Multimodal Artificial Intelligence Ai Market 2026
Multimodal Artificial Intelligence Ai Market
Multimodal Artificial Intelligence Ai Market 2026
Multimodal Artificial Intelligence Ai Market by Component (Software, Services), by Data Modality (Text, Image, Audio & Speech, Video, Sensor/Multispectral), by Technology (Generative, Explanatory, Interactive, Translative, Computer Vision, NLP, Machine Learning), by Vertical (BFSI, Healthcare & Life Sciences, Manufacturing, Retail & E-Commerce, Media & Entertainment, Automotive, Government), by Enterprise Size (SMEs, Large Enterprises), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands), by Asia-Pacific (China, Japan, India, South Korea, Singapore), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 268
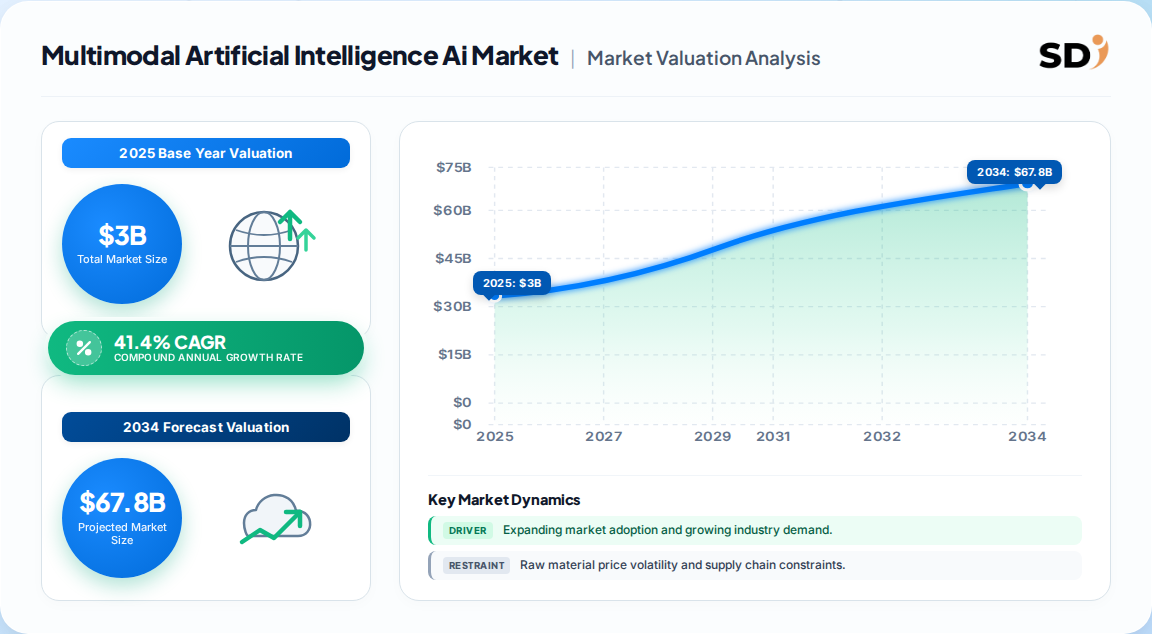
The global multimodal AI market was valued at USD 2.3 billion in 2025 and an estimated USD 3.0 billion in 2026, per one published estimate; scope: software, services, and multimodal models across all verticals.
Forecasts diverge sharply: 41.4% CAGR to USD 34.0 billion by 2033 (one analysis) versus 28.6% CAGR to USD 13.5 billion by 2031 (a competing estimate), a 2.5x gap by comparable horizons.
Software dominates at roughly 65–82% of revenue, but services grow fastest, with double-digit-plus premiums as integration complexity rises.
North America leads with 40–47% revenue share; Asia-Pacific is the fastest-growing region, with CAGRs near 40.9%.
Generative multimodal AI is the leading technology type (35–53% share); text remains the largest data modality, with speech/voice and video growing fastest.
Healthcare & life sciences and BFSI are the largest verticals; retail & e-commerce expands fastest at roughly 33% CAGR.
Why this matters for decision-makers: The forecast spread reveals definitional and pricing uncertainty. Operators should budget against the conservative curve (28–32% CAGR) while positioning product roadmaps for the upside scenario in voice, video, and agentic use cases.
Multimodal Artificial Intelligence Ai Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
2.300 B
2025
3.000 B
2026
4.200 B
2027
6.000 B
2028
8.500 B
2029
12.00 B
2030
16.90 B
2031
Multimodal Artificial Intelligence Ai Market Size (In Billion)
Year
Market Size
2025
2.300 B
2026
3.000 B
2027
4.200 B
2028
6.000 B
2029
8.500 B
2030
12.00 B
2031
16.90 B
What is the Multimodal Artificial Intelligence Ai Market?
Multimodal artificial intelligence (AI) refers to systems that simultaneously ingest, unify, and reason across text, image, audio, video, and sensor data to produce context-aware outputs. The market comprises software platforms, services, and models enabling enterprises to build and deploy such systems across customer experience, operations, and analytics workflows.
Scope: what this report covers and excludes
This report covers the global multimodal AI market across software platforms, integration and managed services, and embedded multimodal models spanning text, image, audio, video, and sensor modalities. It analyzes demand across BFSI, healthcare, manufacturing, retail, media, automotive, and public-sector use cases. This analysis does not cover unimodal AI tooling, general-purpose cloud infrastructure not specific to AI, AI chip fabrication, or the broader machine learning operations (MLOps) market except where directly tied to multimodal deployment.
How big is the market for Multimodal Artificial Intelligence Ai Market?
The market is estimated at roughly USD 2.3–3.3 billion in the 2025 base year, rising to USD 3.0–3.9 billion in 2026, on a path to between USD 13.5 billion (2031) and USD 34.0 billion (2033) depending on definitional scope. The table below reconciles the competing published estimates.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 2.3B → USD 34.0B
2025
2033
41.4%
Broad multi-modal AI incl. software, services, all verticals
Grand View-type analysis (anonymized)
USD 2.99B → USD 13.51B
2025
2031
28.59%
Multi-modal AI solutions & services, 2026–2031 window
Mordor-type analysis (anonymized)
USD 3.29B → USD 93.99B
2025
2035
39.81%
Multi-modal AI incl. translative sub-type, longer horizon
Roots-type analysis (anonymized)
Which figure is most defensible? Our analysis suggests the 28–32% CAGR band is the most conservative and defensible near-term anchor. The higher figures lean on extended horizons and broader scope (translative AI, full stack). Buyers should treat the 2031 estimate of ~USD 13.5 billion as a base case and the 41% CAGR path as an aggressive upside predicated on rapid agentic adoption.
How is the market segmented?
The market segments by component, data modality, technology type, vertical, and enterprise size. Software continues to dominate revenue, but services capture disproportionate growth as integration complexity rises.
Generative, Explanatory, Interactive, Translative, Computer vision, NLP, ML
Vertical
BFSI, Healthcare & life sciences, Manufacturing, Retail & e-commerce, Media & entertainment, Automotive, Government
Enterprise size
SMEs, Large enterprises
Generative multimodal AI leads at 35–53% share depending on scope; interactive agents and translative models are the fastest-growing sub-types. Text remains the foundational modality (44% share) while video processing grows fastest.
Which region leads in Multimodal Artificial Intelligence Ai Market?
North America leads the global multimodal AI market with an estimated 40–47% revenue share, driven by hyperscaler concentration, AI R&D investment, and early regulatory clarity. Asia-Pacific is the fastest-growing region, posting CAGRs near 40.9% on national foundation-model programs.
Multimodal Artificial Intelligence Ai Market Regional Market Share
Loading chart...
Multimodal Artificial Intelligence Ai Market Regional Market Share
Region
Market Share (%)
North America
0.44%
Europe
0.24%
Asia-Pacific
0.22%
Latin America
0.05%
Middle East & Africa
0.05%
Region
Share (2025)
North America
44%
Europe
24%
Asia-Pacific
22%
Latin America
5%
Middle East & Africa
5%
Regional tree:
North America (USA, Canada, Mexico)
Europe (Germany, UK, France, Italy, Netherlands)
Asia-Pacific (China, Japan, India, South Korea, Singapore)
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
What is driving growth — and what is holding it back?
Enterprise adoption across BFSI, healthcare, and manufacturing is the primary growth engine, supported by falling cloud-GPU costs and advances in transformer and diffusion architectures. Integration complexity and compute economics are the binding constraints.
Factor
Direction
Evidence strength
Mechanism
Enterprise multimodal adoption
Growth
High
+8.5% CAGR impact
Transformer/diffusion advances
Growth
High
Compute cuts up to 40%
Venture funding surge
Growth
Moderate
+4.8% CAGR impact
Cloud-GPU cost declines
Growth
Moderate
Up to 70% inference savings
Data integration complexity
Constraint
High
-4.2% CAGR drag
Compute & energy costs
Constraint
Moderate
-3.8% CAGR drag
Cross-modal benchmark scarcity
Constraint
Moderate
-2.9% CAGR drag
Net balance: growth drivers outpace restraints by a factor of roughly two. So what? The pacing item is integration, not model capability. Operators should budget 50–80% of deployment timeline for data harmonization.
Who are the leading vendors?
The market is moderately concentrated, with hyperscalers (Google, Microsoft, AWS, Meta) anchoring foundation models and a long tail of specialists in video understanding, voice, and vertical AI.
Vendor
Positioning
Moat
Google (Gemini)
Full-stack foundation models
Cloud + data + TPU
Microsoft (Azure AI)
Enterprise distribution
Office/enterprise lock-in
AWS (Bedrock)
Platform + tooling
Cloud scale
OpenAI
Frontier multimodal
Brand + research
Meta (Llama)
Open-weight models
Ecosystem gravity
Specialists (Twelve Labs, Uniphore, Reka)
Niche modalities
Vertical depth
Specialists differentiate through modality depth and vertical workflows; hyperscalers win on integration, pricing, and compliance. Our analysis suggests vertical specialists will be most exposed to acquisition risk as hyperscalers extend end-to-end stacks.
What do buyers and operators need to know? (Decision Support)
Procurement hinges on five criteria: model accuracy across modalities, total cost of inference, data governance and residency, integration with existing tooling, and roadmap velocity. Switching costs are substantial once a vendor's multimodal models are embedded in workflow pipelines, so pilot design should stress-test interoperability and exit paths.
Regulatory compliance (EU AI Act, sectoral privacy rules) increasingly shapes procurement, especially in healthcare and BFSI, where multimodal data carries heightened PII and clinical risk. Operators should demand transparency on training data provenance and benchmark coverage before committing to multi-year contracts. The biggest hidden risk is data-integration debt, which routinely consumes the majority of deployment timelines and erodes projected ROI.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a conservative-base, upside-aware posture: budget to the 28–32% CAGR curve, but architect for the agentic and voice/video use cases that could drive the higher scenario. The strongest counter-argument is that foundation-model leaps (e.g., unified reasoning across modalities) could collapse integration timelines and accelerate adoption well beyond the conservative case — a risk to under-investment.
For investors, the durable value sits in services and vertical specialists solving heterogeneous-data integration, not in undifferentiated model providers. For operators, the priority is interoperability and governance by design, not feature breadth. The forecast divergence itself is a signal: definitional ambiguity persists, and precision requires segment-level modeling.
Actionable strategy:
Operators: prioritize vendors with proven cross-modal data pipelines and transparent inference economics.
Investors: target services and vertical specialists exposed to healthcare, BFSI, and retail growth.
Vendors: build governance and interoperability moats as regulatory pressure intensifies.
What would change our conclusion: A sustained 40%+ CAGR over two consecutive years in agentic multimodal deployments, or a breakthrough in cross-modal benchmark standards, would validate the aggressive forecast path.
Multimodal Artificial Intelligence Ai Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Multimodal Artificial Intelligence Ai Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 41.4% from 2020-2034
Segmentation
By Component
Software
Services
By Data Modality
Text
Image
Audio & Speech
Video
Sensor/Multispectral
By Technology
Generative
Explanatory
Interactive
Translative
Computer Vision
NLP
Machine Learning
By Vertical
BFSI
Healthcare & Life Sciences
Manufacturing
Retail & E-Commerce
Media & Entertainment
Automotive
Government
By Enterprise Size
SMEs
Large Enterprises
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Asia-Pacific
China
Japan
India
South Korea
Singapore
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Software
5.1.2. Services
5.2. Market Analysis, Insights and Forecast - by Data Modality
5.2.1. Text
5.2.2. Image
5.2.3. Audio & Speech
5.2.4. Video
5.2.5. Sensor/Multispectral
5.3. Market Analysis, Insights and Forecast - by Technology
5.3.1. Generative
5.3.2. Explanatory
5.3.3. Interactive
5.3.4. Translative
5.3.5. Computer Vision
5.3.6. NLP
5.3.7. Machine Learning
5.4. Market Analysis, Insights and Forecast - by Vertical
5.4.1. BFSI
5.4.2. Healthcare & Life Sciences
5.4.3. Manufacturing
5.4.4. Retail & E-Commerce
5.4.5. Media & Entertainment
5.4.6. Automotive
5.4.7. Government
5.5. Market Analysis, Insights and Forecast - by Enterprise Size
5.5.1. SMEs
5.5.2. Large Enterprises
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia-Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Software
6.1.2. Services
6.2. Market Analysis, Insights and Forecast - by Data Modality
6.2.1. Text
6.2.2. Image
6.2.3. Audio & Speech
6.2.4. Video
6.2.5. Sensor/Multispectral
6.3. Market Analysis, Insights and Forecast - by Technology
6.3.1. Generative
6.3.2. Explanatory
6.3.3. Interactive
6.3.4. Translative
6.3.5. Computer Vision
6.3.6. NLP
6.3.7. Machine Learning
6.4. Market Analysis, Insights and Forecast - by Vertical
6.4.1. BFSI
6.4.2. Healthcare & Life Sciences
6.4.3. Manufacturing
6.4.4. Retail & E-Commerce
6.4.5. Media & Entertainment
6.4.6. Automotive
6.4.7. Government
6.5. Market Analysis, Insights and Forecast - by Enterprise Size
6.5.1. SMEs
6.5.2. Large Enterprises
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Software
7.1.2. Services
7.2. Market Analysis, Insights and Forecast - by Data Modality
7.2.1. Text
7.2.2. Image
7.2.3. Audio & Speech
7.2.4. Video
7.2.5. Sensor/Multispectral
7.3. Market Analysis, Insights and Forecast - by Technology
7.3.1. Generative
7.3.2. Explanatory
7.3.3. Interactive
7.3.4. Translative
7.3.5. Computer Vision
7.3.6. NLP
7.3.7. Machine Learning
7.4. Market Analysis, Insights and Forecast - by Vertical
7.4.1. BFSI
7.4.2. Healthcare & Life Sciences
7.4.3. Manufacturing
7.4.4. Retail & E-Commerce
7.4.5. Media & Entertainment
7.4.6. Automotive
7.4.7. Government
7.5. Market Analysis, Insights and Forecast - by Enterprise Size
7.5.1. SMEs
7.5.2. Large Enterprises
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Software
8.1.2. Services
8.2. Market Analysis, Insights and Forecast - by Data Modality
8.2.1. Text
8.2.2. Image
8.2.3. Audio & Speech
8.2.4. Video
8.2.5. Sensor/Multispectral
8.3. Market Analysis, Insights and Forecast - by Technology
8.3.1. Generative
8.3.2. Explanatory
8.3.3. Interactive
8.3.4. Translative
8.3.5. Computer Vision
8.3.6. NLP
8.3.7. Machine Learning
8.4. Market Analysis, Insights and Forecast - by Vertical
8.4.1. BFSI
8.4.2. Healthcare & Life Sciences
8.4.3. Manufacturing
8.4.4. Retail & E-Commerce
8.4.5. Media & Entertainment
8.4.6. Automotive
8.4.7. Government
8.5. Market Analysis, Insights and Forecast - by Enterprise Size
8.5.1. SMEs
8.5.2. Large Enterprises
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Software
9.1.2. Services
9.2. Market Analysis, Insights and Forecast - by Data Modality
9.2.1. Text
9.2.2. Image
9.2.3. Audio & Speech
9.2.4. Video
9.2.5. Sensor/Multispectral
9.3. Market Analysis, Insights and Forecast - by Technology
9.3.1. Generative
9.3.2. Explanatory
9.3.3. Interactive
9.3.4. Translative
9.3.5. Computer Vision
9.3.6. NLP
9.3.7. Machine Learning
9.4. Market Analysis, Insights and Forecast - by Vertical
9.4.1. BFSI
9.4.2. Healthcare & Life Sciences
9.4.3. Manufacturing
9.4.4. Retail & E-Commerce
9.4.5. Media & Entertainment
9.4.6. Automotive
9.4.7. Government
9.5. Market Analysis, Insights and Forecast - by Enterprise Size
9.5.1. SMEs
9.5.2. Large Enterprises
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Software
10.1.2. Services
10.2. Market Analysis, Insights and Forecast - by Data Modality
10.2.1. Text
10.2.2. Image
10.2.3. Audio & Speech
10.2.4. Video
10.2.5. Sensor/Multispectral
10.3. Market Analysis, Insights and Forecast - by Technology
10.3.1. Generative
10.3.2. Explanatory
10.3.3. Interactive
10.3.4. Translative
10.3.5. Computer Vision
10.3.6. NLP
10.3.7. Machine Learning
10.4. Market Analysis, Insights and Forecast - by Vertical
10.4.1. BFSI
10.4.2. Healthcare & Life Sciences
10.4.3. Manufacturing
10.4.4. Retail & E-Commerce
10.4.5. Media & Entertainment
10.4.6. Automotive
10.4.7. Government
10.5. Market Analysis, Insights and Forecast - by Enterprise Size
10.5.1. SMEs
10.5.2. Large Enterprises
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Multimodal Artificial Intelligence Ai Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Multimodal Artificial Intelligence Ai Market Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Multimodal Artificial Intelligence Ai Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Multimodal Artificial Intelligence Ai Market Revenue (Billion), by Data Modality 2026 & 2034
Figure 5: North America Multimodal Artificial Intelligence Ai Market Revenue Share (%), by Data Modality 2026 & 2034
Figure 6: North America Multimodal Artificial Intelligence Ai Market Revenue (Billion), by Technology 2026 & 2034
Figure 7: North America Multimodal Artificial Intelligence Ai Market Revenue Share (%), by Technology 2026 & 2034
Figure 8: North America Multimodal Artificial Intelligence Ai Market Revenue (Billion), by Vertical 2026 & 2034
Figure 9: North America Multimodal Artificial Intelligence Ai Market Revenue Share (%), by Vertical 2026 & 2034
Figure 10: North America Multimodal Artificial Intelligence Ai Market Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 11: North America Multimodal Artificial Intelligence Ai Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 12: North America Multimodal Artificial Intelligence Ai Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Multimodal Artificial Intelligence Ai Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Multimodal Artificial Intelligence Ai Market Revenue (Billion), by Component 2026 & 2034
Europe Multimodal Artificial Intelligence Ai Market Revenue Share (%), by Component 2026 & 2034
List of Tables
Table 1: Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Data Modality 2020 & 2034
Table 3: Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 4: Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Vertical 2020 & 2034
Table 5: Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 6: Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Component 2020 & 2034
Table 8: North America Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Data Modality 2020 & 2034
Table 9: North America Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 10: North America Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Vertical 2020 & 2034
Table 11: North America Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 12: North America Multimodal Artificial Intelligence Ai Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Multimodal Artificial Intelligence Ai Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Multimodal Artificial Intelligence Ai Market Revenue (Billion) Forecast, by Application 2020 & 2034
Mexico Multimodal Artificial Intelligence Ai Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the multimodal AI market in 2026?
The multimodal AI market is estimated at roughly USD 3.0–3.9 billion in 2026, depending on definitional scope. Published estimates converge on a base near USD 3 billion, with North America contributing around 44% of global revenue.
2. What is the multimodal AI market growth rate?
CAGRs range from 28.6% to 41.4%, with the spread driven by scope and horizon differences. Our base case anchors near 28–32%, while aggressive forecasts assume rapid agentic and voice/video adoption.
3. Which region leads the multimodal AI market?
North America leads with 40–47% revenue share, driven by hyperscalers and AI R&D concentration. Asia-Pacific is the fastest-growing region, with CAGRs near 40.9% on national foundation-model programs.
4. Who are the leading multimodal AI companies?
Google, Microsoft, AWS, OpenAI, and Meta anchor the market through foundation models and cloud distribution. Specialists such as Twelve Labs, Uniphore, and Reka compete on modality depth and vertical workflows.
5. What is driving multimodal AI adoption?
Enterprise demand across BFSI, healthcare, and manufacturing, combined with falling cloud-GPU costs and transformer advances, drives adoption. Data integration complexity and compute costs remain the primary constraints on scale.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the multimodal AI value chain, including foundation-model developers, cloud infrastructure providers, systems integrators and managed-service firms, vertical AI specialists, and enterprise end-users. Decision-makers interviewed include VP-level AI/Data Platform leaders, Heads of Enterprise Architecture, Chief Data Officers, and Commercial Operations Leads responsible for AI procurement.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP AI / Data Platform Leads
34%
Heads of Enterprise Architecture
28%
Chief Data Officers
22%
Commercial Operations Leads
16%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Foundation Model & Platform Providers
35%
Cloud Infrastructure & Hyperscalers
25%
Systems Integrators & Managed Services
22%
Vertical AI Specialists
18%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral and standards sources: UN Comtrade for cross-border technology services flows, WTO and US ITC digital-services trade data, Eurostat ICT statistics, corporate 10-K and SEC filings, annual investor presentations, patent databases, and recognized technical standards bodies including ISO/IEC JTC 1/SC 42 and IEEE AI standards committees.
Demand Modeling & Market Sizing Triangulation
We triangulate simultaneously via Top-Down allocation from macroeconomic AI spending and industry segment budgets, and Bottom-Up modeling of vendor revenue, cloud consumption, and end-use deployment counts. Divergent published estimates are reconciled by normalizing for scope (software vs. software+services) and horizon.
 Multimodal Artificial Intelligence Ai Market