 Cloud Point Of Sale Market
 Size, Share & 2031 Forecast
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 271

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Cloud Point Of Sale Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 6.260 B |
| 2026 | 7.320 B |
| 2027 | 8.560 B |
| 2028 | 10.02 B |
| 2029 | 11.72 B |
| 2030 | 13.70 B |
| 2031 | 16.01 B |

The Cloud Point Of Sale Market comprises software, services and mobile or fixed terminals that process sales, payments and inventory data over internet-connected cloud infrastructure, replacing on-premise cash-register servers. It serves retail, hospitality, healthcare, logistics and entertainment operators who need real-time, multi-location visibility.
This report covers cloud-hosted POS software (fixed and mobile), deployment models (public, private, hybrid), organization sizes (SME and large enterprise) and end-user industries across five global regions for the 2026–2031 forecast period. This analysis does not cover on-premise legacy POS hardware, standalone payment gateways, or general ERP suites unless bundled with a cloud POS platform.
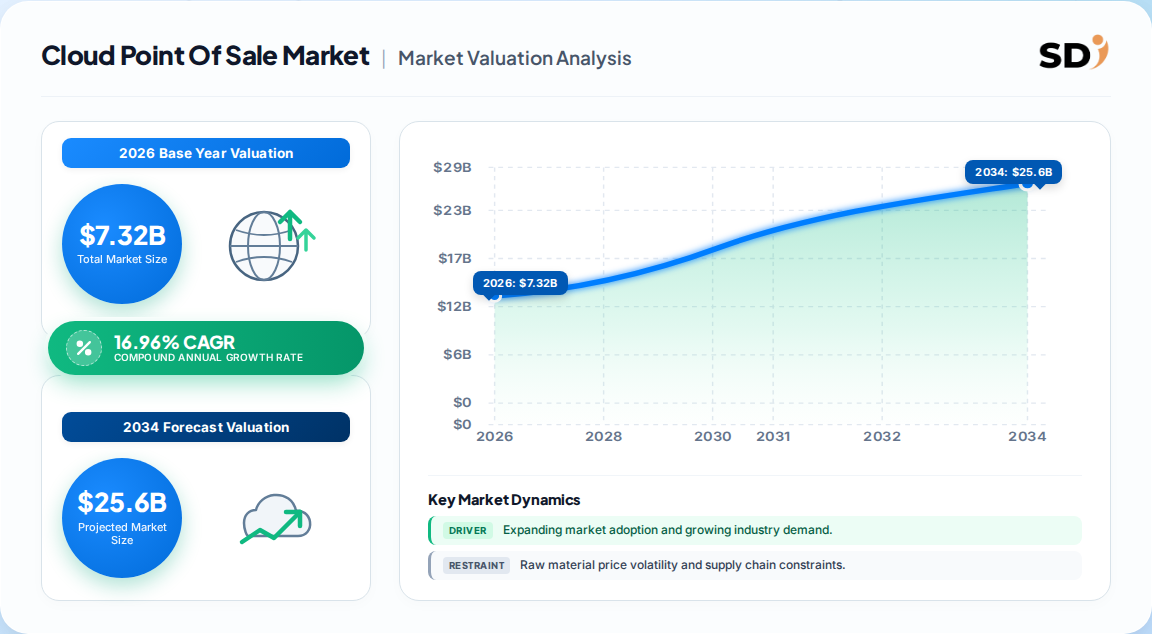
The most defensible base figure is the mid-range estimate: the global Cloud Point Of Sale Market sits near USD 7.32 billion in 2026, growing at roughly 17% to reach USD 16.01 billion by 2031. The table below compares published estimates and explains the divergence.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 3.0 Billion | 2021 | 2028 | 20% | Cloud POS software and services, all sizes | One published estimate |
| USD 7.32 Billion | 2026 | 2031 | 16.96% | Cloud POS software, services and terminals, all end-users | A competing analysis |
| USD 9.63 Billion | 2026 | 2034 | 24.7% | Broad cloud POS including adjacent retail IT | Another published estimate |
Our analysis suggests the divergence is driven less by demand assumptions than by definitional boundaries: the 24.7% CAGR figure folds in adjacent retail analytics and hardware, while the 16.96% figure isolates cloud POS software and terminals. The middle estimate is the most defensible for procurement and investment planning because its component and segment weights are publicly reconcilable. Buyers should anchor budgets to the 16–18% band and treat higher figures as upside scenarios.
Segmentation matters because the fastest-growing sub-segments (services, hybrid cloud, healthcare) carry different margin and procurement profiles than the volume leaders (software, public cloud, retail).
| Parent segment | Children | 2025–2026 share signal |
|---|---|---|
| Component | Software, Services (Implementation & Integration, Support & Maintenance, Consulting & Training) | Software 59.40%; services fastest at 20.95% CAGR |
| PoS type | Fixed PoS, Mobile/MPoS | Mobile 57.20%; fixed 12.41% CAGR |
| Deployment | Public cloud, Private cloud, Hybrid cloud | Public 71.40%; hybrid 23.74% CAGR |
| Organization size | SME, Large enterprise | SME 57.30%; large enterprise 18.87% CAGR |
| End-user industry | Retail & consumer goods, Hospitality & restaurants, Healthcare, Transportation & logistics, Entertainment & media, Others | Retail 38.40%; healthcare 21.37% CAGR |
The implication for vendors is that the SME-led volume base funds the platform, but large-enterprise and healthcare are where services attach and pricing power concentrate. Operators should expect bundled proposals rather than standalone licenses.
North America leads the Cloud Point Of Sale Market with roughly 34.70% of 2025 revenue, while Asia-Pacific is the fastest-growing region at a 19.92% CAGR through 2031. Europe follows on regulatory-driven modernization, with the UK software segment growing near 18%.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.22% |
| Asia-Pacific | 0.29% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | 2025–2026 share | Growth signal |
|---|---|---|
| North America | 35% | Mature; replacement-led, services attach |
| Asia-Pacific | 29% | Fastest at 19.92% CAGR; QR/NFC leapfrog |
| Europe | 22% | Regulatory push; UK near 18% |
| Latin America | 8% | Infrastructure gap limits pace |
| Middle East & Africa | 6% | Cloud-kitchen and UAE retail momentum |
This divergence implies that North American revenue is increasingly recurring and analytics-led, whereas Asia-Pacific growth is still terminal- and payment-rail-led. Vendors cannot run a single go-to-market motion across both.
Cashless-transaction momentum and mobile-first commerce are the strongest growth engines, while data-security gaps and bandwidth reliability in emerging markets are the most material restraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Cashless-transaction momentum | Driver (+5.2% CAGR impact) | High | Only ~10% of in-store payments expected cash-based by 2025; terminals accept new tenders overnight |
| Mobile-first commerce | Driver (+4.7%) | High | MPoS turns any location into a checkout; APAC leapfrogs fixed terminals |
| Omnichannel analytics demand | Driver (+3.8%) | High | 85% of operators feed POS data into engagement tools |
| Regulatory push for e-payments | Driver (+2.9%) | Medium | PSD2-style rules force automatic compliance updates |
| AI-driven inventory optimization | Driver (+2.1%) | Medium | Transaction logs converted into predictive insights |
| Data-security and compliance gaps | Restraint (−2.8%) | High | PCI DSS penalties and data-residency fears slow migration |
| Bandwidth reliability in emerging markets | Restraint (−2.3%) | Medium | Poor connectivity undermines always-on cloud dependence |
| Fragmented cross-border payment rules | Restraint (−1.9%) | Medium | Multinational retailers face inconsistent compliance burdens |
Net position: drivers carry roughly 18.7 percentage points of positive CAGR impact against about 8.6 points of drag, leaving ample headroom for a mid-to-high-teens growth rate. The constraint is not demand—it is trust and infrastructure. Vendors that solve tokenization, zero-trust architecture and offline-mode reliability effectively neutralize the two largest restraints.
The competitive field is medium-concentration, with a top cohort holding well over 70% of value and strong platform-level moats in payments, analytics and distribution.
| Company | Core strength | Moat / differentiation |
|---|---|---|
| Block, Inc. (Square) | SME payments and hardware | Payments ecosystem lock-in and developer network |
| Shopify Inc. | Commerce-integrated POS | Unified online-to-offline data and merchant base |
| Intuit Inc. | SMB accounting-POS bundle | Financial data integration and SMB trust |
| Lightspeed Commerce Inc. | Retail and hospitality verticals | Vertical depth and omnichannel modules |
| Clover Network (Fiserv) | Bank-channel distribution | Acquirer relationships and installed base |
| Oracle Corporation | Enterprise and F&B platforms | Enterprise stack and hospitality references |
| NCR Corporation | Enterprise retail and payments | Global footprint and hardware-service network |
| Toast Inc. | Restaurant-first platform | Restaurant workflow and supplier ecosystem |
Our analysis suggests the durable moats are payment rails and vertical workflow data, not the POS interface itself. Hardware differentiation has collapsed into commodity form factors; differentiation now sits in services attach rates, AI analytics and acquisition-channel partnerships.
Selection hinges on total cost of ownership, not license price. Buyers should model five-year costs including implementation, payment processing spread and migration, because the advertised subscription is rarely the dominant cost line. Payment-fee economics often exceed software spend for high-volume operators.
Data residency, PCI DSS scope and offline-mode reliability are the three procurement risks that most often derail rollouts. Merchants in regulated verticals—healthcare and luxury retail especially—should demand tokenization terms and exit-clause clarity in writing, and should test failure modes under degraded bandwidth before signing.
Switching costs are rising. Integrated loyalty, inventory and accounting modules create data gravity that makes vendor changes expensive in retraining and reconciliation. Operators should insist on contractual data-export rights and API-level portability at the outset, not at renewal.
The balance of evidence favors the mid-range trajectory: a roughly 17% CAGR placing the global Cloud Point Of Sale Market near USD 16 billion by 2031. The strongest counter-argument is the aggressive 24.7% scenario, which assumes AI monetization and adjacent retail IT expansion materialize faster than current indicators suggest. That scenario is plausible but should be treated as an upside case, not a planning base.
Actionable strategy for the next 24 months:
What would change this conclusion: a sustained rise in cyber-insurance premiums and documented data-breach liability could push migration decisions out by 12–18 months, compressing the near-term CAGR toward the low teens. Conversely, regulatory mandates forcing electronic transaction logging would accelerate adoption beyond the base case.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 16.96% from 2020-2034 |
| Segmentation |
|
The global Cloud Point Of Sale Market is estimated at USD 7.32 billion in 2026, up from around USD 6.26 billion in 2025, based on software, services and terminal value across retail, hospitality, healthcare and other end-user industries.
A 16.96% CAGR is the base-case projection for 2026–2031, translating to roughly USD 16.01 billion by the end of the forecast horizon. Higher published figures reflect broader definitions that include adjacent retail IT.
North America leads with about 34.70% of 2025 revenue, supported by mature contactless payment adoption. Asia-Pacific is the fastest-growing region at a 19.92% CAGR, driven by QR and NFC payment leapfrogging.
Software is the leading component segment at 59.40% of 2025 revenue, while mobile PoS leads by terminal type at 57.20%. Retail and consumer goods is the largest end-user industry at 38.40% of value.
Major players include Block (Square), Shopify, Intuit, Lightspeed Commerce, Clover Network (Fiserv), Oracle, NCR, Toast and TouchBistro. The top cohort holds over 70% of value, indicating medium market concentration.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program follows a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with cloud POS software developers, payment-hardware OEMs, managed-service providers, systems integrators and merchant-channel distributors. Respondents were decision-makers holding VP of Product, Head of Payments, Technical Director and Commercial Operations Lead designations, ensuring both technology and buying behavior perspectives are captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & Technology Leadership | 35% |
| Payments & Commercial Operations | 30% |
| Procurement & Sourcing Directors | 20% |
| Security & Compliance Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Cloud POS Software Developers | 40% |
| Payment Terminal OEMs | 25% |
| Managed Service Providers | 20% |
| Systems Integrators & Distributors | 15% |
Secondary benchmarking draws on official multilateral trade statistics (UN Comtrade, USITC DataWeb, Eurostat), corporate annual filings and 10-K submissions, investor presentations, patent databases, and recognized standards and industry bodies including PCI Security Standards Council and relevant national retail associations. No competitor market-research output is used as a validation source.
We run simultaneous top-down allocation (macroeconomic and industry-segment spend) and bottom-up modeling (terminal shipments, seat pricing, services attach and end-use consumption). The two paths are reconciled at the segment level to produce a single calibrated base year and forecast path.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up shipment, license and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |