 Generative AI Chipset Market
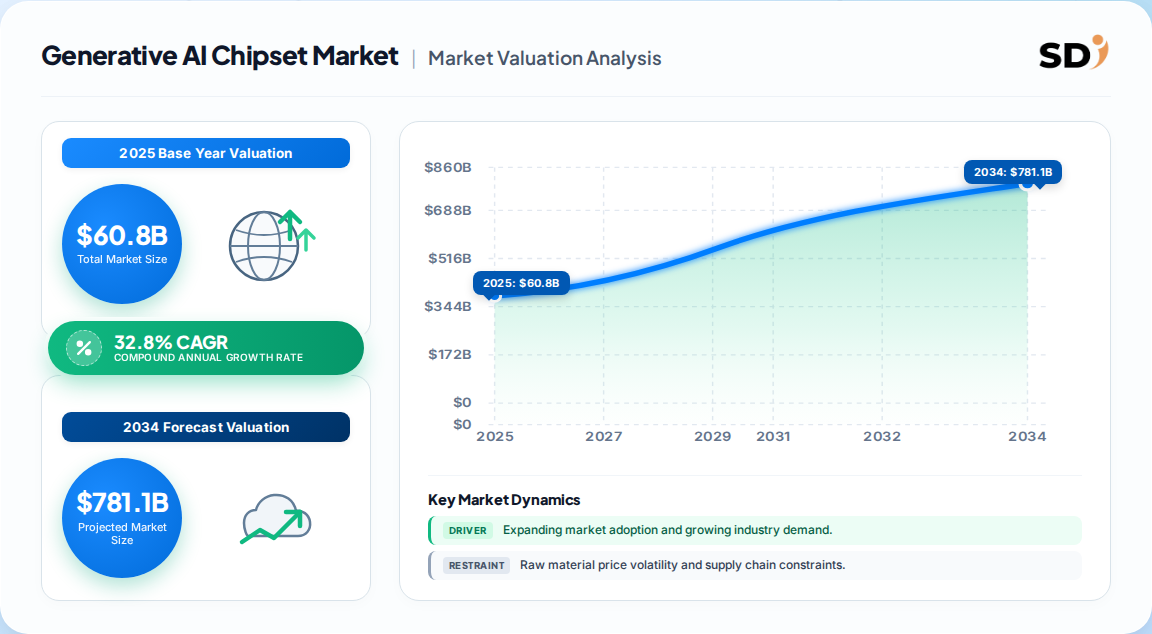
: Size, Growth & Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 266

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Generative AI Chipset Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 60.80 B |
| 2026 | 79.20 B |
| 2027 | 105.3 B |
| 2028 | 139.9 B |
| 2029 | 185.9 B |
| 2030 | 247.0 B |
| 2031 | 328.2 B |

Generative AI chipsets are specialized processors—GPUs, ASICs, FPGAs, and CPUs—designed to accelerate training and inference of generative models including LLMs, image synthesis, and video generation. They deliver the parallel computing capacity required to run complex neural network workloads across cloud data centers, edge devices, and automotive systems.
This report covers the global generative AI chipset market segmented by chipset type (CPU, GPU, FPGA, ASIC, NPU), application (machine learning, deep learning, reinforcement learning, GANs), end use (consumer electronics, automotive, healthcare, BFSI, IT & telecom, manufacturing), and region. This analysis does not cover general-purpose semiconductors unrelated to AI workloads, passive electronic components, or software and algorithmic layers independent of chipset hardware.
The market exhibits significant variation across published estimates, reflecting differences in scope definitions and segment coverage. The table below compares leading published benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 60.8B | 2025 | 2033 | 32.8% | Generative AI chipsets (CPU, GPU, FPGA, ASIC, NPU) | One published estimate (Grand View Research) |
| USD 232.4B | 2025 | 2034 | 24.0% | Broader generative AI chipset incl. systems | Competing analysis (IG Transformation Partners) |
| USD 53.1B | 2025 | 2031 | 32.4% | AI chipsets (training + inference) | Mordor Intelligence |
| USD 56.2B | 2025 | 2034 | 31.2% | AI chipsets, broader segments | Verified Market Research |
Our analysis suggests the USD 60.8B base with 32.8% CAGR to 2033 is the most defensible for the pure generative AI chipset scope. The higher USD 232.4B figure appears to include broader systems and infrastructure, while the USD 53.1B estimate covers AI chipsets broadly rather than generative-specific workloads. The convergence of most estimates around 31–33% CAGR reinforces confidence in the high-growth trajectory. However, buyers must exercise caution: the divergence in base-year sizing by a factor of four underscores the need to validate vendor revenue attribution and scope definitions before committing procurement budgets. Precise sub-segment forecasting requires primary channel checks and design-win tracking.
The market is segmented by chipset type, application, and end use. GPU dominates current revenue, but ASIC and NPU are the fastest-growing categories as custom silicon adoption accelerates.
| Parent Segment | Children |
|---|---|
| By Chipset Type | CPU, GPU, FPGA, ASIC, NPU |
| By Application | Machine Learning, Deep Learning, Reinforcement Learning, Generative Adversarial Networks |
| By End Use | Consumer Electronics, Automotive, Healthcare, BFSI, IT & Telecom, Manufacturing, Retail |
GPUs accounted for 42.2% of 2025 revenue, driven by parallel computing indispensability for training large-scale models. However, ASICs are projected to grow fastest as OpenAI-Broadcom, Google TPU, and Amazon Trainium programs scale. Deep learning led applications at 40.5% share, while automotive emerged as the largest end-use vertical at 39.1%, reflecting autonomous driving and ADAS investments. The implication for buyers: single-source GPU strategies carry concentration risk; dual-sourcing with ASIC alternatives is becoming a procurement imperative.
North America dominates the global generative AI chipset market with 41.7% revenue share in 2025, underpinned by hyperscaler concentration, leading AI labs, and CHIPS Act funding. Asia Pacific is the fastest-growing region, driven by semiconductor manufacturing capacity and government AI infrastructure programs.
| Region | Market Share (%) |
|---|---|
| North America | 0.42% |
| Europe | 0.19% |
| Asia-Pacific | 0.28% |
| Latin America | 0.05% |
| Middle East & Africa | 0.06% |
| Parent Region | Key Countries |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy |
| Asia Pacific | China, Japan, India, South Korea |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
North America's leadership is reinforced by NVIDIA, AMD, and Google headquarters, alongside massive data center investment. The U.S. CHIPS and Science Act's USD 52.7B funding supports domestic fabrication and packaging. Asia Pacific's growth is propelled by TSMC's advanced node dominance, South Korea's HBM leadership, and China's USD 143B AI self-reliance program. Europe is mobilizing approximately USD 209B through InvestAI for AI gigafactories. The divergence implies that supply-chain localization strategies must account for regional capability asymmetries: North America leads in design and cloud, while Asia Pacific controls fabrication and memory.
Demand for generative AI compute, enterprise adoption, and government semiconductor programs are the primary growth drivers, while supply constraints at advanced nodes and high development costs represent the principal restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Exploding training-compute demand | Driver | High | LLM compute needs increase 10x every 18 months |
| Growing enterprise adoption | Driver | High | GenAI moving from pilots to production |
| Rising inference computing | Driver | High | AI agents multiply processing steps per request |
| Cloud/data center expansion | Driver | High | Hyperscale capacity additions |
| Government semiconductor funding | Driver | Medium | CHIPS Act USD 52.7B; China USD 143B |
| High development/manufacturing costs | Restraint | High | Advanced node R&D and fabrication costs |
| Limited advanced foundry capacity | Restraint | High | Sub-3nm supply constraints |
| Export controls | Restraint | Medium | Geopolitical trade restrictions |
The balance of evidence favors sustained high growth. Training compute demand growing tenfold every 18 months underpins multi-year visibility for accelerator orders. NVIDIA's data-center revenue reaching USD 35.6B in Q4 2025 illustrates the scale of hyperscale procurement. However, supply-side constraints below 3nm and CoWoS packaging capacity create near-term bottlenecks. Our analysis suggests these constraints will ease by 2027–2028 as new fabs and packaging facilities come online, but buyers should secure long-term supply agreements now to avoid allocation risk during the peak demand window.
NVIDIA leads the generative AI chipset market with dominant GPU share, followed by AMD, Broadcom, and hyperscaler custom silicon programs. The competitive landscape is intensifying as cloud providers design proprietary accelerators.
| Company | Key Products | Competitive Position |
|---|---|---|
| NVIDIA | H100, B200, Blackwell | Dominant GPU leader; full-stack CUDA ecosystem |
| AMD | MI300X, MI350 | Strong GPU challenger; open ecosystem |
| Broadcom | Custom ASICs (OpenAI XPU) | Leading custom silicon partner |
| TPU v5/v6 | Proprietary hyperscaler accelerator | |
| Intel | Gaudi 3, Xeon | CPU + AI accelerator portfolio |
| Amazon | Trainium, Inferentia | Custom cloud inference silicon |
NVIDIA's moat rests on CUDA software lock-in and full-stack system integration, not just chip performance. However, this lock-in is being challenged: OpenAI's partnership with Broadcom for a custom "XPU" ASIC and Google's TPU scaling signal a structural shift toward heterogeneous architectures. Our analysis suggests the competitive moat is widening at the system level (rack-scale integration, networking, software) while narrowing at the chip level. Vendors that cannot offer integrated rack-scale solutions risk commoditization. Buyers should evaluate total cost of ownership including software migration costs, not just per-chip pricing.
Procurement decisions in this market are mission-critical and carry multi-year lock-in implications. Buyers must prioritize total cost of ownership, supply-chain resilience, and software ecosystem compatibility over raw performance benchmarks alone. Switching costs between GPU and ASIC architectures are substantial—CUDA-trained workloads require significant re-engineering for alternative platforms. Regulatory compliance is increasingly relevant: export controls restrict advanced chip shipments to certain regions, and data sovereignty requirements are driving sovereign AI infrastructure investments. Operators should demand contractual guarantees on supply allocation, performance-per-watt commitments, and roadmap transparency. The shift toward inference workloads means procurement teams must model cost-per-token economics, not just training throughput. Organizations that fail to diversify their accelerator supply chain face concentration risk as demand outpaces fab capacity through 2027.
The balance of evidence favors sustained, high-growth expansion of the generative AI chipset market through 2033, with a 32.8% CAGR representing the most defensible central case. The strongest counter-argument is that the market could face a correction if enterprise ROI on generative AI disappoints, triggering a pause in hyperscale capex. However, current order backlogs and long-term procurement agreements provide multi-year visibility that mitigates near-term demand risk.
Our analysis identifies three structural shifts that will define competitive outcomes: first, inference will surpass training as the dominant workload by 2028, rewarding vendors with cost-efficient, low-latency architectures; second, custom ASIC adoption by hyperscalers will erode merchant GPU share, though NVIDIA's system-level moat will preserve its leadership; third, sovereign AI programs will create regional demand pockets that favor vendors with local manufacturing partnerships.
Actionable Strategy:
We would change our conclusion if enterprise generative AI adoption stalls materially (e.g., if Fortune 500 deployment rates plateau below 30%) or if advanced packaging capacity expands faster than expected, compressing lead times and triggering pricing pressure earlier than 2028.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 32.8% from 2020-2034 |
| Segmentation |
|
The market was valued at USD 60.8 Billion in 2025 and is estimated at USD 79.2 Billion in 2026, based on the most defensible published estimate for purely generative AI chipset scope.
The market is projected to grow at a 32.8% CAGR from 2026 to 2033, reaching USD 578.4 Billion by the end of the forecast period, driven by training and inference compute demand.
North America held the largest revenue share at 41.7% in 2025, driven by hyperscaler concentration and leading AI labs, while Asia Pacific is the fastest-growing region through 2033.
The market is segmented by chipset type (GPU, ASIC, FPGA, CPU, NPU), application (deep learning, machine learning, GANs, reinforcement learning), and end use (consumer electronics, automotive, healthcare, BFSI, IT & telecom).
NVIDIA leads with dominant GPU share, followed by AMD, Broadcom, Google, Intel, and Amazon, with hyperscaler custom silicon programs gaining momentum and eroding merchant GPU share.
Key drivers include exploding training-compute demand, enterprise generative AI adoption, rising inference workloads, cloud data center expansion, and government semiconductor funding programs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, ensuring that market intelligence is grounded in direct industry validation rather than reliance on published estimates. We conducted in-depth interviews with key stakeholders across the generative AI chipset value chain, including semiconductor foundries and fab operators, fabless chip designers, advanced packaging specialists, hyperscale data center operators, and enterprise AI infrastructure buyers. Decision-maker designations interviewed include VP of Sourcing and Procurement, Heads of AI Infrastructure, Technical Directors of Semiconductor Engineering, and Commercial Operations Leads. These interviews provided critical validation of market sizing, procurement timelines, and supply-chain dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 35% |
| Heads of AI Infrastructure | 30% |
| Technical Directors of Engineering | 25% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Semiconductor Foundries & Fabricators | 40% |
| Fabless Chip Designers | 30% |
| Hyperscale Data Center Operators | 20% |
| Advanced Packaging Specialists | 10% |
We benchmark market estimates against official multilateral trade databases including UN Comtrade (HS 8542 integrated circuits trade flows), WTO trade statistics, US International Trade Commission data, and Eurostat semiconductor trade records. Corporate annual filings (10-K, SEC filings, annual investor presentations) from NVIDIA, AMD, Broadcom, Intel, and TSMC provided revenue attribution and capacity data. Patent databases and technical standards from IEEE and SEMI informed technology roadmap validation.
Our demand modeling applies simultaneous top-down and bottom-up triangulation. Top-down modeling allocates macroeconomic semiconductor market forecasts by generative AI workload share. Bottom-up modeling builds from manufacturer capacity data, wafer pricing, advanced packaging throughput, and end-use consumption modeling across hyperscale, enterprise, and edge deployments. Divergences between approaches are reconciled through primary interview validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |