 Automated Media Preparation Systems Market
 2026 Outlook
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 277

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Automated Media Preparation Systems Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 1.000 B |
| 2026 | 1.100 B |
| 2027 | 1.210 B |
| 2028 | 1.340 B |
| 2029 | 1.480 B |
| 2030 | 1.630 B |
| 2031 | 1.800 B |

The Automated Media Preparation Systems Market covers instruments that automate mixing, sterilization, cooling, and dispensing of culture media into plates, tubes, and bottles. These platforms replace manual workflows in microbiology, cell culture, and drug discovery labs, delivering reproducible formulation, contamination control, and audit-ready documentation for pharmaceutical, clinical, and academic facilities.
This analysis covers automated culture media preparation systems and automated liquid handling systems used in cell culture, microbiology, and drug discovery across pharmaceutical, biotechnology, clinical laboratory, and academic end uses. It spans North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, with revenue forecasts to 2033.
This analysis does not cover general-purpose robotic liquid handlers sold outside media workflows, benchtop sterilizers and autoclaves as standalone categories, ready-to-use dehydrated media and consumables, cell culture media formulations themselves, or upstream bioreactor and fermentation equipment.
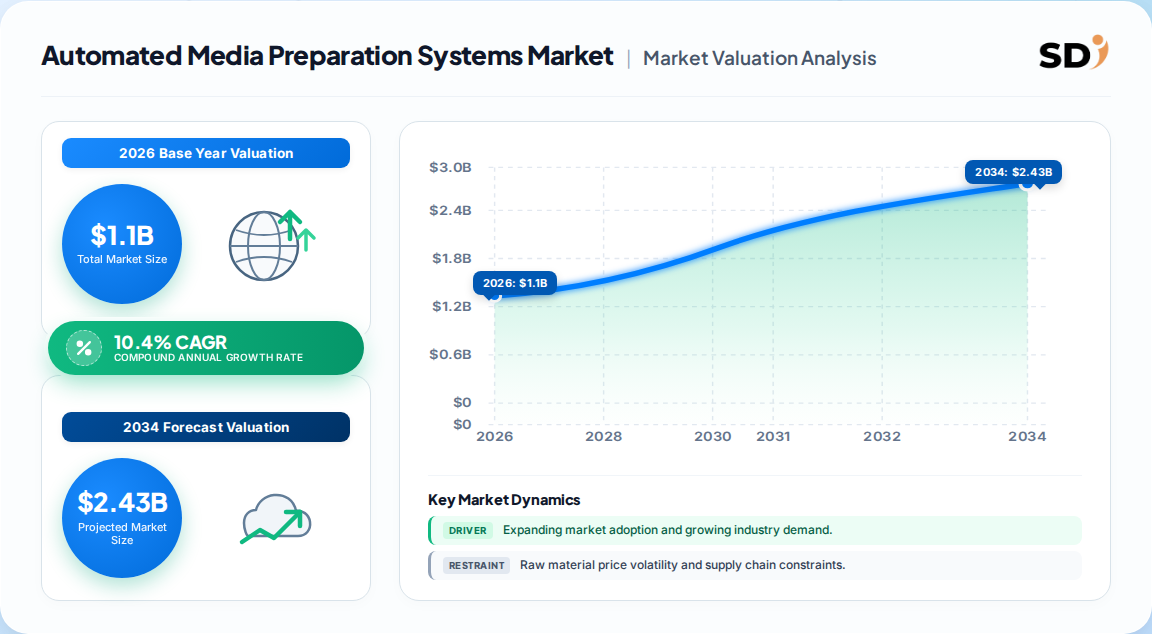
The market is most defensibly sized at USD 1.1 Billion in 2026, converging on USD 2.3 Billion by 2033 at a ~10.4% CAGR — the two tier-1 estimates align closely, while wider third-party projections inflate the base year or extend the horizon.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.0B → USD 2.3B | 2025 | 2033 | 10.4% | Culture media prep + liquid handling, four end uses | One published estimate (tier-1) |
| USD 1.08B → USD 2.92B | 2025 | 2035 | 10.45% | Same product scope, extended horizon | A competing analysis |
| USD 1.0B → USD 2.27B | 2023 | 2033 | 10.35% | Narrower end-use set | A competing analysis |
| USD 1.0B → USD 2.65B | 2023 | 2033 | 10.24% | Broader vendor list, mixed definitions | A competing analysis |
Our analysis suggests the USD 2.3 Billion / 2033 trajectory is the most defensible: the CAGR spread across sources is only ~0.2 percentage points, so the divergence is almost entirely base-year definition and horizon length rather than genuine demand disagreement. The USD 2.92 Billion figure reflects a 2035 endpoint, not a faster market.
Segmentation follows three non-geographic axes: product type, application, and end use. Product is the decisive axis for procurement, because culture media systems and liquid handlers solve different workflow problems and carry very different validation burdens.
| Axis | Leading segment | Share (2025) | Fastest-growing |
|---|---|---|---|
| Product | Automated culture media preparation systems | ~60% | Culture media systems |
| Application | Cell culture | ~45% | Cell culture |
| End use | Pharmaceutical & biotechnology companies | ~42–50% | Pharma & biotech |
North America leads with roughly 42–43% revenue share, reflecting concentrated biopharma R&D, mature clinical diagnostics infrastructure, and early automation adoption. Asia Pacific is the fastest-growing region, while Europe holds a stable second position near 25%.
| Region | Market Share (%) |
|---|---|
| North America | 0.42% |
| Europe | 0.25% |
| Asia-Pacific | 0.21% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
| Region | 2025 share | Growth posture | Primary demand driver |
|---|---|---|---|
| North America | ~42–43% | Mature, steady | Biopharma R&D density, FDA-driven traceability |
| Europe | ~25% | Moderate | Pharma QC standardization, EU GMP audits |
| Asia Pacific | ~20–21% | Fastest | New lab build-out, CDMO expansion |
| Latin America | ~7% | Emerging | Diagnostics modernization, local manufacturing |
| Middle East & Africa | ~5% | Nascent | Public health lab extension |
Nested geography covered in this report:
This divergence implies a two-speed market: North America supplies replacement and upgrade revenue, while Asia Pacific supplies incremental volume. Vendors optimizing only for Western replacement cycles will under-serve the faster-growing greenfield segment.
Growth is driven by laboratory efficiency mandates, biopharma R&D expansion, and regulatory pressure for traceable, contamination-free media preparation. Restraints are concentrated in capital cost and workflow-integration friction rather than in demand saturation.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Laboratory efficiency & labor shortage | Driver | High | Single-platform batch processing cuts prep time and manual effort |
| Biopharma and life-science R&D growth | Driver | High | Biologics, vaccines, and cell/gene therapies need sterile media at scale |
| Regulatory traceability requirements | Driver | High | Audit-ready documentation favors automated over manual records |
| Digital integration (LIMS, IoT, AI alerts) | Driver | Moderate–High | Reduces preparation failures and administrative burden |
| High upfront capital outlay | Restraint | High | Slows adoption in smaller and academic labs |
| Workflow integration and staff retraining | Restraint | Moderate | Limits uptake where legacy processes are entrenched |
On balance, drivers outnumber and outweigh restraints, but the balance is uneven. Our analysis suggests integration friction, not price, is the binding constraint for mid-sized labs — meaning vendors that bundle validation services and workflow migration convert better than those competing on hardware price alone.
The category is moderately concentrated, with large life-science toolmakers holding integrated portfolios and smaller specialists competing on throughput and modularity. Differentiation increasingly rests on software and validation support rather than hardware specification.
| Vendor | Portfolio position | Typical competitive strength |
|---|---|---|
| Thermo Fisher Scientific | Broad integrated platforms | Scale, global service network, consumables pull-through |
| Merck KGaA | Automated media prep and dispensing | ReadyStream on-demand production; strong pharma relationships |
| Sartorius AG | Bioprocess-adjacent automation | Workflow integration with upstream bioprocessing |
| bioMérieux | Microbiology-focused systems | Clinical and industrial QC credibility |
| Lonza | Cell culture workflow solutions | Cell-culture application depth |
| Danaher | Instrument and software ecosystem | LIMS and data connectivity breadth |
| INTEGRA Biosciences | Liquid handling specialists | Precision dispensing, modular pricing |
Competitive moats are built on validation documentation and installed-base service contracts, not on hardware alone. This implies switching costs are high once a platform is embedded in a validated QC workflow — a structural advantage for incumbents and a real barrier for new entrants.
Selection should be anchored to four criteria: batch-to-batch reproducibility, sterilization and contamination control, data traceability compatible with existing LIMS, and service response time. Buyers who prioritize purchase price over validation support frequently absorb higher lifetime cost through revalidation and downtime.
Procurement risk concentrates in two areas. First, integration: systems that cannot export audit-ready records force parallel manual documentation, eroding the efficiency case. Second, scalability: fixed-format dispensers purchased for current volume often require full replacement rather than expansion.
Switching costs are material. Once a platform is embedded in a validated workflow, changing vendors triggers revalidation, retraining, and often consumable re-qualification. Operators should therefore negotiate service-level agreements and consumable pricing at the point of initial purchase, not after lock-in.
Regulatory compliance is non-negotiable in pharmaceutical and clinical settings. Systems should support traceable, consistent processes that withstand audit; this requirement alone eliminates a meaningful share of low-cost alternatives from serious consideration.
The balance of evidence favors a market that will grow reliably rather than explosively. A ~10.4% CAGR across four independent estimates, with only ~0.2 points of spread, is unusually tight for a category of this size — the disagreement is about where the base year sits, not whether demand exists. Investors should treat the 2033 endpoint near USD 2.3 Billion as the planning anchor and discount wider projections as horizon artifacts.
The strongest counter-argument is that capital-intensity plus integration friction could suppress adoption in precisely the mid-sized lab segment that represents the largest untapped pool. That risk is real, but it argues for vendor strategy rather than market contraction: the constraint is deployment, not demand. Regulatory traceability requirements also create a floor under replacement demand that price competition cannot easily erode.
Actionable strategy:
What would change this conclusion: a sustained stall in biopharma R&D spending, or evidence that mid-sized labs are abandoning automation programs mid-deployment, would signal genuine demand erosion rather than deployment friction. While this overview establishes the sizing and strategic frame, precise sub-segment forecasting and country-level vendor share require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.4% from 2020-2034 |
| Segmentation |
|
The global market is estimated at USD 1.1 Billion in 2026, building on USD 1.0 Billion in 2025. It is projected to reach USD 2.3 Billion by 2033, representing a 10.4% CAGR across the forecast period.
North America leads with roughly 42–43% revenue share in 2025, driven by concentrated biopharma R&D and mature clinical diagnostics infrastructure. Asia Pacific is the fastest-growing region across the 2026–2033 forecast horizon.
Cell culture is both the largest and fastest-growing application, holding roughly 45% share in 2025. Growth is driven by biologics development, vaccine production, and regenerative medicine research requiring large volumes of sterile, reproducible media.
Key vendors include Thermo Fisher Scientific, Merck KGaA, Sartorius AG, bioMérieux, Lonza, Danaher, and INTEGRA Biosciences. Competition increasingly rests on software integration, validation support, and service networks rather than hardware specification alone.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, spanning instrument component suppliers, specialized automated media preparation system producers, contract manufacturing and integration partners, and global laboratory equipment distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads across pharmaceutical, biotechnology, and clinical laboratory settings.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Quality & Regulatory Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Instrument & Component Producers | 40% |
| System Integrators & OEMs | 30% |
| Distributors & Service Partners | 30% |
Secondary validation draws on official multilateral trade and standards databases including UN Comtrade, WTO statistics, USITC DataWeb, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies and industry associations. No competitor market research publications are used as validation inputs.
Sizing applies simultaneous Top-Down and Bottom-Up triangulation. Top-down allocation derives from macroeconomic life-science R&D spend and laboratory automation budgets by region and end use. Bottom-up modeling builds from manufacturer capacity, instrument pricing bands, installed-base replacement cycles, and end-use consumption of culture media volumes.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |