 China Contrast Media Injectors Market
 2025: Size, CAGR & Outlook
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 197

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 China Contrast Media Injectors Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2023 | 78.00 M |
| 2024 | 86.00 M |
| 2025 | 94.00 M |
| 2026 | 103.0 M |
| 2027 | 113.0 M |
| 2028 | 124.0 M |
| 2029 | 136.0 M |

The China contrast media injectors market covers powered devices and associated disposables that deliver contrast agents at controlled flow rates during CT, MRI, and angiography procedures. It spans injector systems, syringes, tubing, and cassettes sold to hospitals and diagnostic imaging centers across mainland China. This analysis does not cover the contrast agents (iodinated or gadolinium media) themselves, nor standalone imaging scanners.
This report addresses mainline CT, MRI, and angiographic contrast delivery hardware — single-head, dual-head, and emerging syringeless systems — plus their consumable components and the end-use channels (hospitals, diagnostic centers, and ambulatory settings) that procure them in China.
Excluded from scope: contrast pharmaceuticals, radiotracers, ultrasound contrast agents, standalone scanner capital equipment, and veterinary imaging. Software-only dose-tracking platforms are referenced only where they attach to injector hardware procurement.
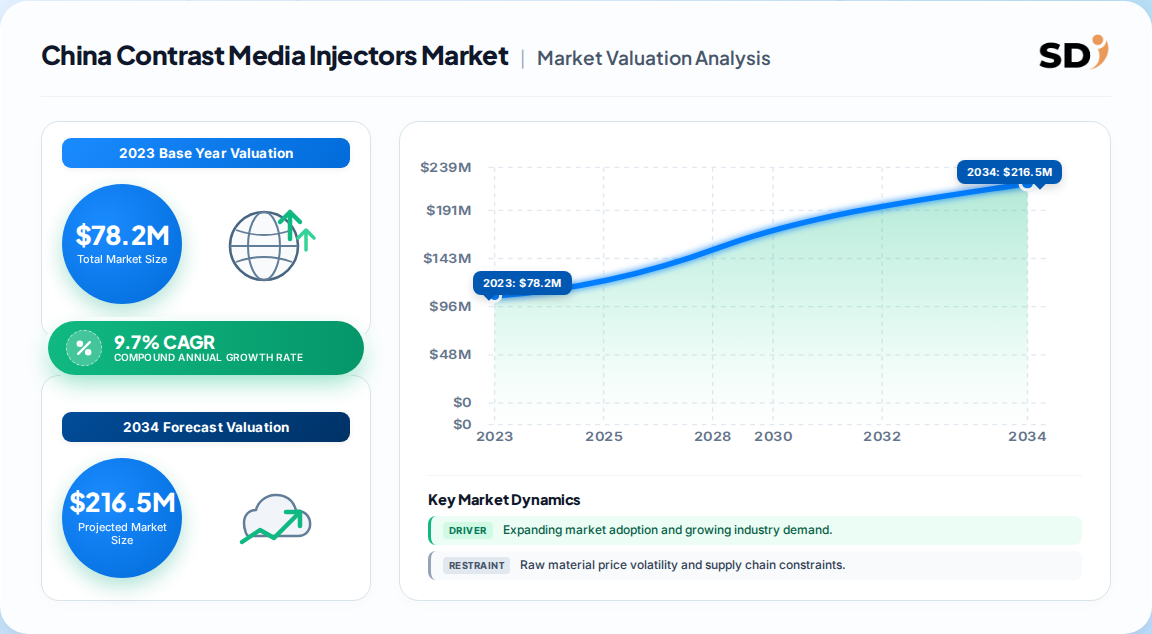
Estimates converge tightly on a USD 78.2 million 2023 base for China, but the forward CAGR differs by source depending on whether syringeless systems and AI-dose software are counted as hardware or consumables revenue.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 78.2 Million | 2023 | 2030 | 9.7% | Systems + consumables, China only | One published estimate |
| Global share ~3.2% of USD 2.45 Billion | 2025 | 2034 | ~9.4% APAC | Global injector market, China as sub-share | A competing analysis |
| Implied Asia-Pacific 9.4–9.5% | 2025 | 2031 | 9.4–9.5% | APAC aggregate growth proxy | A competing analysis |
Our analysis suggests the 9.7% figure is the most defensible single anchor: it is China-specific, spans both product families, and aligns with the 9.4–9.5% APAC CAGR cited in global builds. The higher global CAGRs (near 10%) reflect a heavier weighting toward high-price North American and European replacement cycles; China's volume-driven tier-2 expansion pulls the blended rate slightly down while lifting unit growth.
Two second-order signals matter. First, China's GDP-level healthcare spending — approximately USD 1 trillion annually — is the ceiling constraint, not demand. Second, NMPA's streamlined approval pathway for innovative devices is shortening the lag between global launch and China availability, compressing the window in which legacy single-head systems can be sold at premium pricing.
The segmentation follows product, injector type, application, and end use, each with distinct procurement dynamics and margin structures.
| Parent Segment | Children | 2023 Share / Growth Signal |
|---|---|---|
| By Product | Injector Systems, Consumables (syringes, tubing, cassettes) | Systems 60.8%; consumables 10.6% CAGR |
| By Injector Type | Single-Head, Dual-Head, Syringeless | Single-head 43.8%; syringeless fastest-growing |
| By Application | Radiology, Interventional Cardiology, Interventional Radiology | Radiology dominant; cardiology accelerating |
| By End Use | Hospitals, Diagnostic Centers, Ambulatory Surgery Centers | Hospitals lead; diagnostic centers fastest |
Three structural observations follow. First, the systems/consumables split is misleading if read as a profit split — systems carry higher ticket value but lower recurring margin, so the 60.8% systems share overstates its strategic weight. Second, the single-head dominance (43.8%) is an installed-base artifact, not a forward-looking signal; new cath-lab and stroke-unit builds favor dual-head and syringeless platforms for workflow precision. Third, application mix matters more in China than in Western markets because radiology's dominance is amplified by a national CT-installation boom.
East China leads, anchored by Shanghai, Jiangsu, and Zhejiang, where high-slice CT and 3T MRI density, top-tier hospital concentration, and diagnostic-center investment are highest. North and South China follow, with central and western provinces representing the next volume-growth frontier.
| Parent | Children |
|---|---|
| East China | Shanghai, Jiangsu, Zhejiang, Anhui, Fujian, Jiangxi, Shandong |
| North China | Beijing, Tianjin, Hebei, Shanxi, Inner Mongolia |
| South China | Guangdong, Guangxi, Hainan |
| Central China | Hubei, Hunan, Henan |
| Southwest China | Sichuan, Chongqing, Yunnan, Guizhou, Tibet |
| Northwest China | Shaanxi, Gansu, Qinghai, Ningxia, Xinjiang |
| Northeast China | Liaoning, Jilin, Heilongjiang |
Our analysis suggests the East-China concentration (~34% of national demand) is a double-edged sword. It offers vendors a dense, high-margin beachhead but exposes them to competitive intensity and tender-price compression. The real growth story — and the harder operational test — is tier-2 and tier-3 city hospital expansion in Central and Southwest China, where scanner density sits below two units per 100,000 residents and price sensitivity is acute. Vendors that treat western China as a discounted afterthought will cede the volume layer of the market to local challengers.
China's contrast injector demand is driven by a chronic-disease burden and a scanner-installation boom, constrained by capital budgets and NMPA compliance friction.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Chronic disease burden (NCDs ~74% of deaths) | Driver | High | Rising CT/MRI contrast-enhanced procedure volumes |
| Geriatric shift (28% aged 60+ by 2040) | Driver | High | Structural, multi-decade demand expansion |
| High-slice CT / 3T MRI installation in tier-2 cities | Driver | High | Pull-through injector attach rate per scanner |
| Healthcare spending ~USD 1 trillion | Driver | Medium-High | Capital availability for device procurement |
| NMPA regulatory complexity | Restraint | High | Approval timelines, local clinical evidence requirements |
| High equipment and consumable costs | Restraint | Medium | Budget limits at smaller hospitals |
| AI dose-reduction protocols | Both | Medium | Cuts iodine volume but expands procedure throughput |
The balance of evidence favors demand-side drivers by a wide margin: the constraint on China's market is not patient need or clinical appetite, but procurement timing and regulatory throughput. This divergence implies that vendors with an NMPA-registered local manufacturing footprint hold a structural timing advantage, because they can bid into hospital tenders during windows that import-only competitors miss. The AI dose-reduction paradox is worth flagging: tools that cut per-procedure contrast volume compress consumable revenue per scan, but they also reduce repeat-scan rates and expand the addressable procedure base — net positive for injector-system demand, mildly negative for disposables pricing.
The China market is contested by global imaging majors, specialist injector firms, and emerging domestic manufacturers, each with a distinct moat.
| Vendor Archetype | Examples | Primary Moat | China Positioning |
|---|---|---|---|
| Global imaging major | Siemens Healthineers, GE HealthCare, Bayer | Scanner–injector integration, brand trust | Strong in tier-1 hospitals; bundled scanner deals |
| Contrast & injector specialist | Guerbet, Bracco, Ulrich Medical | Contrast-agent adjacency, workflow software | Growing via automated and dual-head platforms |
| Domestic injector specialist | Sino MDT (SinoPower-D), local OEMs | Price, local service, tender agility | Strong in tier-2/3, provincial tenders |
| Software-led challenger | Dose-tracking/AI protocol vendors | HL7 integration, dose analytics | Attach-rate play; dependent on hardware partners |
Differentiation is shifting from hardware specifications to ecosystem lock-in — scanner integration, dose-tracking software, and consumable supply contracts. Our analysis suggests domestic specialists like Sino MDT have already neutralized the price gap on dual-head CT injectors, which means global vendors must defend on service depth, uptime SLAs, and multi-modality compatibility rather than unit price. The strongest moat remains bidirectional HL7 connectivity that feeds dose, flow, and pressure data into hospital EHR systems — a software depth that smaller manufacturers struggle to replicate.
Buyers should weigh five mission-critical criteria: NMPA registration status and local clinical evidence; multi-modality compatibility (CT, MRI, angiography); consumable supply-chain reliability and per-procedure cost; HL7/EHR integration depth; and service-network coverage in the hospital's province. Procurement risk concentrates in tender cycles and post-warranty service contracts, where consumable lock-in can raise five-year total cost of ownership well above the capital price.
Switching costs are non-trivial. Once a hospital standardizes on a vendor's syringe or cassette format, moving to a competitor requires retraining radiology staff and revalidating protocols — often a 6–12 month cycle. Regulatory compliance is the hard gate: NMPA enforces rigorous safety and efficacy standards, and recent updates have streamlined approvals for innovative devices while raising the bar for documentation. Operators should model consumable cost inflation and service-contract renewal as the dominant lifetime-cost drivers, not the initial equipment quote.
The balance of evidence favors a consumables-first, locally-registered strategy over a systems-led land-grab. China's injector market is not capital-constrained at the national level — healthcare spending near USD 1 trillion and a scanner-installation boom ensure demand — but it is timing-constrained by NMPA throughput and margin-constrained by tender price competition in tier-2 cities. The winners will be vendors that pair a compliant local footprint with a recurring-revenue consumable model.
The strongest counter-argument is that AI dose-reduction protocols could erode consumable revenue faster than procedure growth offsets it. That is a real risk, but it is a medium-term one: dose-reduction software is still concentrated in academic centers, and community-hospital adoption requires clinical-equivalence validation that lags by years. In the interim, the installed-base refresh cycle for single-head systems remains the largest identifiable revenue pool.
Evidence that would change this conclusion: a sharp NMPA acceleration that floods the market with import approvals (compressing domestic price advantage), or a national reimbursement policy that unbundles injector consumables from procedure tariffs.
| Region | Market Share (%) |
|---|---|
| East China | 0.34% |
| North China | 0.18% |
| South China | 0.17% |
| Central China | 0.13% |
| Southwest China | 0.11% |
| Northwest China | 0.04% |
| Northeast China | 0.03% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.7% from 2020-2034 |
| Segmentation |
|
The China contrast media injectors market was estimated at USD 78.2 million in 2023. One published estimate projects it to grow at a 9.7% CAGR through 2030, implying a market of roughly USD 148 million by the end of the forecast period.
The most-cited China-specific CAGR is 9.7% for 2024–2030. This sits close to the 9.4–9.5% Asia-Pacific growth figures cited in global analyses, which lends the China estimate credibility and suggests volume-driven tier-2 hospital expansion is the primary growth engine.
Injector systems held 60.8% of 2023 revenue, while single-head injectors represented 43.8% of the type mix. However, consumables are growing fastest at 10.6% CAGR, and dual-head platforms are gaining share in new cath-lab and interventional builds.
Global imaging majors such as Siemens Healthineers, GE HealthCare, Bayer, Guerbet, and Bracco compete with specialist firms like Ulrich Medical and domestic manufacturers such as Sino MDT. Domestic specialists compete strongly on price and provincial tender agility.
Demand is driven by a heavy chronic-disease burden (non-communicable diseases caused roughly 74% of deaths in 2023), an aging population projected at 28% aged 60+ by 2040, and rapid high-slice CT and 3T MRI installation in tier-2 cities.
NMPA regulatory complexity, approval timelines, and high equipment and consumable costs restrain growth. Budget-constrained smaller hospitals may delay purchases, and tender price competition in tier-2 and tier-3 cities compresses margins for all but the most locally entrenched vendors.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the contrast-delivery value chain, including raw material and component suppliers, specialized injector-system producers, contract manufacturing and assembly partners, and national and provincial distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D and Product Engineering, Technical Directors, and Commercial Operations Leads responsible for hospital tender strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Hospital Procurement & Sourcing Leads | 35% |
| Radiology & Clinical Directors | 30% |
| Regulatory Affairs Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Injector System Manufacturers | 40% |
| Consumable Component Suppliers | 30% |
| Distributors & Hospital Channel Partners | 20% |
| Software & Integration Providers | 10% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized technical standards bodies including ISO and NMPA regulatory publications. No third-party market-research publisher data is cited as primary evidence.
Market sizing is triangulated through simultaneous top-down allocation (macroeconomic healthcare spending, diagnostic imaging procedure volumes, and segment-level device allocation) and bottom-up modeling (manufacturer capacity, product pricing, and end-use consumption by hospital tier). Divergences between the two approaches are reconciled through primary interview validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Provincial share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |