 AI Supercomputing Platforms Market
: 2026 Growth & Forecast
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 259

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 AI Supercomputing Platforms Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 10.90 B |
| 2025 | 12.25 B |
| 2026 | 13.81 B |
| 2027 | 15.56 B |
| 2028 | 17.54 B |
| 2029 | 19.77 B |
| 2030 | 22.28 B |

AI supercomputing platforms are integrated hardware-plus-software systems — accelerated compute, high-speed interconnects, and orchestration stacks — purpose-built to train and serve large AI models at scale. The market covers processors, accelerators, interconnects, storage, cooling, and cloud-based HPC services sold to governments, research institutions, and enterprises.
This report covers the global market for AI-optimized supercomputing platforms across components (processors, accelerators, interconnects, storage, software), deployment models (on-premises, cloud, hybrid), processing scale (petascale through exascale), and end-users (government, academia, healthcare, manufacturing, BFSI). This analysis does not cover standalone consumer GPUs, edge AI devices, quantum computing hardware, or general-purpose enterprise data-center servers below petascale class.
The AI supercomputing segment sits inside a broader supercomputer market of roughly 12.25 Billion (2025), and published forecasts diverge sharply because each analyst defines the boundary differently. The reconciliation below is the analytical core of this overview.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 1.91 Bn → 14.22 Bn | 2025 | 2035 | 22.29% | Narrow "AI supercomputer" hardware-only category | Aggregated industry content (AI supercomputer report) |
| 7.85 Bn → 45.38 Bn | 2025 | 2035 | 19.18% | "AI in supercomputer" — hardware + software + services attached to AI workloads | Aggregated industry content (AI-in-supercomputer report) |
| 12.42 Bn → 21.11 Bn | 2026 | 2031 | 11.18% | Total supercomputer market including non-AI HPC | Aggregated industry content (supercomputer report) |
| 13.29 Bn → 33.48 Bn | 2026 | 2035 | 10.82% | Total supercomputer market, all workload types | Published market benchmark |
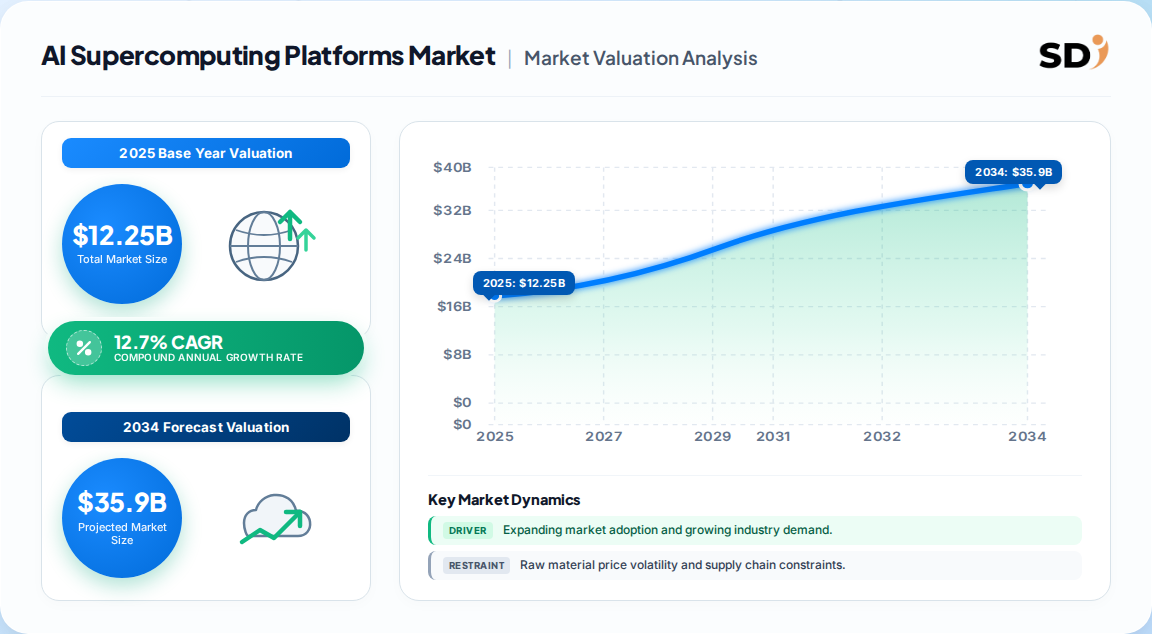
The 22.29% figure is directionally correct for pure AI supercomputer hardware but is too narrow to represent the platforms market; the 10.82–11.18% figures are too broad because they dilute AI growth with legacy HPC. Our analysis suggests a blended 12.7% CAGR for the AI supercomputing platforms market is the most defensible base case — it captures AI acceleration while acknowledging that a meaningful share of deployed supercomputer capacity still runs non-AI workloads. Buyers must validate which definition underpins any vendor TCO comparison, because a hardware-only quote understates the software and integration load by 30–40%.
Segmentation follows four axes — component, deployment, processing scale, and end-user — with cloud and accelerators the fastest-moving axes.
| Parent Segment | Children | 2025 Share Signal | Growth Signal |
|---|---|---|---|
| By Component | Processors/Compute, Accelerators (GPU/ASIC), Interconnects, Storage, Software & Services | Compute ~38–44% share | Interconnects fastest (CAGR) |
| By Deployment | On-Premises, Cloud, Hybrid | Cloud ~61% share | Cloud fastest (19.98% CAGR) |
| By Processing Scale | Petascale, Pre-Exascale, Exascale | Exascale major share | Exascale 26.18% CAGR |
| By End-User | Government & Public Sector, Academic & Research, Healthcare & Life Sciences, Manufacturing, BFSI, Defense | Government ~29–38% | Healthcare 15.44% CAGR |
| By Application | Deep Learning, NLP, Simulation & Modeling, Image Recognition, Climate & Biomedical | NLP largest | Deep Learning fastest |
The cloud-dominance signal (~61% share) is the most consequential structural fact in this market: it means the procurement battleground has shifted from system integrators to hyperscaler and neocloud platform operators. Components remain the value-capture center (accelerators alone drive the majority of BOM cost), but the decision center has moved to cloud platform architects. That split is precisely where vendor margins are being won and lost.
North America leads with roughly 37% of global revenue in 2025, driven by U.S. Department of Energy programs, hyperscaler AI infrastructure buildouts, and the deepest concentration of accelerator supply. Asia-Pacific is the fastest-growing region at a 12.55% CAGR, powered by national exascale programs in China, Japan, and India.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.24% |
| Asia-Pacific | 0.28% |
| Latin America | 0.05% |
| Middle East & Africa | 0.06% |
| Parent Region | Sub-Regions / Countries |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Netherlands |
| Asia Pacific | China, Japan, India, South Korea, Australia |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Israel |
This divergence implies two distinct go-to-market motions: in North America, vendors compete on ecosystem lock-in and software tooling; in Asia-Pacific, they compete on sovereign alignment and localized supply. Export-control fragmentation is the second-order effect most buyers underestimate — it channels demand toward domestically aligned suppliers and raises switching costs for any operator with cross-border workloads.
Growth is driven primarily by AI/ML workload proliferation (+3.2% CAGR impact) and the race-to-exascale public funding surge (+2.8%), offset by ballooning datacenter power costs (−2.4%) and advanced-node supply-chain fragility (−2.1%).
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| AI/ML workload proliferation | Driver | High | Inference and training pervade HPC centers; demands HBM and heterogeneous compute |
| Race-to-exascale public funding | Driver | High | DOE, EuroHPC, Japan, China programs fund next-gen systems |
| Cloud HPC-as-a-Service availability | Driver | Medium-High | Elastic clusters remove capex barriers for mid-market buyers |
| Digital-sovereignty programs | Driver | Medium | National programs favor domestically aligned suppliers |
| Datacenter power & cooling costs | Restraint | High | Exascale systems draw 20–40 MW; energy can exceed amortized hardware cost |
| Parallel-programming talent gap | Restraint | High | Scarcity of skilled HPC/AI engineers slows utilization |
| Advanced-node supply-chain fragility | Restraint | Medium-High | Leading-edge fab concentration constrains accelerator supply |
| Lengthy public procurement cycles | Restraint | Medium | Government-heavy demand base stretches deal timelines |
The balance of evidence favors the drivers: demand is structurally undersupplied through 2028, and power availability — not chips — is emerging as the binding constraint. Our analysis suggests operators that lock in long-term power-purchase agreements and liquid-cooling capacity now will hold a durable cost advantage; those that wait will pay a premium that erodes the economics of the very AI workloads they are buying capacity for.
Vendor leadership is bifurcated: NVIDIA dominates the accelerator layer and its software ecosystem, while HPE, Dell, Lenovo, and Atos compete on full-system integration — and AWS, Microsoft Azure, and Google Cloud increasingly control the buyer relationship through HPC-as-a-Service.
| Vendor | Primary Position | Structural Advantage | Strategic Vulnerability |
|---|---|---|---|
| NVIDIA | Accelerators, networking, CUDA stack | Ecosystem lock-in and developer mindshare | Export-control exposure; customer concentration |
| HPE | Full-system integration, Cray lineage | Exascale credentials; government relationships | Margin pressure from cloud disintermediation |
| Intel | CPUs, accelerators (Gaudi), oneAPI | Broad installed base | Lagging accelerator share vs. NVIDIA |
| AMD | CPUs and MI-series accelerators | Price-performance in memory-rich workloads | Software stack maturity |
| Fujitsu | A64FX, Fugaku lineage | Arm-based efficiency credentials | Limited commercial footprint |
| Atos | European HPC systems | Sovereign-alignment advantage in EU | Scale disadvantage vs. U.S. vendors |
| AWS / Azure / Google Cloud | Cloud HPC-as-a-Service | Elastic capacity, capital access, AI service bundling | Energy and data-residency constraints |
Competitive moats are shifting from hardware performance to software and orchestration. NVIDIA's CUDA and interconnect stack remains the deepest moat in the industry; the credible counter-argument is that open standards (UXL, oneAPI) plus hyperscaler custom silicon will erode it over a five-year horizon. Our analysis suggests the moat is durable through 2028 but narrows materially beyond that window.
Selection criteria have inverted. Five years ago, peak FLOPS dominated the decision; today, performance-per-watt, interconnect latency, and software-stack portability carry equal or greater weight. Buyers should evaluate total cost of ownership across a five-year horizon including power, cooling, and re-tooling — not sticker price. Procurement risk centers on three areas: accelerator allocation lead times, export-control eligibility for cross-border deployments, and vendor lock-in at the compiler and scheduler layer. Switching costs are highest at the software stack, not the silicon; a platform migration typically costs 20–40% of the original system value in re-engineering and retraining. Compliance obligations — data residency, sovereign AI mandates, and increasingly energy-efficiency disclosure — should be treated as architectural inputs, not post-hoc legal review. While this overview establishes the strategic frame, precise sub-segment forecasting and vendor-by-vendor TCO modeling require the full report.
The balance of evidence favors a platform-integration thesis over a hardware-thesis. Demand for AI supercomputing capacity is structurally undersupplied through 2028, but value is migrating from the silicon layer to the orchestration and services layer. The strongest counter-argument — that NVIDIA's ecosystem lock-in preserves hardware-layer value capture indefinitely — is credible but ignores how rapidly hyperscalers are deploying custom accelerators and how aggressively open software stacks are maturing. The divergence between 22% AI-hardware growth and ~11% total-supercomputer growth is not a data error; it is the signature of a market in transition, and transitions reward integrators over component sellers.
For operators, the binding constraints through 2027 will be power, cooling, and engineering talent — not chips. Buyers who treat power procurement as a first-order strategic decision, and who architect for software portability from day one, will hold a structural cost advantage. Investors should watch three leading indicators: liquid-cooling capacity bookings, HPC-as-a-Service contract backlog at hyperscalers, and accelerator allocation lead times — each moves 2–4 quarters ahead of reported revenue.
Actionable strategy:
What would change our conclusion: a sustained acceleration in open-standard software maturity (UXL, oneAPI) that commoditizes the accelerator stack faster than hyperscaler custom silicon scales — that combination would compress hardware margins sooner than our base case assumes.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.7% from 2020-2034 |
| Segmentation |
|
The AI Supercomputing Platforms Market was valued at approximately 12.25 Billion in 2025. This blended figure reconciles published estimates ranging from a narrow 1.91 Billion AI-hardware-only category to a 13.29 Billion total-supercomputer benchmark, weighted by AI workload share.
Our base case assumes a 12.7% CAGR from 2026 to 2035. AI-native platforms grow faster at 19–22%, while general-purpose supercomputers grow near 11%, and the blended rate reflects the AI workload share of total deployed capacity.
North America leads with roughly 37% revenue share in 2025, driven by U.S. Department of Energy programs and hyperscaler AI buildouts. Asia-Pacific is the fastest-growing region at a 12.55% CAGR, led by China, Japan, and India national programs.
Accelerators (GPU/ASIC) grow fastest on the component axis at a 15.05% CAGR, and cloud HPC-as-a-Service grows fastest on the deployment axis at 19.98% CAGR. Exascale installations grow at 26.18% CAGR, the fastest processing-scale segment.
NVIDIA dominates accelerators and software tooling; HPE, Dell, Lenovo, and Atos lead full-system integration; AWS, Microsoft Azure, and Google Cloud control the HPC-as-a-Service buyer relationship. Intel, AMD, and Fujitsu hold distinct positions in CPUs and Arm-based efficiency.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
We apply a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the AI supercomputing value chain with five stakeholder cohorts: accelerator and processor suppliers, system integrators and OEMs, cloud/HPC-as-a-Service operators, enterprise and government end-users, and HPC software and orchestration vendors. Decision-maker designations interviewed include VP of Infrastructure, Head of HPC/AI Platforms, Chief Technology Officers, and Procurement & Sourcing Directors. Fieldwork captures deployment timelines, performance-per-watt requirements, software-stack preferences, and procurement risk factors that published benchmarks cannot resolve.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Infrastructure & CTOs | 35% |
| HPC/AI Platform Heads | 30% |
| Procurement & Sourcing Directors | 20% |
| Software & Orchestration Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Accelerator & Processor Suppliers | 30% |
| System Integrators & OEMs | 25% |
| Cloud / HPC-as-a-Service Operators | 25% |
| End-Users (Government & Enterprise) | 20% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, Eurostat, US ITC), corporate annual filings and SEC 10-K disclosures from listed vendors, patent databases for accelerator and interconnect innovation tracking, and recognized technical standards bodies and industry associations. All public benchmarks are cross-checked against filing-level capacity and revenue disclosures before inclusion in our models.
We run simultaneous Top-Down and Bottom-Up triangulation. Top-down allocates macroeconomic IT and HPC spend across segments using industry output and government budget data. Bottom-up models manufacturer capacity, accelerator shipment volumes, average selling prices, and end-use consumption to derive independently reconciled revenue. Divergences above 8% trigger re-validation against primary interview data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up shipment & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |