 Malaysia Contact Center Software Market
 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 239

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Malaysia Contact Center Software Market
Srinwanti Kar
Senior Research Analyst

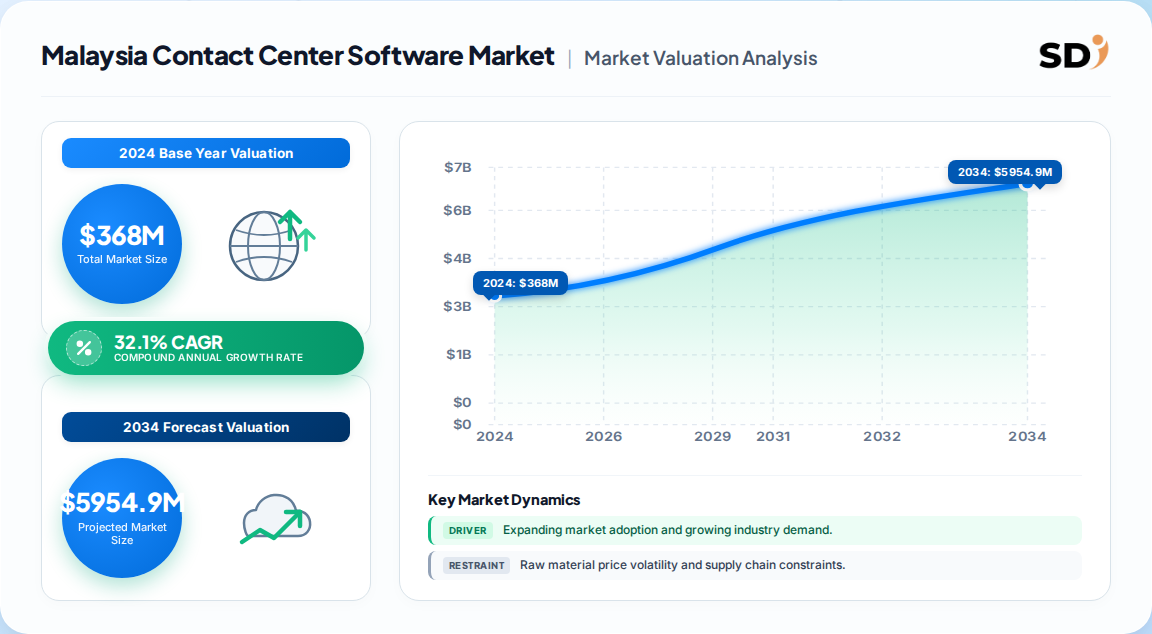
| Year | Market Size |
|---|---|
| 2024 | 368.0 M |
| 2025 | 486.0 M |
| 2026 | 642.0 M |
| 2027 | 848.0 M |
| 2028 | 1.100 B |
| 2029 | 1.500 B |
| 2030 | 1.900 B |

The Malaysia contact center software market covers platforms and services that manage inbound and outbound customer interactions across voice, chat, email, social, and messaging channels. It spans ACD, IVR, CTI, workforce optimization, analytics, and collaboration tools, delivered via cloud/hosted or on-premise models to enterprises and BPO providers.
This report covers software solutions (ACD, IVR, CTI, customer collaboration, workforce optimization, analytics, recording, dialer), services (integration & deployment, support & maintenance, training, managed services), deployment models (hosted/cloud, on-premise), enterprise sizes (large, SME), and end-use verticals (IT & telecom, BFSI, government, healthcare, travel & hospitality, retail) within Malaysia. It includes vendor and competitive analysis plus demand-side procurement dynamics.
This analysis does not cover adjacent markets such as unified communications (UCaaS) outside the contact center, CPaaS-only messaging platforms, hardware/telephony equipment, or IT outsourcing services that do not bundle contact center software.
One published estimate puts the Malaysia contact center software market at USD 368.0 million in 2024, rising to USD 4,293.0 million by 2033 at a 32.1% CAGR — a trajectory that implies roughly a 11.7x expansion in under a decade.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 368.0 million | 2024 | 2033 | 32.1% | Malaysia contact center software, all solutions/services/deployments | One published Malaysia-specific estimate |
| APAC CAGR ~24.2% | 2024 | 2031 | 24.2% | Asia Pacific contact center software (Malaysia as a sub-market) | A competing regional analysis |
| Global CAGR ~15.4%–16.7% | 2025/2026 | 2031/2040 | 15.4–16.7% | Global contact center software | Two competing global analyses |
Our analysis suggests the 32.1% Malaysia figure is aggressive but defensible: it is anchored to a small base (~USD 368M) and reflects a low starting penetration of cloud/AI contact center software. The APAC regional benchmark (~24.2%) implies Malaysia is growing faster than the regional average, consistent with its BPO hub status and MyDIGITAL-driven cloud adoption. A more conservative reading would cluster the true CAGR in the 24–30% band, with 32.1% representing the upside case if GenAI agent adoption accelerates.
The Malaysia contact center software market segments along four primary axes: solution, service, deployment, and enterprise size/end-use — with solution and service mix the strongest determinants of vendor positioning.
| Parent Segment | Children |
|---|---|
| By Solution | ACD, IVR, CTI, Customer Collaboration, Workforce Optimization, Reporting & Analytics, Call Recording, Dialer, Outbound |
| By Service | Integration & Deployment, Support & Maintenance, Training & Consulting, Managed Services, Other Services |
| By Deployment | Hosted/Cloud, On-Premise |
| By Enterprise Size | Large Enterprise, SME |
| By End-Use | IT & Telecom, BFSI, Government, Healthcare, Travel & Hospitality, Consumer Goods & Retail, Others |
ACD (20.8%) leads on the strength of multilingual, skill-based routing — critical in a market with Bahasa Malaysia, English, Mandarin, and Tamil customer bases. Customer Collaboration (37.2% CAGR) is the fastest-growing solution as messaging-app-first consumers push brands toward unified digital dashboards. In services, Integration & Deployment (42.4%) dominates near-term revenue because legacy-to-cloud migration is the primary buying trigger.
Malaysia's contact center software demand is concentrated in Klang Valley (Greater Kuala Lumpur), which we estimate at roughly 52% of national spend, followed by Johor (~14%) and Penang (~12%), reflecting the geographic footprint of BPO hubs, shared-service centers, and enterprise headquarters.
| Region | Market Share (%) |
|---|---|
| Klang Valley (Greater Kuala Lumpur) | 0.52% |
| Johor | 0.14% |
| Penang | 0.12% |
| Sabah & Sarawak | 0.09% |
| Other States | 0.13% |
| Parent | Children |
|---|---|
| Peninsular Malaysia — Central | Klang Valley (Kuala Lumpur, Selangor, Putrajaya) |
| Peninsular Malaysia — Southern | Johor (Johor Bahru/Medini), Melaka |
| Peninsular Malaysia — Northern | Penang (George Town/Bayan Lepas), Kedah, Perak |
| East Malaysia | Sabah, Sarawak (Kota Kinabalu, Kuching) |
Our analysis suggests the Klang Valley's dominance is structural: it hosts the majority of BPO delivery centers, shared-service hubs for MNCs, and the deepest pool of multilingual agents. Johor's growth is tied to Singapore cross-border BPO spillover, while Penang's is anchored in E&E and manufacturing-sector customer support. Sabah and Sarawak remain underpenetrated but benefit from government digital-infrastructure programs.
Growth is driven by MyDIGITAL-fuelled cloud adoption, omnichannel CX expectations, AI/GenAI agent deployment, and Malaysia's rise as a Southeast Asian BPO hub — while high implementation costs, legacy dependencies, and regulatory complexity constrain the pace.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| MyDIGITAL & cloud adoption | Driver | High | National blueprint promotes cloud infrastructure, lowering CCaaS barriers |
| Omnichannel CX demand | Driver | High | Consumers use ~4+ channels per issue; unified routing becomes mandatory |
| GenAI autonomous agents | Driver | Medium-High | Tier-1 resolution cuts cost-per-contact; drives platform refresh |
| BPO hub expansion | Driver | High | Multilingual talent + incentives pull cloud/AI contact center spend |
| High implementation & integration cost | Restraint | High | Licensing, CRM/AI integration, cybersecurity raise upfront burden, especially for SMEs |
| Legacy system dependencies | Restraint | Medium | On-premise estates slow migration and complicate integration |
| Regulatory & data-protection complexity | Restraint | Medium | PDPA compliance and cross-border data rules add design overhead |
The balance of evidence favors the drivers: Malaysia's BPO and shared-services footprint gives it a structural demand base that is less cyclical than pure domestic CX spend. However, the restraint slate is not trivial — implementation cost is the single biggest friction for SMEs, which is precisely why managed services and consumption-based CCaaS pricing are growing fastest. Vendors that cannot reduce time-to-value from months to weeks will cede the SME segment to platform-native competitors.
The Malaysia contact center software landscape is contested by global CCaaS platforms (Genesys, NICE, Five9, Cisco, AWS, Microsoft, Twilio) and regional integrators/BPO-aligned providers that bundle deployment and managed services.
| Vendor | Primary Strength | Typical Buyer Profile | Differentiator |
|---|---|---|---|
| Genesys | Omnichannel orchestration, AI (RAG) | Large enterprise, BFSI, telco | Deep routing + AI pilot evidence (82% FCR in pilots) |
| NICE | Workforce optimization, digital-first routing | Large enterprise, BPO | WFO + analytics heritage |
| Five9 | Cloud-native CCaaS, GenAI virtual agents | Mid-market to large | Fast CCaaS deployment, GPT-powered agents |
| Cisco | Enterprise telephony/contact center integration | Large enterprise, government | Installed-base lock-in, Webex ecosystem |
| AWS (Amazon Connect) | Consumption-priced cloud contact center | SME to large, digital-native | Pay-per-use, cloud-native elasticity |
| Microsoft | Teams-integrated contact center | Microsoft 365 estates | Collaboration-estate leverage |
| Twilio | CPaaS/API-led contact center | Developers, digital-first brands | Programmable flexibility |
Competitive moats in Malaysia hinge less on feature breadth and more on three things: (1) integration depth with local CRM/payment/telecom systems, (2) multilingual and skill-based routing quality, and (3) managed-services capacity to absorb operational burden. Global platforms win large-enterprise bake-offs; regional integrators win on service intimacy and price flexibility. Our analysis suggests the mid-market and SME segments will be won by vendors offering consumption pricing plus local implementation partners — a segment where global platforms alone are structurally disadvantaged.
Buyers should prioritize total cost of ownership over sticker price, integration readiness with existing CRM and payment systems, multilingual routing quality, and PDPA/regulatory compliance. Procurement risk concentrates in vendor lock-in (egress fees, proprietary AI models), migration downtime, and the hidden cost of AI add-ons that are priced separately from core seats.
Switching costs rise sharply after integration: once CRM, payment gateways, and AI analytics are wired into a platform, re-platforming typically takes 6–12 months and carries meaningful operational risk. Buyers should therefore negotiate exit clauses, data-portability terms, and multi-year price protection before signing. Compliance is a second front: Malaysia's PDPA and sector-specific rules in BFSI and healthcare require audit trails, consent management, and data-residency options — capabilities that vary significantly across vendors. Finally, buyers should stress-test AI agent accuracy and escalation logic in pilot, because GenAI resolution rates in vendor demos rarely match production without tuning.
The balance of evidence favors a bullish but disciplined view of the Malaysia contact center software market. The 32.1% CAGR headline is the upside case; a 24–30% band is more defensible, but even the conservative end implies the market roughly triples by 2030. The strongest counter-argument is that Malaysia's base is small and its SME segment is price-sensitive, which could compress realized growth if vendors cannot drive down implementation costs. We weigh this as a timing risk, not a structural one.
The second-order effect most analysts miss is that Malaysia's BPO hub status makes its contact center software demand partly export-driven: decisions are increasingly made by global BPO clients and MNC shared-service centers, not just domestic buyers. This means vendor selection criteria are set internationally (security, compliance, multi-country scalability), which favors global platforms — but the implementation and managed-services layer remains locally contested. The implication: the winning model is a global platform paired with a strong local integrator, and vendors without local service depth will struggle to convert wins into recurring revenue.
Actionable strategy:
What would change our conclusion: a sharper-than-expected SME adoption slowdown, regulatory tightening on cross-border data flows, or evidence that GenAI agents reduce seat counts faster than new use cases expand them. Precise sub-segment forecasting — particularly the SME vs. large-enterprise split and vertical-level CAGR by BFSI, healthcare, and retail — requires the full report's bottom-up modeling.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 32.1% from 2020-2034 |
| Segmentation |
|
The Malaysia contact center software market was estimated at USD 368.0 million in 2024 and is projected to reach USD 4,293.0 million by 2033, registering a 32.1% CAGR from 2025 to 2033, according to one published estimate.
Customer Collaboration is the fastest-growing solution segment at a 37.2% CAGR, driven by messaging-app adoption. Managed Services is the fastest-growing service segment as mid-sized firms outsource operations to avoid upfront infrastructure costs.
The Klang Valley (Greater Kuala Lumpur) leads with an estimated 52% of national spend, followed by Johor (~14%) and Penang (~12%), reflecting the concentration of BPO hubs, shared-service centers, and enterprise headquarters.
Leading vendors include Genesys, NICE, Five9, Cisco, AWS (Amazon Connect), Microsoft, and Twilio, alongside regional integrators. Competition centers on AI capability, omnichannel routing, integration depth, and local managed-services capacity.
Key drivers include the MyDIGITAL blueprint promoting cloud adoption, rising omnichannel customer expectations, GenAI autonomous-agent deployment, and Malaysia's expansion as a Southeast Asian BPO hub with multilingual talent and supportive incentives.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the Malaysia contact center software value chain with: cloud/hosted platform vendors; on-premise legacy system providers; systems integrators and deployment partners; managed-services and BPO operators; and enterprise/end-user buyers. Decision-maker designations interviewed include Chief Information Officers, Heads of Customer Experience, VP-level Sourcing and Procurement Leads, and Contact Center Operations Directors. Interviews focused on deployment timelines, switching costs, AI adoption readiness, and procurement criteria.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CIOs & IT Heads | 35% |
| Heads of Customer Experience | 30% |
| Procurement & Sourcing Leads | 20% |
| Contact Center Operations Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Cloud/CCaaS Platform Vendors | 40% |
| Systems Integrators & Deployment Partners | 25% |
| BPO & Managed-Service Operators | 20% |
| Enterprise & End-User Buyers | 15% |
Secondary validation draws on official multilateral databases (UN Comtrade, WTO, Malaysia's Department of Statistics), corporate annual filings and investor presentations (10-K, Bursa Malaysia filings), patent databases, and recognized standards and industry bodies including the Contact Center Association of Malaysia, ISO 18295-1, and Malaysia's Personal Data Protection Act (PDPA) regulatory guidance.
We run simultaneous Top-Down (macroeconomic and industry-segment allocation across BFSI, IT & telecom, healthcare, retail, and government) and Bottom-Up (vendor seat capacity, per-seat pricing, and end-use consumption modeling) triangulation. Divergences are reconciled through weighted averaging and cross-validated against public benchmarks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up seat/revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | State-level share breakdown | Cross-border trade flow and regional consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |