 Us Organ Donation Transplant Software Market
U.S. Organ Donation Transplant Software Market 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 186

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Organ Donation Transplant Software Market
Srinwanti Kar
Senior Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 57.00 M |
| 2026 | 61.00 M |
| 2027 | 64.00 M |
| 2028 | 68.00 M |
| 2029 | 72.00 M |
| 2030 | 76.00 M |
| 2031 | 81.00 M |

The U.S. organ donation and transplant software market covers digital platforms that coordinate donor identification, organ offer and match-run management, waitlist and recipient tracking, histocompatibility data exchange, logistics, and regulatory reporting to OPTN/UNOS and HRSA. Buyers are organ procurement organizations (OPOs), transplant centers, and histocompatibility laboratories.
This report sizes software and platform revenue sold to U.S. OPOs, transplant centers, and histocompatibility labs, segmented by software type, deployment mode, application, and end-use. It covers workflow automation, registry submission tooling, and analytics layers. This analysis does not cover the broader organ transplantation products market — immunosuppressants, preservation solutions, tissue products, or surgical devices — nor global ex-U.S. software spend.
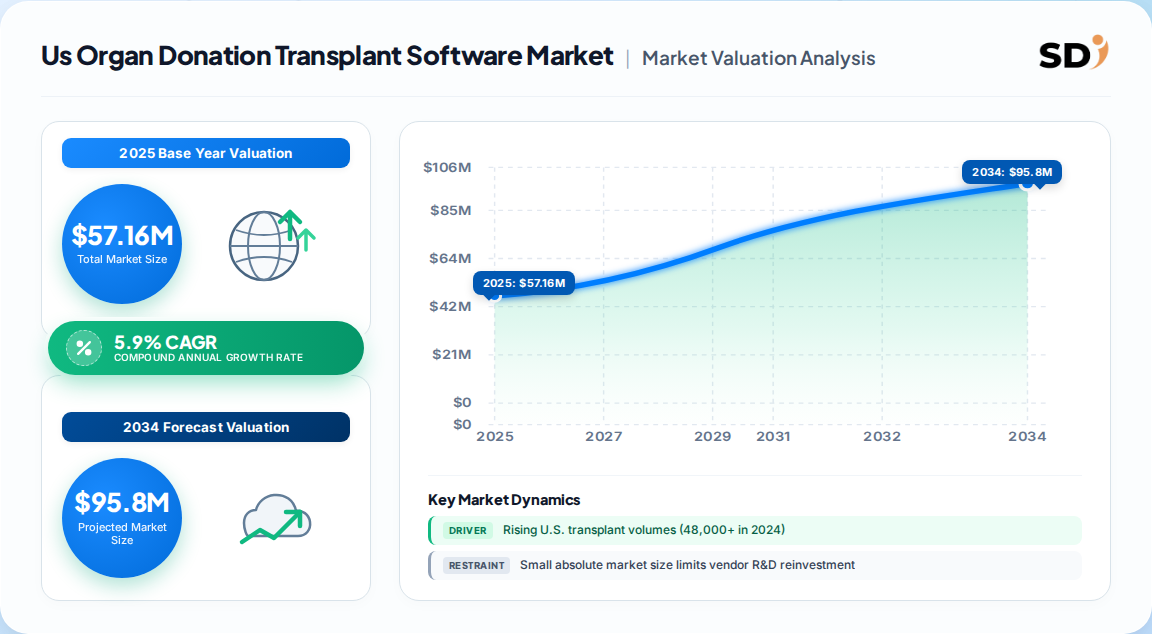
The U.S. market is small but structurally growing: roughly USD 57 million in 2025 rising to USD 90 million by 2033, implying incremental annual software spend of about USD 4 million per year.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 57.16M → USD 90.04M | 2025 | 2033 | 5.9% | U.S. software only: transplant management, OPO logistics, waitlist, analytics | One published estimate |
| USD 118.5B by 2034 | 2024 | 2034 | 9.7% | Global organ transplantation products (tissue, drugs, preservation) | A competing analysis |
| Implied software attach rate | 2025 | — | — | Software spend indexed to 48,000+ annual U.S. transplants | Our analysis |
Our analysis suggests the software figure is the defensible planning number. The USD 118.5 billion figure is a different market entirely — therapeutics and preservation consumables — and should never be used to size software budgets. The divergence implies software monetization remains thin relative to clinical throughput, which is both the growth runway and the pricing constraint.
Segmentation follows four axes: software type, deployment mode, application, and end-use, with transplant management systems and cloud delivery dominating 2025 revenue.
| Parent segment | Children |
|---|---|
| Software Type | Transplant management systems; Organ procurement & logistics; Waitlist & recipient management; Histocompatibility/lab systems; Analytics & reporting |
| Deployment Mode | Cloud-based; On-premise |
| Application | Organ donation workflow automation; Donor-recipient matching; Offer & match-run management; Post-transplant follow-up |
| End-use | Transplant centers; OPOs; Histocompatibility labs; Hospitals |
Transplant management systems command roughly a third of revenue because they sit at the workflow center. Cloud's 65.52% share signals that buyers now treat hosted, interoperable platforms as the default rather than the exception.
Spend concentrates where transplant volume and OPO density are highest: the South and West, followed by the Northeast and Midwest.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.22% |
| South | 0.31% |
| Midwest | 0.23% |
| West | 0.24% |
| Region | Share |
|---|---|
| South | 31% |
| West | 24% |
| Midwest | 23% |
| Northeast | 22% |
Our analysis suggests regional share tracks transplant-center concentration more than population. Single-state OPOs in the South and West are the fastest procurement decision units, while multi-state networks in the Northeast favor enterprise-wide contracts that lengthen sales cycles but raise deal value.
Growth is driven by transplant volume, mandatory registry reporting, and matching accuracy; it is restrained by a small software pool, long public-procurement cycles, and integration burden.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising transplant volumes | Driver | High | 48,000+ U.S. transplants in 2024; larger donor pools and match-run frequency |
| OPTN/UNOS & HRSA reporting mandates | Driver | High | Audit-ready submission automation becomes mandatory spend |
| AI-assisted donor-recipient matching | Driver | Moderate | Predictive scoring and faster data processing raise platform value |
| Cloud migration | Driver | High | 65.52% cloud share lowers deployment friction |
| Small absolute market size | Restraint | High | Limits vendor R&D reinvestment and pricing power |
| OPO procurement complexity | Restraint | Moderate | Public and non-profit buying cycles delay revenue |
| EHR/lab interoperability gaps | Restraint | Moderate | Integration cost shifts budget from license to services |
The balance favors growth: regulatory mandates are non-discretionary, so software spend is largely protected even in budget tightening. The binding constraint is not demand but vendor capacity to deliver compliant integration at a price the market can absorb.
The field is fragmented across transplant management suites, OPO logistics specialists, and AI-enabled challengers, with no single dominant share.
| Vendor archetype | Positioning | Moat |
|---|---|---|
| Transplant management suite incumbents | End-to-end referral-to-follow-up | Deep UNOS/EHR integration and installed base |
| OPO logistics specialists | Organ transport and offer management | Network effects across OPO relationships |
| AI-native platforms (e.g., cloud transplant management with predictive modeling) | Matching accuracy and real-time analytics | Model performance and HIPAA/GDPR-ready architecture |
| Histocompatibility/lab vendors | Lab data exchange | Tight lab-system coupling |
Our analysis suggests moats rest on integration depth, not features. A platform that automates UNOS submission and bi-directional EHR/lab exchange is materially harder to displace than one differentiated on dashboards.
Selection should be anchored on regulatory submission integrity first, interoperability second, and analytics third. Buyers should demand demonstrated OPTN/UNOS submission automation, audit trails, and bi-directional EHR and histocompatibility lab interfaces — not roadmap promises. Procurement risk concentrates in implementation: integration services can exceed license cost in year one.
Switching costs are high and asymmetric. Once match-run logic and historical outcome data reside in a platform, migration risk is clinical as well as financial, which favors incumbents but also exposes buyers to renewal pricing. Operators should negotiate data-portability clauses and outcome-data escrow before signature.
Compliance is continuous, not a one-time gate. Vendors must track UNOS/OPTN policy revisions, HRSA reporting changes, and CMS quality metrics; a platform that lags a policy cycle creates audit exposure. Our analysis suggests compliance velocity — the speed of policy-driven updates — is the single best predictor of long-term vendor fitness.
The balance of evidence favors a compliance-led, consolidation-bound market. Sub-USD 100 million revenue against 48,000 annual transplants means software is under-monetized; regulatory mandates, not marketing, will close that gap. The strongest counter-argument is that AI matching could commoditize workflow layers — but matching still runs through OPTN policy, so compliant orchestration remains the tollgate.
Second-order effects matter here. Cloud's 65.52% share lowers entry barriers, inviting AI-native challengers; simultaneously, integration depth raises exit barriers for incumbents. The result is a barbell: specialists win modules, suites win accounts, and mid-tier generalists get squeezed.
What would change our conclusion: evidence of OPO consolidation compressing vendor counts faster than expected, or a federal mandate standardizing transplant data exchange, which would shift value decisively toward integration-layer providers.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.9% from 2020-2034 |
| Segmentation |
|
It was estimated at USD 57.16 million in 2025 and is projected to reach USD 90.04 million by 2033, growing at a 5.9% CAGR from 2026 to 2033.
Cloud-based deployment led with 65.52% share in 2025, driven by interoperability requirements and lower upfront capital costs for OPOs and transplant centers.
Organ procurement and logistics software is expected to grow fastest as OPOs prioritize transport efficiency and time-critical organ allocation workflows.
Transplant centers, organ procurement organizations, histocompatibility laboratories, and hospitals, mainly to automate UNOS/OPTN reporting and donor-recipient matching.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the transplant software value chain, including transplant management platform developers, OPO logistics software vendors, histocompatibility and laboratory interface providers, systems integrators serving transplant centers, and hospital IT procurement groups. Decision-maker designations interviewed included Chief Information Officers at OPOs, Transplant Center Program Directors, Histocompatibility Laboratory Directors, and Clinical Informatics Leads, ensuring demand-side validation of both workflow requirements and budget authority.
| Stakeholder Role | Interview Share (%) |
|---|---|
| OPO Chief Information Officers | 35% |
| Transplant Center Program Directors | 30% |
| Histocompatibility Lab Directors | 20% |
| Clinical Informatics Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Transplant Management Platform Vendors | 40% |
| OPO Logistics Software Specialists | 25% |
| Histocompatibility & Lab Interface Providers | 20% |
| Systems Integrators & Hospital IT | 15% |
Secondary validation drew on official registries and public filings: OPTN/UNOS data on U.S. transplant volumes and match-run activity, HRSA reporting requirements, CMS quality metrics, SEC 10-K filings and investor presentations from publicly traded healthcare IT vendors, USPTO patent filings for matching algorithms, and industry association publications. Cross-border software and services trade was benchmarked against U.S. Bureau of Economic Analysis and Eurostat ICT services statistics.
Market sizing was triangulated simultaneously top-down and bottom-up. The top-down model allocates U.S. healthcare IT spend across transplant-specific workflows using OPO and transplant-center counts. The bottom-up model aggregates vendor license, subscription, and implementation revenue by end-use segment, cross-checked against transplant volume and per-center software spend.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up vendor revenue and subscription triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis, regulatory-demand elasticity | High |
| Regional Distribution | Regional share breakdown | Transplant-center density and OPO footprint mapping | High |
| Competitive Landscape | Leading market players | Annual reports, product mapping, commercial filings | High |
