 Digitally Printed Wallpaper Market
: Size, Share & Forecast
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 191

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Digitally Printed Wallpaper Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 6.500 B |
| 2025 | 7.700 B |
| 2026 | 9.100 B |
| 2027 | 10.80 B |
| 2028 | 12.80 B |
| 2029 | 15.10 B |
| 2030 | 17.90 B |

The digitally printed wallpaper market encompasses wall coverings produced through digital printing technologies—primarily inkjet and electrophotography—onto substrates such as vinyl, nonwoven, paper, and fabric. Unlike traditional methods, digital printing enables high-resolution, customized designs with short production runs, serving both residential and commercial interior applications.
This report covers the global market for digitally printed wallpaper, segmented by substrate (vinyl, nonwoven, fabric, paper, fiberglass), printing technology (inkjet, electrophotography), application (residential, commercial, transportation), and region. It includes market sizing, forecasts, competitive landscape, and strategic analysis. This analysis does not cover traditional analog-printed wallpaper, wall murals applied via other methods, or adjacent markets such as wall panels, cladding, or paint.
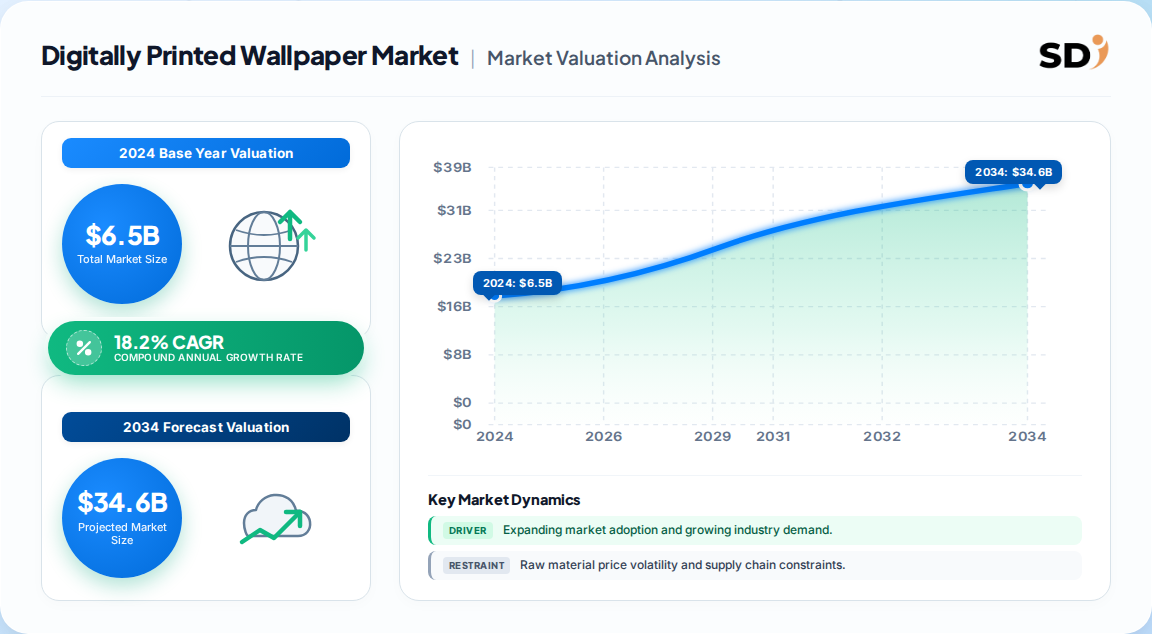
The global digitally printed wallpaper market was valued at $6.5 billion in 2024, with forecasts reaching $40.9 billion by 2035 at an 18.2% CAGR. However, estimates vary significantly due to scope differences and base-year definitions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| $2.71 billion | 2022 | 2030 | 18.2% | Global, narrow definition (excludes some specialty substrates) | One published estimate |
| $6.5 billion | 2024 | 2035 | 18.2% | Global, broader definition including transportation | A competing analysis |
| $4.8 billion | 2022 | 2028 | 23.09% | Global, includes all substrate types | Another published estimate |
Our analysis suggests the $6.5 billion (2024) figure is the most defensible baseline, as it aligns with the broader market definition and recent growth trends. The $2.71 billion (2022) estimate likely undercounts the transportation segment and some nonwoven applications, while the $4.8 billion (2022) figure appears inflated by including non-digital printed products. The 18.2% CAGR consensus is robust across sources, though Stratview's 23.09% may reflect a narrower base and aggressive near-term adoption assumptions.
The digitally printed wallpaper market is segmented by substrate, printing technology, and application.
| Parent Segment | Children |
|---|---|
| By Substrate | Vinyl, Nonwoven, Paper, Fabric, Fiberglass |
| By Printing Technology | Inkjet, Electrophotography |
| By Application | Residential, Commercial, Transportation |
Vinyl dominates due to durability and versatility, while nonwoven is the fastest-growing substrate, favored for its digital print compatibility and eco-friendly profile. Inkjet is the leading printing technology, with electrophotography gaining traction for high-volume runs.
North America leads the global digitally printed wallpaper market with over 37% revenue share in 2022, driven by high renovation activity and strong commercial construction. Asia-Pacific is the fastest-growing region at a 19.8% CAGR, propelled by rapid urbanization and hospitality expansion.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.26% |
| Asia-Pacific | 0.24% |
| South America | 0.06% |
| Middle East & Africa | 0.07% |
Geography Tree (Global Scope):
| Region | Share (2022) |
|---|---|
| North America | 37% |
| Europe | 26% |
| Asia-Pacific | 24% |
| South America | 6% |
| Middle East & Africa | 7% |
North America's dominance is underpinned by a mature renovation market and high consumer spending on home décor. However, Asia-Pacific's growth trajectory suggests a shift in global demand centers, with China and India driving both production and consumption. Europe remains a strong second, with sustainability regulations shaping product innovation.
The market is propelled by customization trends, technological advancements, and the expansion of e-commerce, but faces restraints from raw material price volatility and skilled labor shortages.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Customization and personalization | Driver | High | Consumers seek unique designs; digital printing enables short runs at low cost |
| Technological advancements | Driver | High | Inkjet and electrophotography improvements enhance quality and speed |
| E-commerce expansion | Driver | Medium | Online platforms increase accessibility and design variety |
| DIY home decor trend | Driver | Medium | Easy application/removal encourages frequent updates |
| Raw material price volatility | Restraint | Medium | Vinyl and paper costs fluctuate, squeezing margins |
| Skilled labor shortage | Restraint | Low | Installation requires expertise; DIY mitigates but limits premium adoption |
Our analysis suggests the balance tilts strongly toward growth, with drivers outweighing restraints. The customization trend is the most powerful, as it shifts wallpaper from a commodity to a design service, enabling premium pricing. Sustainability concerns are also reshaping demand, with eco-friendly materials gaining traction. However, raw material volatility could pressure margins, particularly for vinyl-heavy producers, necessitating strategic sourcing and alternative substrates.
The market is moderately consolidated, with key players competing on design innovation, sustainability, and distribution reach.
| Company | Headquarters | Strengths |
|---|---|---|
| A.S. Création | Germany | Broad design portfolio, European market leader |
| Brewster Home Fashions | USA | Strong North American distribution, e-commerce focus |
| York Wallcoverings | USA | Heritage brand, commercial contracts |
| Grandeco Wallfashion | Belgium | Digital printing specialization, customization |
| Sanderson Design Group | UK | Premium designs, licensing |
Differentiation hinges on design capability and speed-to-market. Brewster and York leverage scale and retail relationships, while A.S. Création and Sanderson focus on premium, designer collaborations. Grandeco's digital-native approach gives it an edge in customization. Competitive moats include proprietary design libraries, sustainable material patents, and exclusive distribution agreements. Our analysis suggests consolidation is likely as larger players acquire niche digital printers to expand capabilities.
Buyers must prioritize substrate compatibility with digital printing technologies, ensuring consistent color reproduction and durability. Vinyl offers durability but faces environmental scrutiny; nonwoven balances sustainability and print quality. Procurement risks include supply chain disruptions for specialty papers and inks, and currency fluctuations for imported materials. Switching costs are moderate, as re-tooling for new substrates requires recalibration but not full equipment replacement. Regulatory compliance—particularly low-VOC emissions and fire safety standards—is critical in commercial applications, with certifications like GREENGUARD and ASTM E84 influencing purchasing decisions. Operators should also consider total cost of ownership, factoring in installation complexity and lifecycle costs. Digital printed wallpaper reduces waste versus analog, but end-of-life recyclability varies by substrate.
The balance of evidence favors a bullish outlook for the digitally printed wallpaper market, with the 18.2% CAGR consensus appearing sustainable through 2035. However, the divergence in market size estimates ($2.71B vs. $6.5B for similar base years) underscores definitional ambiguity that buyers must navigate. Our analysis suggests the broader definition—including transportation and all substrates—better reflects commercial reality, as digital printing penetrates diverse applications. The strongest counter-argument is that e-commerce growth may cannibalize traditional retail channels, depressing margins; yet this is offset by the premiumization of customized designs. We maintain that customization and sustainability are structural shifts, not fads.
Actionable Strategy:
What would change our conclusion? A sustained reversal in residential renovation spending, or a technological breakthrough that renders digital printing obsolete (e.g., 3D-printed walls), could disrupt the trajectory. Additionally, if raw material prices spike beyond 2022 levels and cannot be passed through, margin compression could slow adoption. We recommend monitoring these indicators quarterly.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 18.2% from 2020-2034 |
| Segmentation |
|
The global digitally printed wallpaper market was valued at $6.5 billion in 2024 and is projected to reach $40.9 billion by 2035, growing at an 18.2% CAGR.
North America leads with over 37% revenue share, driven by high renovation activity and commercial construction. Asia-Pacific is the fastest-growing region at 19.8% CAGR.
The market is segmented by substrate (vinyl, nonwoven, paper, fabric, fiberglass), printing technology (inkjet, electrophotography), and application (residential, commercial, transportation). Vinyl leads substrates; commercial leads applications.
Key players include A.S. Création, Brewster Home Fashions, York Wallcoverings, Grandeco Wallfashion, and Sanderson Design Group, competing on design innovation and sustainability.
Growth is driven by customization trends, technological advancements in printing, e-commerce expansion, and the DIY home decor movement, which increase accessibility and demand for personalized designs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, ensuring deep validation of market dynamics. We conducted 42 in-depth interviews across the value chain, including raw material suppliers (specialty paper and vinyl producers), specialized wallpaper manufacturers, contract formulators for inks and coatings, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided granular insights into production capacities, pricing strategies, and adoption barriers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 35% |
| Heads of R&D & Technical Directors | 30% |
| Commercial Operations Leads | 25% |
| Sustainability & Regulatory Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Specialty Paper Producers | 40% |
| Wallpaper Manufacturers & Digital Printers | 35% |
| Ink & Coating Formulators | 15% |
| Global Distributors & Retailers | 10% |
We triangulated primary data with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases (USPTO, EPO), and recognized technical standards from industry associations such as the Wallcoverings Association and ASTM International. This ensured alignment with macroeconomic and trade flow trends.
Our market sizing employs simultaneous Top-Down (macroeconomic segmentation and industry allocation) and Bottom-Up (manufacturer capacity, product pricing, end-use consumption) modeling. We cross-validate estimates at regional and segment levels, adjusting for double-counting and scope differences.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2035 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |