Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
AI Code Tools Market: Size, CAGR & 2032 Outlook (2026)
AI Code Tools Market: Size, CAGR & 2032 Outlook (2026)
AI Code Tools Market
AI Code Tools Market: Size, CAGR & 2032 Outlook (2026)
AI Code Tools Market by Deployment Mode (Cloud-based, On-premises), by Tool Functionality (Code Completion, Code Generation, Code Review, Debugging, Documentation), by Technology (Machine Learning, Deep Learning, Natural Language Processing, Generative AI), by Application (Data Science & ML, Cloud Services & DevOps, Web Development, Mobile App Development, Gaming Development, Embedded Systems), by End-User Vertical (IT & Telecom, BFSI, Healthcare & Life Sciences, Manufacturing, Retail & E-commerce, Government, Media & Entertainment), by Organization Size (Large Enterprises, SMEs), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands, Spain), by Asia Pacific (China, Japan, India, South Korea, Indonesia, Malaysia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (UAE, Saudi Arabia, Israel, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 255
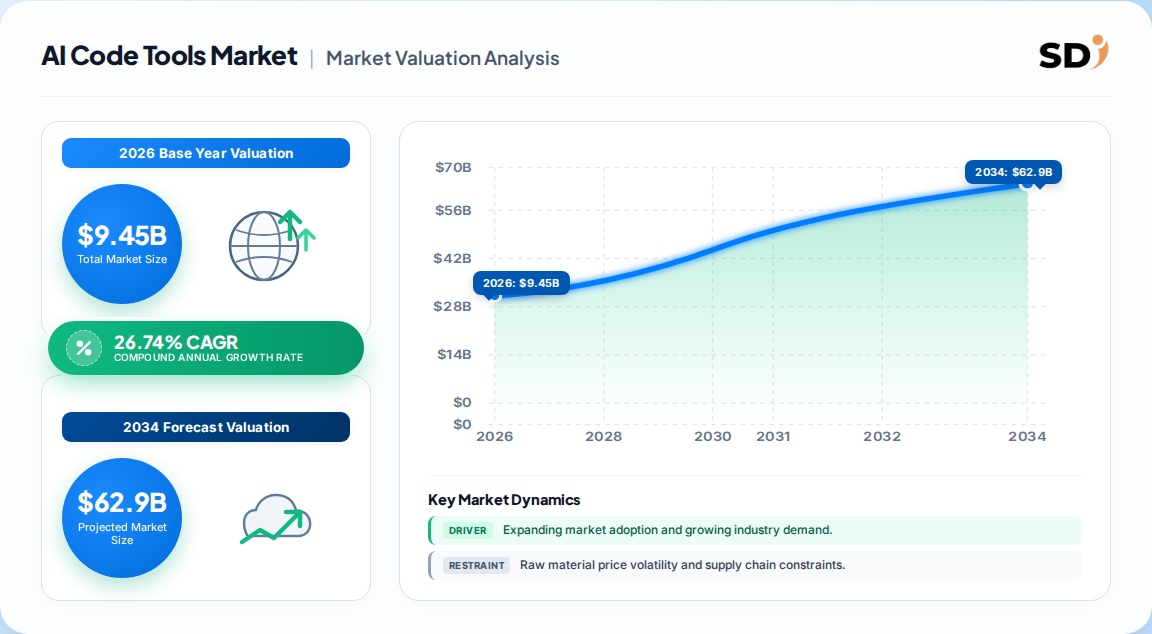
USD 9.45 billion in 2026, global scope — the AI Code Tools Market sits at an inflection point between tooling pilots and enterprise standardization.
26.7% CAGR to 2032, reaching roughly USD 38.59 billion; alternative consensus models land 23.6%–26.05%, all confirming hyper-growth but from different baselines.
Cloud-based deployment holds 72.4% share; on-premises is the fastest deployment mode at 27.05% CAGR, signaling rising IP-control anxiety.
North America leads with ~41.8% of revenue, while Asia-Pacific grows fastest at ~27.2% CAGR on developer-pool scale and digital-transformation spend.
Code completion is the largest functionality (37.96%); code generation (27.5% CAGR) is the fastest and most strategically contested battleground.
Leading vendors: Microsoft/GitHub, Google, OpenAI, AWS, IBM, Meta, Sourcegraph — with medium concentration and rapid bundling-driven share shifts.
Why this matters for decision-makers: Bundled free tiers are commoditizing suggestions, so vendors must pivot toward workflow coverage, governance, and traceability to defend paid seats — and buyers should lock in pricing before consumption-based models reset the economics.
AI Code Tools Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
9.450 B
2026
11.98 B
2027
15.18 B
2028
19.24 B
2029
24.39 B
2030
30.91 B
2031
38.59 B
2032
AI Code Tools Market Size (In Billion)
Year
Market Size
2026
9.450 B
2027
11.98 B
2028
15.18 B
2029
19.24 B
2030
24.39 B
2031
30.91 B
2032
38.59 B
What is the AI Code Tools Market?
The AI Code Tools Market covers software and services that use machine learning, NLP, and generative AI to assist software development — code completion, generation, review, debugging, and documentation — delivered as cloud-based or on-premises tools and professional services across enterprise and SME users.
Scope: what this report covers and excludes
This report covers AI-assisted software development tooling globally: deployment (cloud, on-premises), functionality (completion, generation, review, debugging), technology (ML, NLP, generative AI), applications (DevOps, web, mobile, gaming, embedded), end-user verticals, and organization size. It excludes generic IT outsourcing, traditional non-AI IDEs, AI infrastructure hardware, and pure data-science platforms without coding-assistant capability. Adjacent markets such as autonomous agent platforms and AI project-management tooling are referenced only as context.
How big is the market for AI Code Tools Market?
The global AI Code Tools Market is estimated at USD 9.45 billion in 2026, with forecasts converging on USD 22–39 billion by 2030–2032 at CAGRs between 23.6% and 26.7%. Definitions differ on whether services and consumption revenue are included.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 9.45 Bn → USD 22.06 Bn
2026
2030
23.6%
Tools + services, broad verticals, generative AI included
Offering, technology, application, vertical, region
A third published outlook
Our analysis suggests the 2026 base is unusually tight (USD 9.23–9.45 billion, a 2.4% spread), which raises confidence in the near-term figure. The divergence is entirely in the tail: horizons and service-revenue inclusion drive the USD 22 billion vs. USD 59 billion gap. For procurement and planning, anchor to the 2026 base and treat the CAGR as a 23–27% band, not a point estimate.
How is the market segmented?
The AI Code Tools Market segments along deployment, functionality, technology, application, end-user vertical, and organization size, with cloud-based, code-completion, and IT/telecom dominating current revenue.
Machine learning, Deep learning, NLP, Generative AI
ML largest; generative AI fastest
Application
Data science/ML, Cloud & DevOps, Web, Mobile, Gaming, Embedded
Cloud & DevOps fastest
End-User Vertical
IT & telecom, BFSI, Healthcare, Manufacturing, Retail, Government, Media
IT & telecom 31.81%; healthcare fastest (27.45%)
Organization Size
Large enterprises, SMEs
Large 59.36%; SMEs fastest (27.1%)
The segmentation tells a coherent story: revenue today is concentrated in large enterprises, cloud delivery, and completion-style assistance, while the growth vectors — on-prem, generation, healthcare, SMEs — are exactly where governance and IP concerns bite hardest.
Which regions lead in AI Code Tools Market?
North America leads the AI Code Tools Market with roughly 41.8% of 2026 revenue on U.S. innovation and hyperscaler concentration, while Asia-Pacific is the fastest-growing region at about 27.2% CAGR. Europe holds a governance-driven second position.
AI Code Tools Market Regional Market Share
Loading chart...
AI Code Tools Market Regional Market Share
Region
Market Share (%)
North America
0.42%
Europe
0.25%
Asia-Pacific
0.24%
Latin America
0.05%
Middle East & Africa
0.04%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Netherlands, Spain
Asia-Pacific — China, Japan, India, South Korea, Indonesia, Malaysia
Latin America — Brazil, Argentina, Mexico
Middle East & Africa — UAE, Saudi Arabia, Israel, South Africa
Region
2026 Share
Growth posture
North America
~42%
Largest; enterprise standardization
Europe
~25%
Regulation-led adoption
Asia-Pacific
~24%
Fastest (~27.2% CAGR)
Latin America
~5%
Emerging, price-sensitive
Middle East & Africa
~4%
Sovereign-cloud driven
Our analysis suggests the North America–Asia-Pacific share gap narrows by 2030 as Japan and India enterprise engineering moves from individual seats to organizational contracts.
What is driving growth — and what is holding it back?
Growth is powered by LLM accuracy above 90% on HumanEval, explosive IDE plug-in distribution, generous free tiers, and an expected 75% of enterprise engineers using AI assistants by 2028. Restraints are hallucination risk, IP liability, and GPU/ASIC scarcity.
Factor
Direction
Evidence strength
Mechanism
LLM accuracy >90% HumanEval
Driver (+9.8%)
Strong, benchmark-dated
Makes bounded coding tasks delegable
IDE plug-in adoption (VS Code, JetBrains)
Driver (+8.4%)
Strong, install counts
Distribution carries larger work units
Vendor cloud credits & free tiers
Driver (+6.6%)
Strong, published terms
Lowers trial cost, seeds paid conversion
75% enterprise engineer adoption by 2028
Driver (+5.5%)
Moderate, survey-based
Expands paid seat base
Private/local models for IP control
Driver (+2.7%)
Moderate
Opens sensitive-workload route
IP & copyright liability
Restraint (−2.2%)
Strong, legal precedent
Adds approval and verification work
Hallucination & security bugs
Restraint (−2.7%)
Strong, CVE evidence
Erodes trust in unattended generation
GPU/ASIC shortages for on-prem
Restraint (−1.4%)
Moderate, supply-chain
Caps private-cluster scaling
The balance favors growth decisively, but the restraint profile is instructive: the two strongest brakes are trust-related, not demand-related. That implies the marginal dollar shifts from raw suggestion quality toward verification, traceability, and provenance — the exact areas where free tiers cannot compete.
Who are the leading vendors?
Microsoft/GitHub, Google, OpenAI, AWS, IBM, Meta, and Sourcegraph anchor a medium-concentration market, with Microsoft's 74.78 million VS Code Copilot installs and agent-mode rollout giving it the widest distribution moat.
Vendor
Core strength
Moat
Risk
Microsoft / GitHub
Copilot, VS Code + JetBrains distribution, agent mode
Editor reach + enterprise bundling
Consumption pricing backlash
Google LLC
Gemini Code Assist, cloud integration
GCP ecosystem, model depth
Monetization lag
OpenAI
Codex-class models, API ubiquity
Model quality and developer mindshare
Channel dependence
AWS
Amazon Q Developer, free tier
Cloud lock-in, enterprise contracts
Late editor footprint
IBM
watsonx Code Assistant, regulated industries
Compliance credibility
Perceived innovation gap
Meta Platforms
Code Llama lineage, open weights
Open-source community
Commercial capture
Sourcegraph
Cody, code-graph context
Repository-wide understanding
Scale vs. hyperscalers
Differentiation is migrating from model benchmarks to workflow coverage: how much of a task a plug-in can own, and how well provenance is captured.
What do buyers and operators need to know?
Selection should hinge on three mission-critical criteria: verification and provenance (can the tool prove which code is AI-generated?), data-residency and model-hosting options (cloud, private, or local for IP-sensitive repositories), and total cost under consumption pricing, which can outrun seat licenses at scale. Procurement risk concentrates in renewal clauses and AI-credit pools: unlimited completions are often bundled while chat and agentic requests are metered. Switching costs rise with IDE deep integration and repository context accumulation, so pilots should be time-boxed and export paths contractually guaranteed. Note that 43% of surveyed organizations cannot reliably distinguish AI-generated from human code — a compliance exposure in regulated verticals. Buyers in BFSI and healthcare should require audit trails and indemnification terms before enterprise rollout.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a trust-and-workflow thesis over a pure model-quality thesis. The 2026 base is tightly corroborated, growth is durable, and the strongest restraints are verification-related — meaning the durable margin pool sits in governance, provenance, and private deployment, not in commodity completion. The strongest counter-argument: hyperscaler bundling could compress willingness to pay faster than governance features monetize, especially among SMEs where free tiers suffice. Our view is that bundling wins the seat but not the audit, and regulated buyers will pay separately for assurance.
A second-order effect deserves attention: on-premises is the fastest deployment mode (27.05% CAGR) despite GPU scarcity, which implies buyers will accept hardware friction to keep IP local. Vendors without a credible private-model roadmap will lose sensitive-workload accounts regardless of benchmark leadership.
Actionable strategy:
Vendors: prioritize provenance and audit features to convert free-tier users into governed paid seats before bundling resets pricing.
Operators: negotiate consumption caps and export rights at pilot stage; treat AI-credit pools as the real cost variable.
Investors: weight private-deployment capability and regulated-vertical traction over raw HumanEval scores when assessing durability.
Evidence that would change this conclusion: a sustained plateau in enterprise seat conversion, or regulatory clarity that removes IP-liability friction and unlocks unattended generation at scale.
AI Code Tools Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
AI Code Tools Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 26.74% from 2020-2034
Segmentation
By Deployment Mode
Cloud-based
On-premises
By Tool Functionality
Code Completion
Code Generation
Code Review
Debugging
Documentation
By Technology
Machine Learning
Deep Learning
Natural Language Processing
Generative AI
By Application
Data Science & ML
Cloud Services & DevOps
Web Development
Mobile App Development
Gaming Development
Embedded Systems
By End-User Vertical
IT & Telecom
BFSI
Healthcare & Life Sciences
Manufacturing
Retail & E-commerce
Government
Media & Entertainment
By Organization Size
Large Enterprises
SMEs
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Spain
Asia Pacific
China
Japan
India
South Korea
Indonesia
Malaysia
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
UAE
Saudi Arabia
Israel
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Deployment Mode
5.1.1. Cloud-based
5.1.2. On-premises
5.2. Market Analysis, Insights and Forecast - by Tool Functionality
5.2.1. Code Completion
5.2.2. Code Generation
5.2.3. Code Review
5.2.4. Debugging
5.2.5. Documentation
5.3. Market Analysis, Insights and Forecast - by Technology
5.3.1. Machine Learning
5.3.2. Deep Learning
5.3.3. Natural Language Processing
5.3.4. Generative AI
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Data Science & ML
5.4.2. Cloud Services & DevOps
5.4.3. Web Development
5.4.4. Mobile App Development
5.4.5. Gaming Development
5.4.6. Embedded Systems
5.5. Market Analysis, Insights and Forecast - by End-User Vertical
5.5.1. IT & Telecom
5.5.2. BFSI
5.5.3. Healthcare & Life Sciences
5.5.4. Manufacturing
5.5.5. Retail & E-commerce
5.5.6. Government
5.5.7. Media & Entertainment
5.6. Market Analysis, Insights and Forecast - by Organization Size
5.6.1. Large Enterprises
5.6.2. SMEs
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Deployment Mode
6.1.1. Cloud-based
6.1.2. On-premises
6.2. Market Analysis, Insights and Forecast - by Tool Functionality
6.2.1. Code Completion
6.2.2. Code Generation
6.2.3. Code Review
6.2.4. Debugging
6.2.5. Documentation
6.3. Market Analysis, Insights and Forecast - by Technology
6.3.1. Machine Learning
6.3.2. Deep Learning
6.3.3. Natural Language Processing
6.3.4. Generative AI
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Data Science & ML
6.4.2. Cloud Services & DevOps
6.4.3. Web Development
6.4.4. Mobile App Development
6.4.5. Gaming Development
6.4.6. Embedded Systems
6.5. Market Analysis, Insights and Forecast - by End-User Vertical
6.5.1. IT & Telecom
6.5.2. BFSI
6.5.3. Healthcare & Life Sciences
6.5.4. Manufacturing
6.5.5. Retail & E-commerce
6.5.6. Government
6.5.7. Media & Entertainment
6.6. Market Analysis, Insights and Forecast - by Organization Size
6.6.1. Large Enterprises
6.6.2. SMEs
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Deployment Mode
7.1.1. Cloud-based
7.1.2. On-premises
7.2. Market Analysis, Insights and Forecast - by Tool Functionality
7.2.1. Code Completion
7.2.2. Code Generation
7.2.3. Code Review
7.2.4. Debugging
7.2.5. Documentation
7.3. Market Analysis, Insights and Forecast - by Technology
7.3.1. Machine Learning
7.3.2. Deep Learning
7.3.3. Natural Language Processing
7.3.4. Generative AI
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Data Science & ML
7.4.2. Cloud Services & DevOps
7.4.3. Web Development
7.4.4. Mobile App Development
7.4.5. Gaming Development
7.4.6. Embedded Systems
7.5. Market Analysis, Insights and Forecast - by End-User Vertical
7.5.1. IT & Telecom
7.5.2. BFSI
7.5.3. Healthcare & Life Sciences
7.5.4. Manufacturing
7.5.5. Retail & E-commerce
7.5.6. Government
7.5.7. Media & Entertainment
7.6. Market Analysis, Insights and Forecast - by Organization Size
7.6.1. Large Enterprises
7.6.2. SMEs
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Deployment Mode
8.1.1. Cloud-based
8.1.2. On-premises
8.2. Market Analysis, Insights and Forecast - by Tool Functionality
8.2.1. Code Completion
8.2.2. Code Generation
8.2.3. Code Review
8.2.4. Debugging
8.2.5. Documentation
8.3. Market Analysis, Insights and Forecast - by Technology
8.3.1. Machine Learning
8.3.2. Deep Learning
8.3.3. Natural Language Processing
8.3.4. Generative AI
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Data Science & ML
8.4.2. Cloud Services & DevOps
8.4.3. Web Development
8.4.4. Mobile App Development
8.4.5. Gaming Development
8.4.6. Embedded Systems
8.5. Market Analysis, Insights and Forecast - by End-User Vertical
8.5.1. IT & Telecom
8.5.2. BFSI
8.5.3. Healthcare & Life Sciences
8.5.4. Manufacturing
8.5.5. Retail & E-commerce
8.5.6. Government
8.5.7. Media & Entertainment
8.6. Market Analysis, Insights and Forecast - by Organization Size
8.6.1. Large Enterprises
8.6.2. SMEs
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Deployment Mode
9.1.1. Cloud-based
9.1.2. On-premises
9.2. Market Analysis, Insights and Forecast - by Tool Functionality
9.2.1. Code Completion
9.2.2. Code Generation
9.2.3. Code Review
9.2.4. Debugging
9.2.5. Documentation
9.3. Market Analysis, Insights and Forecast - by Technology
9.3.1. Machine Learning
9.3.2. Deep Learning
9.3.3. Natural Language Processing
9.3.4. Generative AI
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Data Science & ML
9.4.2. Cloud Services & DevOps
9.4.3. Web Development
9.4.4. Mobile App Development
9.4.5. Gaming Development
9.4.6. Embedded Systems
9.5. Market Analysis, Insights and Forecast - by End-User Vertical
9.5.1. IT & Telecom
9.5.2. BFSI
9.5.3. Healthcare & Life Sciences
9.5.4. Manufacturing
9.5.5. Retail & E-commerce
9.5.6. Government
9.5.7. Media & Entertainment
9.6. Market Analysis, Insights and Forecast - by Organization Size
9.6.1. Large Enterprises
9.6.2. SMEs
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Deployment Mode
10.1.1. Cloud-based
10.1.2. On-premises
10.2. Market Analysis, Insights and Forecast - by Tool Functionality
10.2.1. Code Completion
10.2.2. Code Generation
10.2.3. Code Review
10.2.4. Debugging
10.2.5. Documentation
10.3. Market Analysis, Insights and Forecast - by Technology
10.3.1. Machine Learning
10.3.2. Deep Learning
10.3.3. Natural Language Processing
10.3.4. Generative AI
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Data Science & ML
10.4.2. Cloud Services & DevOps
10.4.3. Web Development
10.4.4. Mobile App Development
10.4.5. Gaming Development
10.4.6. Embedded Systems
10.5. Market Analysis, Insights and Forecast - by End-User Vertical
10.5.1. IT & Telecom
10.5.2. BFSI
10.5.3. Healthcare & Life Sciences
10.5.4. Manufacturing
10.5.5. Retail & E-commerce
10.5.6. Government
10.5.7. Media & Entertainment
10.6. Market Analysis, Insights and Forecast - by Organization Size
10.6.1. Large Enterprises
10.6.2. SMEs
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: AI Code Tools Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America AI Code Tools Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 3: North America AI Code Tools Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 4: North America AI Code Tools Market Revenue (Billion), by Tool Functionality 2026 & 2034
Figure 5: North America AI Code Tools Market Revenue Share (%), by Tool Functionality 2026 & 2034
Figure 6: North America AI Code Tools Market Revenue (Billion), by Technology 2026 & 2034
Figure 7: North America AI Code Tools Market Revenue Share (%), by Technology 2026 & 2034
Figure 8: North America AI Code Tools Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America AI Code Tools Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America AI Code Tools Market Revenue (Billion), by End-User Vertical 2026 & 2034
Figure 11: North America AI Code Tools Market Revenue Share (%), by End-User Vertical 2026 & 2034
Figure 12: North America AI Code Tools Market Revenue (Billion), by Organization Size 2026 & 2034
Figure 13: North America AI Code Tools Market Revenue Share (%), by Organization Size 2026 & 2034
Figure 14: North America AI Code Tools Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America AI Code Tools Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe AI Code Tools Market Revenue (Billion), by Deployment Mode 2026 & 2034
List of Tables
Table 1: AI Code Tools Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 2: AI Code Tools Market Revenue Billion Forecast, by Tool Functionality 2020 & 2034
Table 3: AI Code Tools Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 4: AI Code Tools Market Revenue Billion Forecast, by Application 2020 & 2034
Table 5: AI Code Tools Market Revenue Billion Forecast, by End-User Vertical 2020 & 2034
Table 6: AI Code Tools Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 7: AI Code Tools Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America AI Code Tools Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 9: North America AI Code Tools Market Revenue Billion Forecast, by Tool Functionality 2020 & 2034
Table 10: North America AI Code Tools Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 11: North America AI Code Tools Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: North America AI Code Tools Market Revenue Billion Forecast, by End-User Vertical 2020 & 2034
Table 13: North America AI Code Tools Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 14: North America AI Code Tools Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How large is the AI Code Tools Market in 2026?
USD 9.45 billion globally, with competing estimates clustering between USD 9.23 and 9.45 billion. The tight base-year range reflects broad agreement on current adoption; divergence appears mainly in long-horizon forecasts.
2. What is the AI Code Tools Market CAGR?
Roughly 23.6% to 26.7% depending on horizon and scope. The most defensible planning band is 24–27%, with 26.7% used for the 2032 forecast to USD 38.59 billion.
3. Which region leads AI Code Tools adoption?
North America leads with about 41.8% of 2026 revenue, driven by U.S. innovation and hyperscaler concentration. Asia-Pacific is the fastest-growing region at approximately 27.2% CAGR.
4. Who are the leading AI Code Tools vendors?
Microsoft/GitHub, Google, OpenAI, AWS, IBM, Meta, and Sourcegraph. Microsoft holds the widest distribution moat through VS Code and Copilot installs.
5. Which segment grows fastest?
Code generation (27.5% CAGR) and on-premises deployment (27.05% CAGR), with healthcare and SMEs the fastest-growing vertical and organization-size segments respectively.
6. What limits AI Code Tools adoption?
Hallucination and security-bug risk (−2.7%) and IP/copyright liability (−2.2%) are the strongest brakes, followed by GPU/ASIC shortages for private clusters (−1.4%).
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. Structured interviews and in-depth briefings were conducted across the value chain with AI tooling vendors, model providers and API suppliers, IDE and DevOps platform integrators, enterprise software buyers, and managed service providers. Within these organizations we engaged decision-makers including VP of Engineering, Heads of Developer Platform, Chief Information Security Officers, Procurement and Vendor Management Leads, and Commercial Operations Directors. Interview evidence was weighted toward observed contract structures, seat-conversion behavior, and governance requirements.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Engineering & Developer Platform Heads
38%
Procurement & Vendor Management Leads
27%
CISO & Security Architecture Leads
20%
Commercial Operations Directors
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
AI Tooling Vendors & Model Providers
40%
IDE & DevOps Platform Integrators
25%
Enterprise Software Buyers
22%
Managed & Professional Services
13%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on official multilateral and regulatory databases including UN Comtrade, WTO digital-services data, US ITC reports, Eurostat ICT statistics, corporate annual filings (10-K and SEC disclosures), investor presentations, patent databases, and recognized technical standards bodies and non-profit associations such as ISO/IEC software-engineering standards and IEEE technical publications. No third-party market-research publications were used as validation sources.
Demand Modeling & Market Sizing Triangulation
Market sizing triangulates a top-down allocation (macroeconomic software spend, developer populations, and vertical IT budgets) against a bottom-up model (vendor revenue, seat counts, consumption pricing, and end-use coding-hour consumption). The two views are reconciled to a single base-year value with a documented variance band.
Data Triangulation & Validation Matrix
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
Sources Referenced
UN Comtrade — cross-border ICT and digitally delivered services trade data
US ITC — software and digital services trade reporting
Eurostat — enterprise ICT adoption and digital-intensity statistics
ISO/IEC JTC 1 — software and systems engineering standards (e.g., ISO/IEC 12207, 25010)
IEEE Computer Society — software engineering technical literature and benchmarks
Figure 17: Europe AI Code Tools Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 18: Europe AI Code Tools Market Revenue (Billion), by Tool Functionality 2026 & 2034
Figure 19: Europe AI Code Tools Market Revenue Share (%), by Tool Functionality 2026 & 2034
Figure 20: Europe AI Code Tools Market Revenue (Billion), by Technology 2026 & 2034
Figure 21: Europe AI Code Tools Market Revenue Share (%), by Technology 2026 & 2034
Figure 22: Europe AI Code Tools Market Revenue (Billion), by Application 2026 & 2034
Figure 23: Europe AI Code Tools Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe AI Code Tools Market Revenue (Billion), by End-User Vertical 2026 & 2034
Figure 25: Europe AI Code Tools Market Revenue Share (%), by End-User Vertical 2026 & 2034
Figure 26: Europe AI Code Tools Market Revenue (Billion), by Organization Size 2026 & 2034
Figure 27: Europe AI Code Tools Market Revenue Share (%), by Organization Size 2026 & 2034
Figure 28: Europe AI Code Tools Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe AI Code Tools Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia Pacific AI Code Tools Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 31: Asia Pacific AI Code Tools Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 32: Asia Pacific AI Code Tools Market Revenue (Billion), by Tool Functionality 2026 & 2034
Figure 33: Asia Pacific AI Code Tools Market Revenue Share (%), by Tool Functionality 2026 & 2034
Figure 34: Asia Pacific AI Code Tools Market Revenue (Billion), by Technology 2026 & 2034
Figure 35: Asia Pacific AI Code Tools Market Revenue Share (%), by Technology 2026 & 2034
Figure 36: Asia Pacific AI Code Tools Market Revenue (Billion), by Application 2026 & 2034
Figure 37: Asia Pacific AI Code Tools Market Revenue Share (%), by Application 2026 & 2034
Figure 38: Asia Pacific AI Code Tools Market Revenue (Billion), by End-User Vertical 2026 & 2034
Figure 39: Asia Pacific AI Code Tools Market Revenue Share (%), by End-User Vertical 2026 & 2034
Figure 40: Asia Pacific AI Code Tools Market Revenue (Billion), by Organization Size 2026 & 2034
Figure 41: Asia Pacific AI Code Tools Market Revenue Share (%), by Organization Size 2026 & 2034
Figure 42: Asia Pacific AI Code Tools Market Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia Pacific AI Code Tools Market Revenue Share (%), by Country 2026 & 2034
Figure 44: Latin America AI Code Tools Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 45: Latin America AI Code Tools Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 46: Latin America AI Code Tools Market Revenue (Billion), by Tool Functionality 2026 & 2034
Figure 47: Latin America AI Code Tools Market Revenue Share (%), by Tool Functionality 2026 & 2034
Figure 48: Latin America AI Code Tools Market Revenue (Billion), by Technology 2026 & 2034
Figure 49: Latin America AI Code Tools Market Revenue Share (%), by Technology 2026 & 2034
Figure 50: Latin America AI Code Tools Market Revenue (Billion), by Application 2026 & 2034
Figure 51: Latin America AI Code Tools Market Revenue Share (%), by Application 2026 & 2034
Figure 52: Latin America AI Code Tools Market Revenue (Billion), by End-User Vertical 2026 & 2034
Figure 53: Latin America AI Code Tools Market Revenue Share (%), by End-User Vertical 2026 & 2034
Figure 54: Latin America AI Code Tools Market Revenue (Billion), by Organization Size 2026 & 2034
Figure 55: Latin America AI Code Tools Market Revenue Share (%), by Organization Size 2026 & 2034
Figure 56: Latin America AI Code Tools Market Revenue (Billion), by Country 2026 & 2034
Figure 57: Latin America AI Code Tools Market Revenue Share (%), by Country 2026 & 2034
Figure 58: Middle East & Africa AI Code Tools Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 59: Middle East & Africa AI Code Tools Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 60: Middle East & Africa AI Code Tools Market Revenue (Billion), by Tool Functionality 2026 & 2034
Figure 61: Middle East & Africa AI Code Tools Market Revenue Share (%), by Tool Functionality 2026 & 2034
Figure 62: Middle East & Africa AI Code Tools Market Revenue (Billion), by Technology 2026 & 2034
Figure 63: Middle East & Africa AI Code Tools Market Revenue Share (%), by Technology 2026 & 2034
Figure 64: Middle East & Africa AI Code Tools Market Revenue (Billion), by Application 2026 & 2034
Figure 65: Middle East & Africa AI Code Tools Market Revenue Share (%), by Application 2026 & 2034
Figure 66: Middle East & Africa AI Code Tools Market Revenue (Billion), by End-User Vertical 2026 & 2034
Figure 67: Middle East & Africa AI Code Tools Market Revenue Share (%), by End-User Vertical 2026 & 2034
Figure 68: Middle East & Africa AI Code Tools Market Revenue (Billion), by Organization Size 2026 & 2034
Figure 69: Middle East & Africa AI Code Tools Market Revenue Share (%), by Organization Size 2026 & 2034
Figure 70: Middle East & Africa AI Code Tools Market Revenue (Billion), by Country 2026 & 2034
Figure 71: Middle East & Africa AI Code Tools Market Revenue Share (%), by Country 2026 & 2034
Table 17: Mexico AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Europe AI Code Tools Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 19: Europe AI Code Tools Market Revenue Billion Forecast, by Tool Functionality 2020 & 2034
Table 20: Europe AI Code Tools Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 21: Europe AI Code Tools Market Revenue Billion Forecast, by Application 2020 & 2034
Table 22: Europe AI Code Tools Market Revenue Billion Forecast, by End-User Vertical 2020 & 2034
Table 23: Europe AI Code Tools Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 24: Europe AI Code Tools Market Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Germany AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: UK AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: France AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Italy AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Netherlands AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Spain AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Asia Pacific AI Code Tools Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 32: Asia Pacific AI Code Tools Market Revenue Billion Forecast, by Tool Functionality 2020 & 2034
Table 33: Asia Pacific AI Code Tools Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 34: Asia Pacific AI Code Tools Market Revenue Billion Forecast, by Application 2020 & 2034
Table 35: Asia Pacific AI Code Tools Market Revenue Billion Forecast, by End-User Vertical 2020 & 2034
Table 36: Asia Pacific AI Code Tools Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 37: Asia Pacific AI Code Tools Market Revenue Billion Forecast, by Country 2020 & 2034
Table 38: China AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Japan AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: India AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: South Korea AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: Indonesia AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: Malaysia AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: Latin America AI Code Tools Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 45: Latin America AI Code Tools Market Revenue Billion Forecast, by Tool Functionality 2020 & 2034
Table 46: Latin America AI Code Tools Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 47: Latin America AI Code Tools Market Revenue Billion Forecast, by Application 2020 & 2034
Table 48: Latin America AI Code Tools Market Revenue Billion Forecast, by End-User Vertical 2020 & 2034
Table 49: Latin America AI Code Tools Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 50: Latin America AI Code Tools Market Revenue Billion Forecast, by Country 2020 & 2034
Table 51: Brazil AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Argentina AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: Mexico AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 54: Middle East & Africa AI Code Tools Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 55: Middle East & Africa AI Code Tools Market Revenue Billion Forecast, by Tool Functionality 2020 & 2034
Table 56: Middle East & Africa AI Code Tools Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 57: Middle East & Africa AI Code Tools Market Revenue Billion Forecast, by Application 2020 & 2034
Table 58: Middle East & Africa AI Code Tools Market Revenue Billion Forecast, by End-User Vertical 2020 & 2034
Table 59: Middle East & Africa AI Code Tools Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 60: Middle East & Africa AI Code Tools Market Revenue Billion Forecast, by Country 2020 & 2034
Table 61: UAE AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 62: Saudi Arabia AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 63: Israel AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 64: South Africa AI Code Tools Market Revenue (Billion) Forecast, by Application 2020 & 2034


 AI Code Tools Market