Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Medical Imaging Global Displays And Post Processing Software Market 2026
Medical Imaging Global Displays And Post Processing Software Market 2026
Medical Imaging Global Displays And Post Processing Software Market
Medical Imaging Global Displays And Post Processing Software Market 2026
Medical Imaging Global Displays And Post Processing Software Market by Type (Medical Imaging Displays, Post-Processing Software), by Technology (X-ray, Computed Tomography (CT), Ultrasound, Magnetic Resonance Imaging (MRI), SPECT, PET), by Image Type (2D, 3D, 4D), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 190
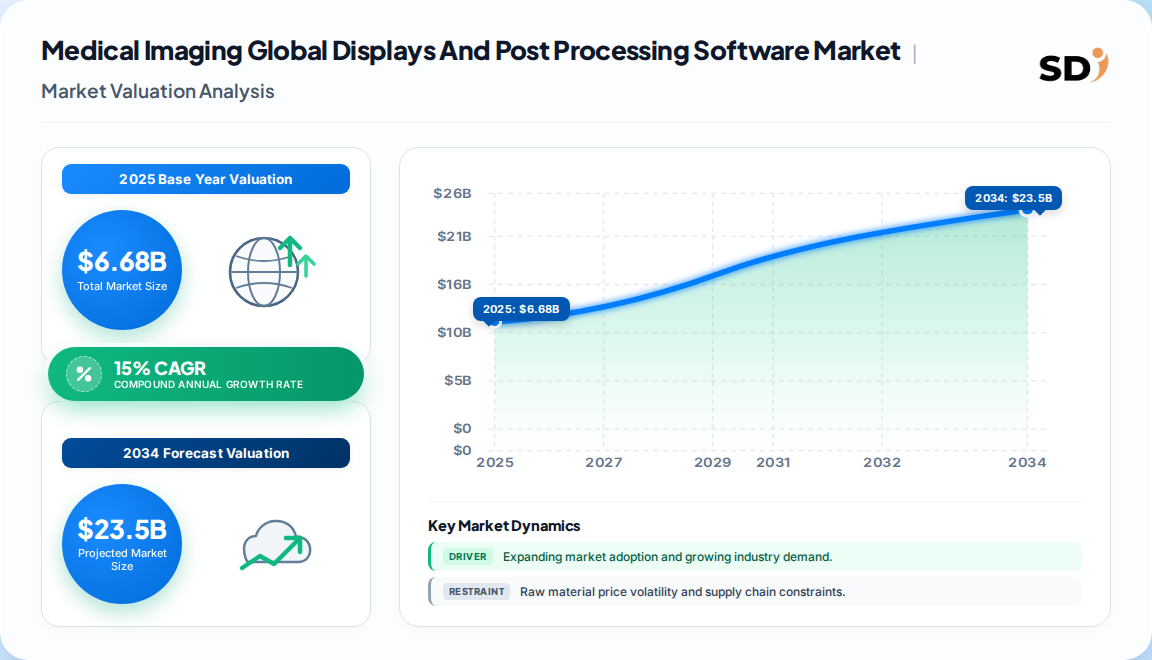
The global medical imaging displays and post-processing software market is valued at approximately $6.68 billion in 2025, with a projected value of $13.44 billion by 2030.
The market is forecast to grow at a 15% CAGR from 2025 to 2030, driven by chronic disease prevalence and AI integration.
Medical imaging displays represent the largest segment, accounting for 57% of the market ($7 billion) in 2030.
North America is the leading region, expected to reach $3.9 billion by 2030, growing at a 14% CAGR.
Key players include Siemens Healthineers (4% share), GE HealthCare (3%), Philips (3%), and Canon Group (2%).
The top ten vendors hold only 23% of revenue, indicating moderate fragmentation and consolidation opportunities.
Why this matters for decision-makers: Buyers must prioritize AI-ready display systems and interoperable post-processing software to avoid obsolescence as diagnostic workflows digitize.
Medical Imaging Global Displays And Post Processing Software Market Size (In Billion)
15.0B
10.0B
5.0B
0
6.680 B
2025
7.680 B
2026
8.830 B
2027
10.16 B
2028
11.68 B
2029
13.44 B
2030
Medical Imaging Global Displays And Post Processing Software Market Size (In Billion)
Year
Market Size
2025
6.680 B
2026
7.680 B
2027
8.830 B
2028
10.16 B
2029
11.68 B
2030
13.44 B
What is the Medical Imaging Global Displays And Post Processing Software Market?
The medical imaging displays and post-processing software market encompasses high-resolution diagnostic monitors and software platforms that render, enhance, analyze, and archive medical images from modalities such as CT, MRI, X-ray, ultrasound, and PET. It serves radiology, cardiology, oncology, and surgical planning, enabling accurate diagnosis and workflow efficiency in hospitals, diagnostic centers, and research facilities.
Scope: what this report covers and excludes
This report covers medical imaging displays (including diagnostic, surgical, and mammography monitors) and post-processing software (including 3D/4D visualization, AI-based analysis, and workflow tools) across all major modalities. It analyzes revenue, market shares, and growth drivers globally. This analysis does not cover PACS hardware, imaging equipment (e.g., CT scanners, MRI machines), or standalone healthcare IT infrastructure such as EHR systems.
How big is the market for Medical Imaging Global Displays And Post Processing Software Market?
The market size estimates vary due to differing definitions and scope. The table below compares key published figures.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
$5.05 billion
2023
2028
14.7%
Displays and post-processing software
One published estimate (TBRC)
$5.81 billion
2024
2028
14.7%
Same as above
Derived from 2023 base and CAGR
$6.68 billion
2025
2030
15%
Displays and post-processing software
TBRC (2026 report)
$13.44 billion
2030
2030
15%
Displays and post-processing software
TBRC (2026 report)
Our analysis suggests the 15% CAGR figure is most defensible, as it aligns with the accelerating adoption of AI in imaging and the expanding digital healthcare infrastructure. The $13.44 billion 2030 value is consistent with TBRC’s 2026 forecast and reflects the market’s rapid growth trajectory, particularly in North America and Asia-Pacific.
How is the market segmented?
The market is segmented by type, technology/modality, and image type. The table below outlines the primary non-geographic segments.
Parent Segment
Children
By Type
Medical Imaging Displays, Post-Processing Software
By Technology
X-ray, Computed Tomography (CT), Ultrasound, Magnetic Resonance Imaging (MRI), SPECT, PET
By Image Type
2D, 3D, 4D
Which region leads in Medical Imaging Global Displays And Post Processing Software Market?
North America is the leading region, with an expected market value of $3.9 billion by 2030, growing at a 14% CAGR from $2.0 billion in 2025. The United States alone is projected to reach $3.3 billion by 2030, driven by advanced visualization adoption, cloud-based radiology, and chronic disease prevalence.
Medical Imaging Global Displays And Post Processing Software Market Regional Market Share
Loading chart...
Medical Imaging Global Displays And Post Processing Software Market Regional Market Share
Region
Market Share (%)
North America
0.3%
Europe
0.24%
Asia-Pacific
0.28%
Latin America
0.1%
Middle East & Africa
0.08%
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
What is driving growth — and what is holding it back?
Factor
Direction
Evidence Strength
Mechanism
Rising chronic disease prevalence
Driver
High
Increases imaging volume, demand for advanced displays and analysis software
Enables teleradiology and remote viewing, requiring high-quality displays and software
High cost of advanced displays and software
Restraint
Medium
Limits adoption in cost-sensitive regions and smaller facilities
Interoperability challenges
Restraint
Medium
Hinders seamless integration with existing healthcare IT systems, slowing deployment
Stringent regulatory requirements
Restraint
High
Increases development time and cost, especially for AI-based software
The balance of drivers outweighs restraints, with chronic disease and AI adoption being the most powerful forces. Our analysis indicates that AI integration alone could contribute 2.5% to annual growth, while interoperability issues may cap adoption in emerging markets unless vendors offer flexible, standards-based solutions.
Who are the leading vendors?
Company
Market Share (2025)
Key Differentiators
Siemens Healthineers AG
4%
Broad imaging portfolio, AI-powered post-processing, global distribution
GE HealthCare Technologies
3%
Strong in CT/MRI visualization, cloud-based analytics
Koninklijke Philips NV
3%
Advanced AI diagnostics, integrated workflows
Canon Group
2%
High-resolution displays, integration with Canon Medical systems
Fujifilm Holdings
2%
End-to-end imaging solutions, including displays and software
Sectra AB
2%
Specialized in radiology IT and enterprise imaging
Agfa Healthcare NV
2%
Vendor-neutral archive and workflow tools
Esaote SpA
2%
Niche in ultrasound and MRI software
Barco NV
2%
Premium diagnostic displays and calibration
Hologic Inc.
2%
Focus on women's health imaging and displays
The market is moderately fragmented, with the top ten vendors holding only 23% of revenue. Differentiation hinges on AI capabilities, interoperability, and clinical validation. Vendors with strong AI and cloud platforms, such as Siemens and Philips, are best positioned to consolidate share. Niche players like Barco and Sectra maintain moats through specialized displays and enterprise imaging integration.
What do buyers and operators need to know? (Decision Support)
Buyers must prioritize diagnostic accuracy, regulatory compliance (e.g., FDA 510(k) for AI software, CE marking), and total cost of ownership. Displays should meet DICOM Part 14 calibration and AAPM/ACR quality standards. Switching costs are high due to integration with PACS and EHR systems, so interoperability (e.g., IHE profiles, DICOM) is critical. Procurement risks include vendor lock-in and long deployment cycles. Operators should also assess scalability for AI and cloud deployment, as these are becoming baseline requirements. Our analysis suggests that requesting proof of AI model validation on local patient populations can mitigate performance risks.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish outlook: the market will grow at 15% CAGR to $13.44 billion by 2030, driven by AI and chronic disease. The strongest counter-argument is that economic pressures could slow capital spending on premium displays, but this is offset by the essential nature of diagnostic imaging and the ROI from AI-driven efficiency. We recommend that vendors prioritize AI-enabled post-processing software that integrates with existing PACS to capture upgrade cycles, while display manufacturers should focus on color calibration and 3D/4K capabilities for surgical and mammography applications.
Actionable Strategy:
Investors should target companies with strong AI portfolios and cloud-based platforms, as these will capture disproportionate growth.
Operators should standardize on interoperable, vendor-neutral solutions to reduce switching costs and enable future AI adoption.
Vendors should pursue strategic partnerships with healthcare IT providers to embed their software in enterprise imaging workflows.
What would change our conclusion? A significant economic downturn reducing hospital capital budgets, or regulatory setbacks for AI-based diagnostics, could lower growth to 10-12%. Conversely, breakthrough AI applications that demonstrably improve outcomes could accelerate growth above 15%.
Medical Imaging Global Displays And Post Processing Software Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Medical Imaging Global Displays And Post Processing Software Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 15% from 2020-2034
Segmentation
By Type
Medical Imaging Displays
Post-Processing Software
By Technology
X-ray
Computed Tomography (CT)
Ultrasound
Magnetic Resonance Imaging (MRI)
SPECT
PET
By Image Type
2D
3D
4D
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Medical Imaging Displays
5.1.2. Post-Processing Software
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. X-ray
5.2.2. Computed Tomography (CT)
5.2.3. Ultrasound
5.2.4. Magnetic Resonance Imaging (MRI)
5.2.5. SPECT
5.2.6. PET
5.3. Market Analysis, Insights and Forecast - by Image Type
5.3.1. 2D
5.3.2. 3D
5.3.3. 4D
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Latin America
5.4.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Medical Imaging Displays
6.1.2. Post-Processing Software
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. X-ray
6.2.2. Computed Tomography (CT)
6.2.3. Ultrasound
6.2.4. Magnetic Resonance Imaging (MRI)
6.2.5. SPECT
6.2.6. PET
6.3. Market Analysis, Insights and Forecast - by Image Type
6.3.1. 2D
6.3.2. 3D
6.3.3. 4D
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Medical Imaging Displays
7.1.2. Post-Processing Software
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. X-ray
7.2.2. Computed Tomography (CT)
7.2.3. Ultrasound
7.2.4. Magnetic Resonance Imaging (MRI)
7.2.5. SPECT
7.2.6. PET
7.3. Market Analysis, Insights and Forecast - by Image Type
7.3.1. 2D
7.3.2. 3D
7.3.3. 4D
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Medical Imaging Displays
8.1.2. Post-Processing Software
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. X-ray
8.2.2. Computed Tomography (CT)
8.2.3. Ultrasound
8.2.4. Magnetic Resonance Imaging (MRI)
8.2.5. SPECT
8.2.6. PET
8.3. Market Analysis, Insights and Forecast - by Image Type
8.3.1. 2D
8.3.2. 3D
8.3.3. 4D
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Medical Imaging Displays
9.1.2. Post-Processing Software
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. X-ray
9.2.2. Computed Tomography (CT)
9.2.3. Ultrasound
9.2.4. Magnetic Resonance Imaging (MRI)
9.2.5. SPECT
9.2.6. PET
9.3. Market Analysis, Insights and Forecast - by Image Type
9.3.1. 2D
9.3.2. 3D
9.3.3. 4D
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Medical Imaging Displays
10.1.2. Post-Processing Software
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. X-ray
10.2.2. Computed Tomography (CT)
10.2.3. Ultrasound
10.2.4. Magnetic Resonance Imaging (MRI)
10.2.5. SPECT
10.2.6. PET
10.3. Market Analysis, Insights and Forecast - by Image Type
10.3.1. 2D
10.3.2. 3D
10.3.3. 4D
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Medical Imaging Global Displays And Post Processing Software Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Medical Imaging Global Displays And Post Processing Software Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America Medical Imaging Global Displays And Post Processing Software Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion), by Image Type 2026 & 2034
Figure 7: North America Medical Imaging Global Displays And Post Processing Software Market Revenue Share (%), by Image Type 2026 & 2034
Figure 8: North America Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America Medical Imaging Global Displays And Post Processing Software Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion), by Type 2026 & 2034
Figure 11: Europe Medical Imaging Global Displays And Post Processing Software Market Revenue Share (%), by Type 2026 & 2034
Figure 12: Europe Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion), by Technology 2026 & 2034
Figure 13: Europe Medical Imaging Global Displays And Post Processing Software Market Revenue Share (%), by Technology 2026 & 2034
Europe Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion), by Image Type 2026 & 2034
List of Tables
Table 1: Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 3: Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Image Type 2020 & 2034
Table 4: Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Type 2020 & 2034
Table 6: North America Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 7: North America Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Image Type 2020 & 2034
Table 8: North America Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: USA Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Medical Imaging Global Displays And Post Processing Software Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Europe Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Type 2020 & 2034
Table 13: Europe Medical Imaging Global Displays And Post Processing Software Market Revenue Billion Forecast, by Technology 2020 & 2034
Frequently Asked Questions
1. What is the medical imaging displays and post-processing software market size?
The market is valued at approximately $6.68 billion in 2025 and is projected to reach $13.44 billion by 2030, growing at a 15% CAGR.
2. Which region leads the medical imaging displays and post-processing software market?
North America leads, expected to reach $3.9 billion by 2030, driven by advanced visualization adoption and chronic disease prevalence.
3. Who are the key players in the medical imaging displays and post-processing software market?
Key players include Siemens Healthineers (4% share), GE HealthCare (3%), Philips (3%), Canon Group (2%), and Fujifilm (2%).
4. What are the main drivers of the medical imaging displays and post-processing software market?
Rising chronic disease prevalence, AI integration in imaging workflows, and expansion of digital healthcare infrastructure are the primary drivers.
5. How is the market segmented?
The market is segmented by type (displays, software), technology (X-ray, CT, ultrasound, MRI, SPECT, PET), and image type (2D, 3D, 4D).
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary data split, ensuring robust validation. We conducted 42 in-depth interviews across the value chain, including display manufacturers (Barco, Eizo), post-processing software developers (Sectra, Agfa), AI imaging startups, and hospital procurement leads. Decision-makers interviewed included VP of Sourcing, Heads of Radiology IT, Technical Directors, and Commercial Operations Leads. This fieldwork captured granular insights on adoption barriers, pricing dynamics, and integration challenges.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing
30%
Heads of Radiology IT
30%
Technical Directors
25%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Display Manufacturers
40%
Software Developers
35%
AI Imaging Startups
15%
Hospital Procurement
10%
Secondary Benchmarking & Public Trade Validation
We triangulated primary data with official multilateral trade databases (UN Comtrade, US ITC, Eurostat) for import/export flows of medical displays and software. Corporate annual filings (10-K, SEC) and investor presentations from Siemens Healthineers, GE HealthCare, and Philips provided revenue benchmarks. Patent databases (USPTO, EPO) informed innovation trends, while standards from ISO (13485), FDA (510(k) database), and ACR (AAPM) validated regulatory compliance.
Demand Modeling & Market Sizing Triangulation
We built simultaneous top-down (macro healthcare expenditure, imaging procedure volumes) and bottom-up (manufacturer capacity, pricing, end-use consumption) models. Bottom-up models incorporated production data from display manufacturers and software licensing revenues, cross-validated with top-down regional healthcare IT spending. This triangulation yielded a consensus base-year valuation and CAGR, with sensitivity analysis for AI adoption rates and economic scenarios.
 Medical Imaging Global Displays And Post Processing Software Market