 The Global Supply Chain Analytics Market
: 2026-2035 Outlook
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 247

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 The Global Supply Chain Analytics Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 11.00 B |
| 2026 | 12.70 B |
| 2027 | 14.70 B |
| 2028 | 17.00 B |
| 2029 | 19.70 B |
| 2030 | 22.80 B |
| 2031 | 26.40 B |

The global supply chain analytics market comprises software, services and cloud platforms that apply descriptive, predictive and prescriptive analytics to procurement, inventory, logistics, manufacturing and sustainability data — enabling enterprises to forecast demand, optimize networks, mitigate risk and satisfy regulatory reporting with auditable, multi-tier visibility.
This analysis covers analytics software and associated professional and managed services applied to supply chain planning, execution visibility, inventory, transportation, procurement and ESG/carbon accounting across all major end-use verticals and regions. Revenue definitions follow vendor-level software and services spend unless otherwise attributed. This analysis does not cover adjacent markets such as warehouse automation hardware, pure ERP transaction systems, freight forwarding services, or standalone IoT sensor hardware — each of which is examined only as an input or adjacency.
Estimates converge on a 2026 base of USD 12–14 billion, growing at roughly 16% annually. The variation between published figures is driven principally by scope definitions — whether services, embedded ERP analytics and ESG modules are included — rather than by disagreement on underlying demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 12.7 billion | 2026 | 2034 | 15.85% | Software + services, all verticals | One published estimate |
| USD 14.18 billion | 2026 | 2035 | 16.61% | Broader solution + service scope | A competing analysis |
| USD 11.60 billion | 2026 | 2035 | 15.8% | Software-led, services secondary | Another published estimate |
| USD 6.12 billion | 2022 | 2030 | 17.8% | Narrower historical base, earlier vintage | An earlier third-party estimate |
Our analysis suggests the USD 12.7–14.2 billion range for 2026 is the most defensible, because it reconciles vendor-reported software revenue with services attach rates. The lower 2022-base figures reflect an earlier vintage and narrower scope; the 15.8–16.6% CAGR band is the consensus signal buyers should plan against. The divergence implies that procurement teams must normalize vendor claims to a common scope before comparing TCO.
Segmentation matters because growth is uneven: software and cloud carry the base, while services and sustainability analytics carry the incremental margin and fastest expansion through 2035.
| Parent segment | Children |
|---|---|
| Component | Software, Services (professional, managed) |
| Deployment | Cloud, On-premise |
| Analytics type | Descriptive, Predictive, Prescriptive |
| Application | Inventory management, Transportation & logistics, Procurement & sourcing, Sustainability analytics |
| End-use industry | Retail & e-commerce, Manufacturing, Healthcare & life sciences, Automotive, Others |
| Enterprise size | Large enterprises, SMEs |
Inventory management captured roughly 30% of 2025 revenue, anchored by safety-stock optimization and demand sensing. Sales & operations analytics leads in some taxonomies at 26–28%. Professional services hold about 60% of the services pool, but support and managed services are growing fastest as platforms shift to subscription models.
North America leads with 37–44% of global revenue, Europe follows at roughly 25%, and Asia-Pacific is the fastest-growing region at a 22%+ CAGR. Regional leadership reflects both SaaS ecosystem maturity and the timing of ESG disclosure mandates.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.25% |
| Asia-Pacific | 0.24% |
| South America | 0.05% |
| Middle East & Africa | 0.07% |
| Region | 2025 share (indicative) |
|---|---|
| North America | 39–44% |
| Europe | 25% |
| Asia-Pacific | 24% (fastest CAGR) |
| Middle East & Africa | 5–7% |
| South America | 4–5% |
The North American lead is structural, not cyclical: established SaaS procurement cycles and early Scope 3 reporting pressure create durable demand. Europe's CSRD mandate — requiring roughly 50,000 companies to report granular Scope 3 emissions — is a compliance-driven floor under analytics spend. Asia-Pacific's 22.8% projected CAGR reflects smart-factory investment in China and India exceeding USD 45 billion since 2021, generating telemetry streams that require real-time analytics.
Growth is driven by AI-enabled planning, cloud migration and ESG compliance, while data integration complexity, talent scarcity and data-sovereignty rules cap the pace of adoption. Net momentum remains strongly positive, but execution friction disproportionately penalizes mid-market buyers.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Gen-AI copilots & autonomous planning | Driver (~22% of CAGR) | High | Natural-language scenario planning cuts cycle time up to 60% |
| Cloud-native migration | Driver (~18%) | High | 25–35% TCO reduction; >70% of new deployments cloud-first |
| Scope 3 / ESG mandates | Driver (~16%) | High | CSRD and SEC rules demand auditable tier-2/3 supplier data |
| APAC manufacturing digitization | Driver (~14%) | Medium-High | Smart-factory telemetry requires real-time yield and maintenance analytics |
| Data integration complexity | Restraint (~−6%) | Medium | Fragmented ERP and supplier systems delay time-to-value |
| Analytics talent scarcity | Restraint | Medium | Data-scientist shortages raise services dependence and cost |
| Data privacy & sovereignty rules | Restraint | Medium | Cross-border data flow restrictions complicate global deployments |
The balance favors acceleration: drivers sum to materially more CAGR impact than restraints, and regulatory deadlines are non-negotiable. The second-order effect our analysis emphasizes is that integration and talent friction push spend toward managed services and vertical SaaS templates — which is precisely where SME adoption will be won or lost.
The vendor landscape is consolidating around platforms that combine planning depth, network design and AI interfaces, with specialists defending niches in visibility and risk analytics.
| Vendor | Primary strength | Strategic positioning |
|---|---|---|
| SAP SE | ERP-native planning and analytics | Deep installed base; copilot-led expansion |
| Oracle Corporation | Cloud SCM and analytics suite | Integrated cloud stack and data platform |
| Blue Yonder | AI-driven planning and execution | Strong retail and logistics footprint |
| Kinaxis Inc. | Concurrent planning platform | Differentiated multi-echelon planning engine |
| SAS Institute | Advanced analytics and forecasting | Statistical depth; regulated industries |
| IBM Corporation | Hybrid cloud and AI (watsonx) | Enterprise integration and governance |
Differentiation is shifting from dashboard breadth to decision velocity: how fast a platform converts supplier, IoT and regulatory data into an optimized action. Moats are built on ERP integration depth, proprietary network-design algorithms and — increasingly — certified ESG data pipelines. Our analysis suggests vendors without credible Scope 3 modules will face pricing pressure in Europe by 2027.
Selection should hinge on four mission-critical criteria: proven integration with the existing ERP and supplier ecosystem, auditable ESG data lineage, total cost of ownership under subscription pricing, and the depth of the vendor's AI planning capabilities beyond interface novelty.
Procurement risk concentrates in implementation, not licensing. Integration complexity can extend time-to-value by several quarters and is the leading cause of failed deployments, so buyers should contract for outcome-based milestones and reference-check multi-tier supplier onboarding. Switching costs are high once planning workflows and supplier data models are embedded, making the initial platform choice semi-permanent — a reason to prioritize composability and open APIs over feature checklists. Regulatory compliance is now a purchasing criterion in its own right: CSRD-aligned Scope 3 reporting requires automated tier-2 and tier-3 data ingestion that legacy batch-planning tools cannot deliver. Operators should assume a 25–35% TCO advantage for cloud-native deployments and model services attach rates of 25–40% of software spend over the contract life.
The balance of evidence favors a mid-teens growth market through 2035, with the upside case anchored in AI-driven planning adoption and mandatory ESG reporting rather than in cyclical IT budgets. The strongest counter-argument is that data integration complexity and talent scarcity could suppress realized value and slow renewal expansion — a risk that is real but concentrated in mid-market accounts rather than large enterprises. Our judgment is that the market will grow toward the upper end of consensus because regulatory deadlines are non-discretionary and AI copilots materially lower the skill floor for adoption.
The conclusion would change if Scope 3 enforcement were materially delayed across both the EU and US, or if integration costs proved structurally uncompressible — either would push realized growth toward the lower end of the 15–17% band and favor services-heavy business models over pure software.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with enterprise supply chain leaders, analytics software vendors, systems integrators, logistics service providers and industry consultants. Decision-maker designations interviewed include Chief Supply Chain Officers, VP of Planning and Analytics, Heads of Procurement and Sourcing, and IT/Enterprise Architecture Directors.
Secondary validation draws on official multilateral and national statistical sources — UN Comtrade, WTO trade statistics, US International Trade Commission data and Eurostat — alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases and recognized non-profit industry and standards bodies. All third-party estimates are normalized to a common scope before triangulation.
Simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (vendor revenue, subscription pricing and end-use consumption modeling) triangulation is applied. Historical validation uses enterprise software revenue disclosures and technology spending databases; forecasts are stress-tested against GDP growth, trade-flow volatility and technology investment indexes.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 15.8% from 2020-2034 |
| Segmentation |
|
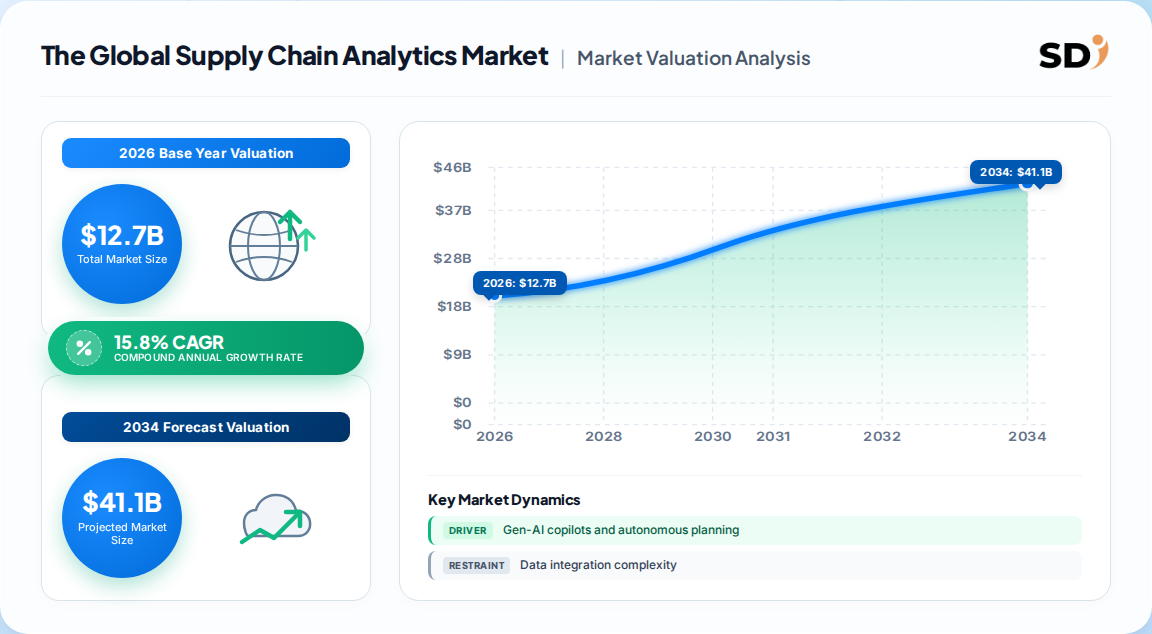
The global supply chain analytics market is estimated at approximately USD 12.7 billion in 2026, up from USD 11.0 billion in 2025. Published estimates range from USD 11.6 to 14.2 billion depending on whether services and embedded ESG modules are included in scope.
Forecasts cluster between a 15.8% and 16.6% CAGR through the mid-2030s, implying a market of USD 41–56 billion by 2034–2035. Consensus growth is anchored in AI-enabled planning, cloud migration and mandatory ESG reporting.
North America leads with roughly 37–44% of global revenue, supported by mature SaaS ecosystems and early Scope 3 reporting pressure. Asia-Pacific is the fastest-growing region at a 22%+ CAGR, driven by manufacturing digitization in China and India.
Leading vendors include SAP SE, Oracle Corporation, Blue Yonder, Kinaxis Inc., SAS Institute and IBM Corporation. Differentiation is shifting toward AI copilots, multi-echelon planning depth and certified Scope 3 ESG data pipelines.
Gen-AI copilots and autonomous planning contribute roughly 22% of growth momentum, cloud-native migration about 18%, and Scope 3/ESG reporting mandates about 16%. Cloud deployment now accounts for over 70% of new planning installations.
Data integration complexity, analytics talent scarcity and data-sovereignty regulations restrain adoption. Integration friction can extend time-to-value by several quarters and disproportionately affects mid-market buyers, pushing spend toward managed services.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with enterprise supply chain leaders, analytics software vendors, systems integrators, logistics service providers and industry consultants. Decision-maker designations interviewed include Chief Supply Chain Officers, VP of Planning and Analytics, Heads of Procurement and Sourcing, and IT/Enterprise Architecture Directors.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Supply Chain Officers | 35% |
| VP Planning & Analytics | 30% |
| Procurement & Sourcing Heads | 20% |
| IT / Enterprise Architecture Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Analytics Software Vendors | 40% |
| Systems Integrators & Consultancies | 30% |
| Enterprise End-Users | 20% |
| Logistics Service Providers | 10% |
Secondary validation draws on official multilateral and national statistical sources — UN Comtrade, WTO trade statistics, US International Trade Commission data and Eurostat — alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases and recognized non-profit industry and standards bodies. All third-party estimates are normalized to a common scope before triangulation.
Simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (vendor revenue, subscription pricing and end-use consumption modeling) triangulation is applied. Historical validation uses enterprise software revenue disclosures and technology spending databases; forecasts are stress-tested against GDP growth, trade-flow volatility and technology investment indexes.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |