 Sovereign Cloud Market
 Size, Growth & Outlook 2026-2032
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 233

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Sovereign Cloud Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 129.0 B |
| 2026 | 156.0 B |
| 2027 | 193.7 B |
| 2028 | 240.5 B |
| 2029 | 298.7 B |
| 2030 | 370.9 B |
| 2031 | 460.6 B |

The sovereign cloud market encompasses cloud infrastructure and services where data, operations, technology stacks, and governance remain under a defined national or regional jurisdiction. It guarantees legal and operational control beyond physical data residency, ensuring compliance with local laws and resilience against geopolitical and extraterritorial access risks.
This report covers sovereign cloud infrastructure, platform, and software services across data, operational, and technical sovereignty types, deployed via cloud and on-premises models into government, BFSI, healthcare, telecom, energy, and manufacturing verticals worldwide. This analysis does not cover adjacent categories such as general-purpose public cloud, traditional colocation, or non-sovereign managed hosting.
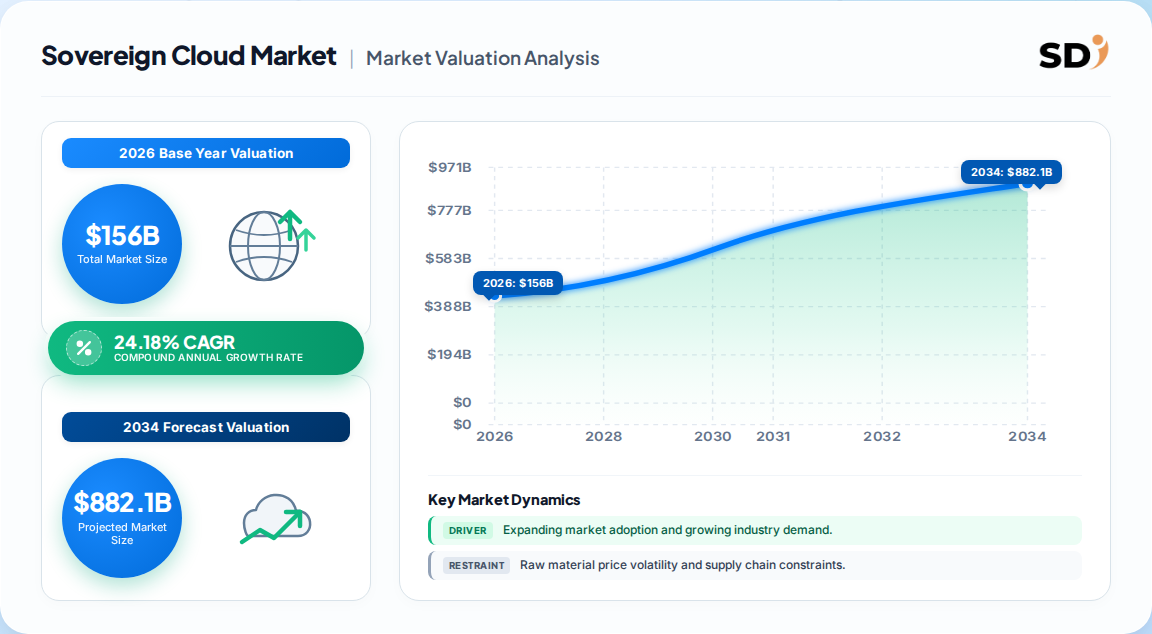
The sovereign cloud market is estimated between USD 143 Billion and USD 156 Billion in 2026, with forecasts converging on a 24% CAGR through 2033. Divergence reflects differing treatment of on-premises sovereign stacks and nationalized IaaS.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 156 Billion | 2026 | 2032 (USD 572B) | 24.18% | Full stack incl. on-prem sovereign | Aggregated industry content (Doc 3) |
| USD 143.3 Billion | 2026 | 2033 (USD 648.9B) | 24.1% | Cloud-centric sovereign deployments | Competing published analysis (GVR-style) |
| USD 139.27 Billion | 2026 | 2035 (USD 651.43B) | 18.70% | Public + private sovereign cloud only | Alternate published estimate |
Our analysis suggests the USD 156 Billion figure is most defensible for 2026 because it captures on-premises sovereign infrastructure, which Gartner-sized spending data (USD 80.4B in 2026) confirms is material. The lower CAGRs (18.7%) reflect longer horizons and dilutive base effects, not weaker demand.
The market segments along sovereignty type, deployment model, enterprise size, and end-use vertical, with data sovereignty dominating spend at roughly 60% of infrastructure value.
| Parent Segment | Children |
|---|---|
| Sovereignty Type | Data Sovereignty, Operational Sovereignty, Technical Sovereignty |
| Deployment Model | Cloud (Public, Private, Hybrid), On-Premises |
| Enterprise Size | Large Enterprises, SMEs |
| End-Use Industry | Government & Defense, BFSI, Healthcare & Life Sciences, Telecommunications, Energy & Utilities, Manufacturing, Others |
Actual segmentation data implies that IaaS remains the anchor service (~46% of service-type spend), while PaaS is the fastest-growing layer at ~20% CAGR as sovereign AI workloads mature. SMEs, though only ~29% of 2026 spend, will grow faster than large enterprises as compliance obligations cascade down supply chains.
North America leads the sovereign cloud market with approximately 44% share in 2026, though Asia-Pacific posts the fastest CAGR as China, India, and Japan institutionalize data localization.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.28% |
| Asia-Pacific | 0.24% |
| Latin America | 0.05% |
| Middle East & Africa | 0.05% |
Europe's share understates its strategic weight: EU Data Act, NIS2, DORA, and the Gaia-X framework are exporting compliance norms globally. Our analysis suggests China's USD 47.4B sovereign IaaS figure is the single most underappreciated data point, signaling a bifurcated global market where Western hyperscalers face structural exclusion.
Regulatory mandates (GDPR, NIS2, DORA, India DPDP, EU Data Act) and national digital sovereignty strategies are the primary growth engines, while limited advanced service portfolios and high deployment costs constrain velocity.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Data localization regulations | Driver | High | Forces jurisdictional data control, expands addressable spend |
| National digital sovereignty initiatives | Driver | High | Government-led procurement and infrastructure investment |
| Sovereign AI infrastructure demand | Driver | Medium-High | GPU clusters, national LLMs require sovereign compute |
| Limited advanced service portfolios | Restraint | Medium | Narrower catalog vs hyperscalers delays adoption |
| High deployment costs | Restraint | Medium | Capex intensity for localized data centers |
| Vendor lock-in concerns | Restraint | Medium | Multicloud/portability requirements slow commitment |
The balance of evidence favors accelerating demand: Gartner's 35.6% year-over-year infrastructure spending growth in 2026 outpaces most enterprise software categories. The restraint that matters most is not cost but capability — sovereign environments often lag hyperscaler GenAI tooling by 12-24 months. Buyers must weigh compliance certainty against innovation velocity.
The market is highly fragmented: top-five vendors hold only ~28% combined share, with hyperscalers, EU sovereign specialists, telcos, and government-backed providers competing on jurisdictional trust.
| Vendor | Positioning | Sovereign Differentiator |
|---|---|---|
| Microsoft | Hyperscale + sovereignty services (Kyndryl partnership) | Broad enterprise footprint, sovereign controls |
| AWS | European Sovereign Cloud (Brandenburg, ~USD 8.91B) | Independent EU governance, EU-resident operations |
| Google Cloud | Multicloud-friendly, EU data transfer fee removal | Portability and open ecosystem |
| Oracle | Sovereign regions for government/defense | Dedicated regions and classified workloads |
| IBM | Hybrid cloud + sovereign consulting | Regulated industry depth |
| OVHcloud / STACKIT | EU-native sovereign providers | Jurisdictional purity, local governance |
| ESDS (Swaraj Cloud) | India sovereign AI platform | Domestic AI sovereign positioning |
Differentiation hinges on jurisdictional guarantees, not feature parity. Hyperscalers win on capability breadth; regional specialists win on trust and legal insulation. Our analysis suggests partnerships (e.g., Kyndryl-Microsoft) are the pragmatic bridge, letting buyers combine hyperscale innovation with sovereign governance — but they introduce operational complexity that pure-play sovereign providers avoid.
Buyers must evaluate sovereign cloud on four mission-critical criteria: jurisdictional guarantee (legal, not just physical, data control), operational transparency (who can access systems and under what law), service parity (AI/analytics availability), and exit economics (data portability and switching costs). Procurement risk concentrates in vendor legal structure — a hyperscaler subsidiary may still be subject to extraterritorial law (e.g., US CLOUD Act). Operators should insist on contractual sovereignty attestations, independent audit rights, and clear data residency SLAs. Switching costs are high once workloads and AI models are embedded, so initial selection is a multi-year strategic decision. Regulatory compliance (NIS2, DORA, sector mandates) should be validated against the provider's certifications, not marketing claims.
The balance of evidence favors a bifurcated market: hyperscalers will capture the majority of sovereign spend through dedicated regions and partnerships, while EU and national champions defend high-trust, high-regulation segments. The strongest counter-argument is that sovereign cloud is a compliance niche that hyperscalers will absorb once regulations stabilize — but Gartner's projection that 80% of sovereign spend funds new workloads, not migration, undercuts this view.
Our analysis suggests the "sovereignty premium" is durable because it is rooted in geopolitics, not technology cycles. The most underestimated risk is service-parity lag: buyers who choose pure-play sovereign providers may sacrifice 12-24 months of AI capability. The most underestimated opportunity is sovereign AI infrastructure — national GPU clusters and LLMs will drive the next investment wave through 2030.
Evidence that would change our conclusion: sustained hyperscaler service parity in sovereign regions and regulatory harmonization (e.g., mutual recognition of EU-US sovereignty frameworks) would compress the pure-play sovereign premium and favor consolidated hyperscale capture.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 24.18% from 2020-2034 |
| Segmentation |
|
The sovereign cloud market is estimated at USD 156 Billion in 2026, with forecasts ranging from USD 139 Billion to USD 156 Billion depending on whether on-premises sovereign infrastructure is included. It is projected to reach USD 572 Billion by 2032.
The market is forecast to grow at a 24.18% CAGR from 2026 to 2032. More conservative longer-horizon estimates place CAGR near 18.7%, reflecting different base-year and scope assumptions rather than weaker underlying demand.
North America leads with approximately 44% of 2026 revenue, driven by US government and defense demand. Asia-Pacific is the fastest-growing region, with China alone representing USD 47.4 Billion in sovereign IaaS spending in 2026.
Data localization regulations (GDPR, NIS2, DORA, India DPDP Act), national digital sovereignty strategies, and sovereign AI infrastructure demand are the primary drivers. Government and defense accounts for roughly 35% of end-user spending.
Microsoft, AWS, Google Cloud, Oracle, IBM, OVHcloud, STACKIT, and ESDS lead the fragmented market, where the top five vendors hold only about 28% combined share, leaving significant room for regional specialists.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split, anchored in structured interviews with stakeholders across the sovereign cloud value chain: hyperscale and regional cloud operators, sovereign infrastructure specialists, systems integrators, and government/regulated-enterprise procurement teams. We conducted in-depth interviews with decision-makers including Chief Information Security Officers, Heads of Cloud Infrastructure, Procurement Directors, and Compliance & Data Protection Leads, capturing procurement criteria, governance requirements, and deployment timelines.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CISOs & Cloud Infrastructure Heads | 38% |
| Procurement Directors | 27% |
| Compliance & Data Protection Leads | 22% |
| Government IT Policy Officials | 13% |
| Company Type | Representation (%) |
|---|---|
| Hyperscale & Regional Cloud Operators | 40% |
| Sovereign Infrastructure Specialists | 30% |
| Systems Integrators & MSPs | 20% |
| Government & Regulated Procurement Teams | 10% |
We triangulate against official multilateral and standards sources: UN Comtrade and WTO services trade statistics, Eurostat digital economy indicators, national statistical agencies (e.g., US BEA, India MeitY), corporate annual filings (10-K, SEC, annual investor presentations), patent databases, and recognized standards bodies including ISO/IEC 27001, ENISA, and the European Data Protection Board.
We run simultaneous Top-Down (macroeconomic and end-use segment allocation) and Bottom-Up (operator capacity, pricing, and consumption modeling) triangulation, reconciling sovereign infrastructure spend with jurisdiction-level procurement volumes to produce base-year and forecast values.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up operator revenue & capacity triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border data flow & procurement analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |