 Agentic AI Governance Policy Management Market
 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 252


Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Agentic AI Governance Policy Management Market
Srinwanti Kar
Senior Research Analyst

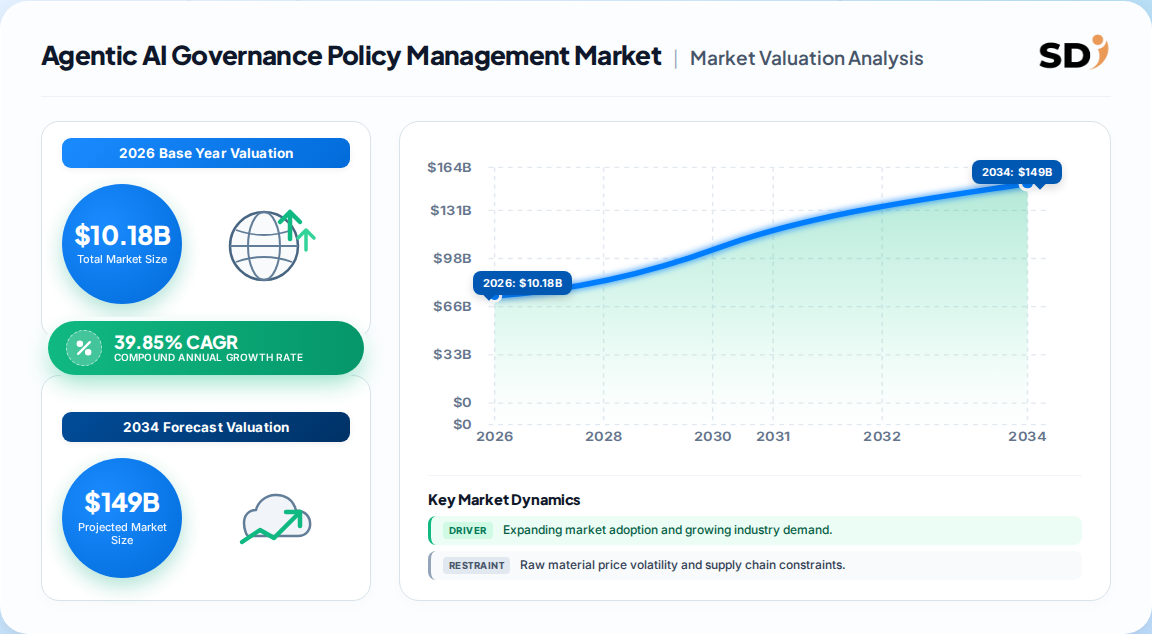
| Year | Market Size |
|---|---|
| 2026 | 10.18 B |
| 2027 | 14.24 B |
| 2028 | 19.91 B |
| 2029 | 27.85 B |
| 2030 | 38.95 B |
| 2031 | 54.46 B |

The Agentic AI Governance Policy Management Market covers software platforms and professional services that define, enforce, monitor, and audit rules governing autonomous AI agents. It spans policy authoring, bias and fairness monitoring, explainability, security, risk and incident management, and drift monitoring across cloud, hybrid, and on-premises deployments in regulated and commercial industries.
This report covers global software platforms and services for agentic AI policy management, bias monitoring, explainability, security, risk, and drift control across BFSI, healthcare, retail, manufacturing, media, IT, and government. It segments by component, governance function, deployment mode, organization size, end-use industry, and geography. This analysis does not cover foundational model training, general AI observability without policy enforcement, traditional GRC suites lacking agent-level controls, or AI hardware markets.
Competing published estimates converge on a base-year value near 10 Billion with CAGR in the high-30s, but forecast endpoints diverge sharply because definitions of "agentic governance" differ. The table below compares the available estimates and their scope assumptions.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 10.18 Billion | 2026 | 2031 (54.46 Billion) | 39.85% | Full policy lifecycle: platform plus services, all industries | One published estimate |
| 13.8 Billion | 2026 | 2035 (247.24 Billion) | 37.80% | Broad agentic governance including deployment services | A competing analysis |
| 7.3 Billion | 2025 | 2035 (203.20 Billion) | 39.50% | Platform-centric governance, software-weighted | A competing analysis |
| 7.4 Billion | 2026 | 2035 (141.30 Billion) | 38.80% | Governance platforms and managed governance services | A competing analysis |
Our analysis suggests the 10.18 Billion to 54.46 Billion series is the most defensible near-term figure because it ties base-year value to a five-year window, reducing compounding error over a decade. The 2035 endpoints ranging from 141.3 to 247.2 Billion reflect definitional inflation: broader scopes absorb adjacent observability and GRC spend. Buyers should treat the five-year number as the procurement-planning anchor and the long-horizon figures as directional.
Segmentation follows five non-geographic axes. Software platforms dominate today, but services and hybrid deployment are where marginal growth concentrates as agent estates sprawl.
| Parent segment | Children | 2025 share / growth |
|---|---|---|
| Component | Platform/Software, Services | Platform 70.80% share; Services 42.20% CAGR |
| Governance function | Policy Management & Compliance, Bias & Fairness Monitoring, Explainability & Transparency, Security & Privacy, Risk & Incident Management, Performance & Drift Monitoring | Policy 27.50% share; Bias 41.71% CAGR |
| Deployment mode | Cloud, Hybrid, On-Premises | Cloud 65.20% share; Hybrid 42.50% CAGR |
| Organization size | Large Enterprises, SMEs | Large 68.10% share; SMEs 41.83% CAGR |
| End-use industry | BFSI, Healthcare & Life Sciences, Retail & E-Commerce, Manufacturing, Media & Entertainment, IT & Telecom, Government | BFSI 25.40% share; Healthcare 43.20% CAGR |
The pattern is consistent: established categories hold revenue while emerging ones hold velocity. That divergence implies buyers should contract on platform breadth today but negotiate expansion clauses for bias, drift, and hybrid capabilities.
North America leads with roughly 38% of global revenue in 2025, driven by early EU-aligned enforcement, mature cloud estates, and the largest concentration of platform vendors. Asia-Pacific is the fastest-growing region at a 41.55% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.27% |
| Asia-Pacific | 0.24% |
| South America | 0.05% |
| Middle East & Africa | 0.06% |
The geography tree shows where enforcement intensity, not population, determines spend. Our analysis suggests Europe may outgrow its current share in policy-specific functions because the EU AI Act's 7% turnover penalty ceiling creates mandatory rather than discretionary demand.
Regulation and penalty escalation are the dominant demand drivers, while ROI ambiguity and skills scarcity are the binding constraints. The table below weighs each factor.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Intensifying global AI-risk regulations | Driver | High (~12.5% CAGR impact) | EU AI Act, China framework, Japan sector rules force cross-border policy harmonization |
| Rising compliance penalties for opaque AI | Driver | High (~8.2% CAGR impact) | Fines up to 7% of turnover convert governance into mandatory spend |
| Governance inside MLOps toolchains | Driver | Medium (~7.8% CAGR impact) | Policy-as-code blocks violations pre-release, shortening release cycles |
| Policy engines embedded in foundation models | Driver | Medium (~6.1% CAGR impact) | In-model safeguards lower enforcement latency and deepen vendor lock-in |
| Poor ROI visibility for stand-alone tools | Restraint | High (~-6.8% CAGR impact) | Only 24% of firms fully enforce AI policies; boards see cost, not growth |
| Responsible-AI skills scarcity | Restraint | Medium (~-5.2% CAGR impact) | Deployment and tuning capacity lags platform purchases |
| Fragmented jurisdictional standards | Restraint | Medium (~-4.1% CAGR impact) | Multinationals maintain duplicate control libraries |
Our analysis suggests the balance favors growth decisively: regulatory drivers are non-discretionary, while restraints are execution problems that services revenue is positioned to absorb. The skills gap, in particular, is a commercial opportunity for managed governance rather than a ceiling on platform demand.
IBM, Microsoft, Alphabet (Google), Amazon (AWS), and SAS Institute anchor a medium-concentration field. Differentiation rests on regulatory mapping breadth, MLOps integration depth, and hybrid-cloud portability rather than raw model capability.
| Vendor | Primary governance positioning | Notable strength |
|---|---|---|
| IBM | Policy, bias, drift within hybrid cloud stack | Regulatory mappings and enterprise software installed base |
| Microsoft | Cloud-native governance and identity integration | Azure scale and enterprise distribution |
| Alphabet (Google) | Model-adjacent controls and early-blocking guidance | Foundation-model integration and developer tooling |
| Amazon (AWS) | Cloud governance services attached to agent workloads | Elastic scale and broad customer base |
| SAS Institute | Analytics-led risk and model governance | Statistical rigor and regulated-industry trust |
The competitive moat is increasingly the control library and audit trail, not the model. Our analysis suggests vendors embedding machine-readable safeguards directly into model and agent layers will capture disproportionate share, but that same integration raises switching costs buyers must price into contracts.
Selection should be driven by five mission-critical criteria: breadth of pre-mapped regulatory controls, native MLOps and pipeline hooks, agent inventory and decommissioning capability, audit-ready evidence generation, and hybrid portability. Procurement risk concentrates in lock-in and scope creep.
Evidence from industry surveys is sobering. Only about 21% of organizations report a mature agentic governance model, while 82% have discovered previously unknown AI agents and 65% experienced an agent-related incident. Formal decommissioning processes exist at just 21% of firms. These figures imply that buyers are purchasing into an immature operating environment where vendor onboarding services matter as much as software features.
Switching costs rise sharply once policy libraries and audit histories accumulate. Negotiate data portability, exportable control mappings, and exit assistance upfront. For regulated buyers, verify that vendor controls map to EU AI Act tiers and recognized risk frameworks before signing, and require contractual commitments on regulatory-change alerting cadence.
The balance of evidence favors buyers who move now on policy-management foundations while deferring long-horizon commitments. Regulatory enforcement is the strongest signal in the dataset: the EU AI Act's 7% turnover ceiling, US healthcare transparency certification, and UK audit scrutiny create non-discretionary demand that will not soften with economic cycles. The strongest counter-argument is ROI ambiguity, supported by the finding that only 24% of firms fully enforce AI policies. That is a real friction, but it reflects immature measurement practices rather than absence of value, and it argues for phased deployment rather than delay.
Our analysis suggests a second-order effect that the headline CAGR obscures: as policy engines embed into foundation models, the governance layer risks being absorbed by model vendors. Independent platform vendors must therefore compete on multi-vendor, multi-jurisdiction control breadth and evidence portability, not on proximity to a single model. Buyers should weight vendor neutrality heavily when agent estates will span multiple providers.
The conclusion would change if EU enforcement were materially delayed or if survey evidence showed enforcement maturity rising above roughly 50%, which would compress discretionary services demand faster than current forecasts assume.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the agentic governance value chain: AI platform software vendors, cloud infrastructure providers, managed governance and consulting firms, regulated end-user enterprises, and systems integrators. Decision-maker designations interviewed included Chief AI Officers, Heads of Model Risk and Compliance, Chief Information Security Officers, and VP-level procurement and vendor-management leads. Interview programs were structured to capture both buying criteria and deployment outcomes across BFSI, healthcare, and public-sector contexts.
Secondary validation drew on official multilateral and regulatory databases, including UN Comtrade and WTO trade statistics for AI-related hardware flows, US SEC 10-K filings and annual investor presentations from leading platform vendors, patent databases for governance and guardrail technology, and recognized standards bodies including NIST and ISO/IEC JTC 1 for AI risk-management frameworks. Corporate filings were used to size vendor exposure to governance-adjacent software and services revenue.
Market sizing triangulates top-down and bottom-up approaches simultaneously. The top-down model allocates macroeconomic and industry-segment spend to governance functions using regulatory intensity and cloud adoption as weights. The bottom-up model builds from vendor capacity, license and services pricing, and end-use consumption by regulated industry. Divergence between the two is reconciled through demand-elasticity adjustment around regulatory timelines.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 39.85% from 2020-2034 |
| Segmentation |
|
The market is valued at approximately 10.18 Billion in 2026 and is forecast to reach 54.46 Billion by 2031, growing at a 39.85% CAGR. North America leads with roughly 38% share, while Asia-Pacific is the fastest-growing region.
Policy Management and Compliance is the largest function at about 27.5% of 2025 revenue. Bias and Fairness Monitoring is the fastest-growing function at a 41.71% CAGR through 2031, reflecting rising regulatory scrutiny of model fairness.
Long-horizon estimates range from about 141 to 247 Billion because definitions differ. Broader scopes absorb adjacent observability and traditional GRC spend, while narrower platform-only definitions grow more slowly. The five-year forecast is the more defensible planning anchor.
Switching costs and lock-in are the primary risks. Once policy libraries and audit histories accumulate, migration becomes expensive. Buyers should negotiate data portability, exportable control mappings, and exit assistance before signing enterprise agreements.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the agentic governance value chain: AI platform software vendors, cloud infrastructure providers, managed governance and consulting firms, regulated end-user enterprises, and systems integrators. Decision-maker designations interviewed included Chief AI Officers, Heads of Model Risk and Compliance, Chief Information Security Officers, and VP-level procurement and vendor-management leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief AI Officers | 30% |
| Model Risk & Compliance Heads | 30% |
| Chief Information Security Officers | 20% |
| Procurement & Vendor Management Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| AI Platform & Software Vendors | 40% |
| Cloud Infrastructure Providers | 25% |
| Managed Governance & Consulting Firms | 20% |
| Regulated End-User Enterprises | 15% |
Secondary validation drew on official multilateral and regulatory databases, including UN Comtrade and WTO trade statistics for AI-related hardware flows, US SEC 10-K filings and annual investor presentations from leading platform vendors, patent databases for governance and guardrail technology, and recognized standards bodies including NIST and ISO/IEC JTC 1 for AI risk-management frameworks.
Market sizing triangulates top-down and bottom-up approaches simultaneously. The top-down model allocates macroeconomic and industry-segment spend to governance functions using regulatory intensity and cloud adoption as weights. The bottom-up model builds from vendor capacity, license and services pricing, and end-use consumption by regulated industry. Divergence between the two is reconciled through demand-elasticity adjustment around regulatory timelines.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |