Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Finance Cloud Market by Offering (Solutions, Services), by Deployment Model (Public Cloud, Private Cloud, Hybrid / Multi-Cloud), by Organization Size (Large Enterprises, SMEs), by Application (Revenue Management, Wealth Management, Customer Management, Account Management, Risk & Compliance, Asset Management), by End-User (Banks, Financial Service Providers, Insurance, Capital Markets, FinTech / Neo-banks), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 239
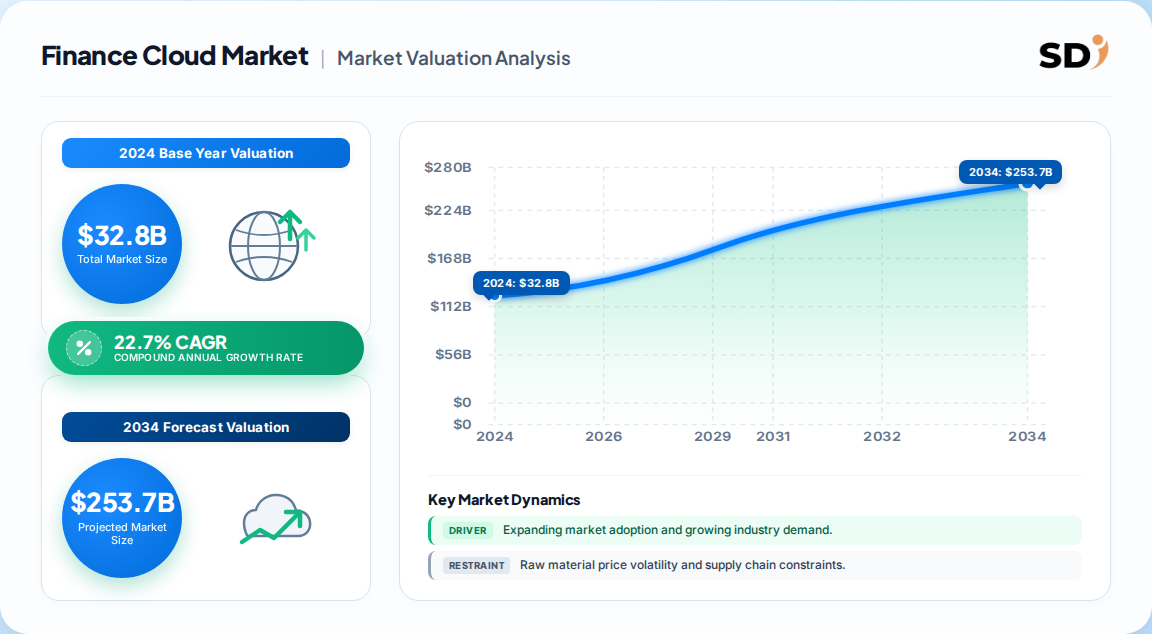
USD 32.8 billion was the global finance cloud market size in 2024, with a forecast of USD 240.4 billion by 2034.
22.7% CAGR is the consensus growth rate for 2025–2034, though competing analyses range from 15.3% to 22.7% depending on scope.
Services dominated with 60% share in 2024, while public cloud led deployment at roughly 57% of revenue.
Large enterprises captured about 70% of spend; SMEs are the fastest-growing size tier at ~17% CAGR.
North America leads with ~40% of global revenue; Asia-Pacific is the fastest-growing region at ~16–18% CAGR.
Key players include AWS, Microsoft, Google, IBM, Oracle, SAP, Salesforce, Workday, Infosys, TCS and Wipro.
Why this matters for decision-makers: The growth premium is shifting from infrastructure to AI-enabled compliance and analytics layers — vendors that cannot embed RegTech and GenAI into finance workflows will face margin compression as services commoditize.
Finance Cloud Market Size (In Billion)
150.0B
100.0B
50.0B
0
32.80 B
2024
40.20 B
2025
49.40 B
2026
60.60 B
2027
74.40 B
2028
91.30 B
2029
112.0 B
2030
Finance Cloud Market Size (In Billion)
Year
Market Size
2024
32.80 B
2025
40.20 B
2026
49.40 B
2027
60.60 B
2028
74.40 B
2029
91.30 B
2030
112.0 B
What is the Finance Cloud Market?
The finance cloud market covers cloud-delivered solutions and services that let banks, insurers, and financial firms run accounting, planning, reporting, risk, and compliance workloads. It spans public, private, and hybrid deployments, sold as software or managed services to large enterprises and SMEs.
Scope: what this report covers and excludes
This analysis covers cloud-based finance solutions and services — core accounting, financial planning, forecasting, wealth management, risk and compliance, and payments — across banking, insurance, capital markets and fintech end-users globally. This analysis does not cover general-purpose enterprise cloud infrastructure, non-financial ERP deployments, or consumer fintech applications.
How big is the market for Finance Cloud Market?
Estimates diverge sharply because each publisher defines "finance cloud" differently — some count only SaaS finance applications, others bundle infrastructure and managed services. The table below compares the principal published benchmarks.
Estimate (Base Year)
Horizon
CAGR
Definition / Scope
Attribution
USD 32.8 Bn (2024)
2034
22.7%
Broad: solutions + services across all financial end-users
One published estimate
USD 37.45 Bn (2025)
2031
15.3%
Narrower: solution-led, excludes some infrastructure
A competing analysis
USD 19.96 Bn (2021)
2030
20.3%
Application-centric, excludes pure infrastructure
A third published estimate
USD 141.61 Bn (2034)
2034
15.8%
Broad offering + deployment scope, later base
A fourth published estimate
Our analysis suggests the USD 32.8 billion base and 22.7% CAGR are the most defensible headline figures for a buyer-facing overview, because they align with the 2025 baseline of USD 37–43 billion reported by competing analyses once a year of growth is applied. The wide 15–23% CAGR band implies forecast uncertainty of roughly USD 60–100 billion by 2034 — a gap precise sub-segment forecasting must close.
How is the market segmented?
Segmentation converges on offering, deployment, organization size, application and end-user. The table summarizes the non-geographic parents and their children.
Banks, Financial Service Providers, Insurance, Capital Markets, FinTech / Neo-banks
Services held 60% share in 2024, reflecting migration, integration and managed-service demand. Solutions, however, are forecast to grow faster as AI and analytics embed directly in finance platforms.
Which region leads in Finance Cloud Market?
North America leads the global finance cloud market with roughly 39–40% of revenue, supported by deep cloud adoption, digital banking maturity, and concentrated fintech investment. Asia-Pacific is the fastest-growing region.
Finance Cloud Market Regional Market Share
Loading chart...
Finance Cloud Market Regional Market Share
Region
Market Share (%)
North America
0.39%
Europe
0.26%
Asia-Pacific
0.24%
South America
0.06%
Middle East & Africa
0.05%
Geography tree:
North America
United States
Canada
Mexico
Europe
Germany, UK, France, Italy, Spain, Netherlands
Asia Pacific
China, Japan, India, South Korea, Australia
Latin America
Brazil, Mexico, Argentina
Middle East & Africa
Saudi Arabia, UAE, South Africa
Asia-Pacific's 16–18% CAGR reflects digital-banking scale-up and cloud-native core replacements. Europe's growth is regulation-led, with DORA mandating upgraded ICT risk controls for roughly 22,000 financial entities.
What is driving growth — and what is holding it back?
Demand for operational efficiency and regulatory real-time transparency are the strongest drivers, while data-security concerns and legacy integration complexity are the main restraints.
Factor
Direction
Evidence Strength
Mechanism
Operational efficiency
Driver
High
20–30% faster month-end close reported post-migration
Regulatory real-time reporting (DORA, Basel III)
Driver
High
Mandates auditable, compliant cloud controls
GenAI self-service analytics
Driver
Medium
Conversational forecasting and reconciliation
CRM and customer-data management
Driver
Medium
Hyper-personalization at scale
Data privacy and security concerns
Restraint
High
Slows core-workload migration
Legacy system integration complexity
Restraint
High
Raises migration cost and timeline
Cloud cost escalation / FinOps gaps
Restraint
Medium
Erodes ROI without optimization
Our analysis suggests the driver-restraint balance favors growth: 98% of financial institutions already use at least one cloud service, up from 91% in 2020, meaning the market has passed critical mass. The binding constraint is no longer adoption intent but execution — integration talent and regulatory assurance.
Who are the leading vendors?
The competitive field splits into hyperscalers, enterprise-software incumbents, and IT services firms, each with distinct moats.
Vendor
Category
Core Strength
AWS
Hyperscaler
Breadth of infrastructure, financial-services cloud
Microsoft
Hyperscaler + SaaS
Azure plus Dynamics 365 and Workday adjacency
Google Cloud
Hyperscaler
Data and AI tooling, Deutsche Bank partnership
IBM
Hybrid cloud + services
Regulated-industry trust, hybrid deployments
Oracle
SaaS + infrastructure
ERP and core banking integration
SAP
Enterprise software
Finance ERP and planning depth
Salesforce
SaaS
CRM-led finance engagement
Workday
SaaS
EPM and AI-powered accounts payable
Infosys / TCS / Wipro
IT services
Migration, integration, managed services
Hyperscalers control infrastructure economics, but services firms capture the migration and compliance spend — that split is why "services" still holds a 60% revenue share. Differentiation increasingly rests on embedded RegTech, model governance, and data-residency controls rather than raw compute.
What do buyers and operators need to know? (Decision Support)
Buyers should prioritize regulatory assurance over headline price. DORA, Basel III and PSD2 compliance require immutable logs, automated audit evidence and cross-jurisdiction data residency — capabilities that are hard to retrofit and expensive to switch away from. Procurement teams should test vendor support for continuous security validation and zero-trust networking before signing multi-year contracts.
Switching costs are significant: core finance migrations typically run 18–36 months and involve data-model conversion, integration rebuilds and regulatory re-certification. Organizations that underestimate integration complexity face budget overruns and delayed ROI. Mission-critical selection criteria include proven migration track records, FinOps tooling to control consumption spend, and AI model-governance frameworks that satisfy auditors.
Operators should also plan for hybrid or multi-cloud from day one — public cloud leads on cost and scale, but regulated core workloads often require private or hybrid controls. The full report details vendor-by-vendor compliance posture and migration risk profiles.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a durable multi-year expansion: 22.7% headline CAGR is aggressive but corroborated by a 98% institutional adoption rate and regulation-led demand. The strongest counter-argument is that the 15–16% CAGR camp is more accurate because it strips out services double-counting — a fair critique that implies the true underlying software growth is closer to 16–18%, with services inflating the headline.
Our analysis suggests the strategic battleground is shifting from infrastructure to the AI-and-compliance layer. GenAI rollouts — Workday's AI-powered accounts payable, FIS Treasury GPT — require GPU scale and model governance simultaneously, favoring vendors that bundle both. Services firms that fail to productize RegTech will see margin compression as hyperscalers embed compliance natively.
Actionable strategy:
Vendors should prioritize embedded RegTech and GenAI compliance modules to capture the fastest-growing 15%+ CAGR sub-segments.
Buyers should negotiate data-residency and audit-evidence clauses upfront, since switching costs after migration are prohibitive.
Investors should weight services-led vendors cautiously — growth is real, but pricing power is migrating to platform owners.
Evidence that would change our conclusion: a sustained slowdown in European DORA-driven modernization, or hyperscaler pricing that pushes regulated workloads back on-premise, would materially lower the 2034 forecast.
Table 16: Europe Finance Cloud Market Revenue Billion Forecast, by Offering 2020 & 2034
Frequently Asked Questions
1. How big is the finance cloud market in 2024?
The global finance cloud market was valued at USD 32.8 billion in 2024, according to one widely cited published estimate. Competing analyses place 2025 revenue between USD 37 billion and USD 43 billion, reflecting differing scope definitions.
2. What is the finance cloud market growth rate?
Published CAGRs range from 15.3% to 22.7% depending on scope. The 22.7% figure applies to a broad solutions-and-services definition through 2034, while narrower application-only definitions cluster near 15–16%.
3. Which region dominates the finance cloud market?
North America leads with roughly 40% of global revenue, driven by cloud maturity and digital banking investment. Asia-Pacific is the fastest-growing region at approximately 16–18% CAGR through the forecast period.
4. Who are the leading finance cloud vendors?
AWS, Microsoft, Google, IBM, Oracle and SAP lead the platform tier, while Infosys, TCS and Wipro dominate migration and managed services. Salesforce and Workday are prominent in finance SaaS applications.
5. What is driving finance cloud adoption?
Operational efficiency, regulatory real-time reporting such as DORA, GenAI-enabled analytics and improved customer data management are the primary drivers. Data-security concerns and legacy integration complexity remain the main restraints.
6. Which segment is largest in the finance cloud market?
Services held about 60% of revenue in 2024, while public cloud led deployment at roughly 57%. Large enterprises account for about 70% of spend, with SMEs growing fastest at around 17% CAGR.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement over desk research. In-depth interviews were conducted with stakeholders across the finance cloud value chain, including hyperscale cloud infrastructure providers, enterprise finance-software vendors, system integrators, managed-service providers, and financial-institution technology buyers. Decision-makers interviewed included Chief Information Officers, Heads of Finance Transformation, Compliance and Risk Directors, and VP-level Procurement Leads at banking, insurance and capital-markets firms.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
CIOs & Heads of Finance Transformation
38%
Compliance & Risk Directors
27%
Procurement & Vendor Management Leads
20%
Cloud Infrastructure Architects
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hyperscale Cloud Providers
30%
Enterprise Finance Software Vendors
28%
System Integrators & IT Services
25%
Managed Service & RegTech Providers
17%
Secondary Benchmarking & Public Trade Validation
Desk research triangulates official multilateral and regulatory databases — UN Comtrade, WTO, Eurostat, US ITC, SEC 10-K filings, corporate investor presentations, and patent databases — alongside recognized standards bodies and financial-services industry associations. Public regulatory frameworks including DORA, Basel III and PSD2 were reviewed to validate compliance-driven demand assumptions. No competitor market-research publisher is cited in validation.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down and Bottom-Up models. The top-down model allocates macroeconomic IT-spend forecasts across financial-services segments; the bottom-up model builds from vendor revenue, contract values, deployment volumes and end-user consumption. Divergences are reconciled through weighted averaging, with scope definitions applied consistently across both approaches.
 Finance Cloud Market