 Middle East Phosphate Fertilizer Market
 2026: Size & Forecast
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 217

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Phosphate Fertilizer Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2024 | 1.230 B |
| 2025 | 1.300 B |
| 2026 | 1.380 B |
| 2027 | 1.460 B |
| 2028 | 1.550 B |
| 2029 | 1.640 B |
| 2030 | 1.730 B |

The Middle East phosphate fertilizer market covers finished phosphorus-bearing fertilizers — principally MAP, DAP, TSP and SSP — sold into agriculture across GCC states, the Levant and North Africa. It spans mined phosphate rock conversion, phosphoric acid, and downstream granulation, with output split between domestic crop nutrition and export trade.
This analysis covers finished phosphate fertilizer products (MAP, DAP, TSP, SSP and blended phosphate grades) sold into agricultural applications across Middle East countries, measured at manufacturer/exporter revenue level for 2024–2033. Both domestic consumption and export-destined volumes originating in the region are addressed.
This analysis does not cover phosphate rock mining as a standalone commodity, phosphoric acid merchant trade, nitrogenous or potassic fertilizers, or specialty micronutrient products except where referenced as adjacent demand drivers. Non-agricultural uses such as industrial phosphates and detergents are excluded.
A published estimate puts the region at 1,232.5 Million in 2024, reaching 2,029.0 Million by 2033 at 5.8% CAGR. Broader phosphate and fertilizer benchmarks imply faster headline growth, but those cover global or all-nutrient scopes and are not directly comparable.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 1,232.5 Million | 2024 | 2033 | 5.8% | Middle East finished phosphate fertilizers, revenue | One published estimate |
| 3,352.4 Million (Middle East) | 2025 | 2033 | 5.7% | Middle East phosphate fertilizers, wider definition | A competing analysis |
| 55.0 Billion | 2026 | 2031 | 5.3% | Global phosphate fertilizers, all regions | A competing analysis |
| 148 Billion | 2025 | 2035 | 2.1% | Global all-nutrient fertilizer market | A competing analysis |
Our analysis suggests the 1,232.5 Million figure is the most defensible for buyer planning because it isolates finished phosphate product revenue within the region rather than blending in rock, acid, or global tonnage. The wider 3,352.4 Million Middle East figure likely includes intermediate and adjacent nutrient categories; the ~2.7x gap is a scope artifact, not a growth disagreement. Notably, both regional estimates converge near 5.7–5.8% CAGR, which strengthens confidence in the growth trajectory even where absolute values diverge.
Segmentation follows product chemistry and crop application, with product choice driven by nutrient concentration, solubility, irrigation compatibility, and delivered cost per nutrient unit.
| Parent segment | Children | Share signal |
|---|---|---|
| By Product | Monoammonium Phosphate (MAP), Diammonium Phosphate (DAP), Triple Superphosphate (TSP), Single Superphosphate (SSP), Blends & Others | MAP 30.0% (2024); TSP fastest at ~5.3% CAGR |
| By Application | Cereals & Grains, Oilseeds & Pulses, Fruits & Vegetables, Others (turf, forage) | Cereals 49.4% (2024); Fruits & Vegetables fastest at 6.1% CAGR |
| By Form | Dry, Liquid / Water-Soluble | Dry dominant; liquid growing with fertigation |
MAP's lead is structural: high solubility and moderate nitrogen suit drip and precision systems increasingly standard in Gulf horticulture. DAP retains scale in broad-acre and export trade. The implication is a two-tier market — commodity granulation competing on cost, and soluble grades competing on agronomic outcomes and service.
Saudi Arabia leads with 52.9% of 2024 regional revenue, underpinned by integrated phosphate rock reserves, captive phosphoric acid, and state-backed capacity expansion. Jordan, Israel, and Tunisia follow as production-and-export-oriented markets, while GCC states are import-led consumption hubs.
| Country | 2024 share |
|---|---|
| Saudi Arabia | 52.9% |
| Jordan | ~10.8% |
| Israel | ~9.3% |
| UAE | ~7.7% |
| Tunisia | ~6.2% |
| Qatar | ~4.1% |
| Kuwait | ~2.8% |
| Oman | ~2.4% |
| Rest of Middle East | ~3.8% |
Our analysis suggests the concentration in Saudi Arabia is a supply-side fact more than a demand-side one: domestic application is limited by arable land, so Saudi volume is structurally export-facing. That means regional revenue is highly sensitive to seaborne DAP pricing and to import-market policy in South Asia and Africa — a risk buyers should model explicitly.
Growth is driven by food-security policy, protected-cultivation expansion, and fertigation adoption; it is restrained by phosphate affordability sensitivity, sulfur and ammonia input costs, and salinity risk in arid soils. The net balance favors steady rather than explosive expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Government food-security programs | Driver | Strong | Subsidies and self-sufficiency targets raise fertilizer intensity |
| Protected cultivation & fertigation | Driver | Strong | Water-soluble grades lift per-hectare nutrient spend |
| Structural soil phosphorus depletion | Driver | Strong | Recurring replacement demand for yield stability |
| Integrated capacity expansion (Saudi, Morocco) | Driver | Moderate | Improves availability; shifts trade flows to low-cost producers |
| Phosphate affordability sensitivity | Restraint | Strong | Farmers defer P application when prices spike |
| Sulfur, ammonia, rock cost volatility | Restraint | Moderate | Raises finished-product prices, compresses demand |
| Soil salinity build-up | Restraint | Moderate | Limits repeated application in Gulf soils |
Phosphorus demand behaves differently from nitrogen: residual soil phosphorus lets growers defer purchases, making volumes cyclical and price-elastic. Our analysis suggests this is the single most under-modelled risk in regional forecasts — headline CAGR looks stable, but annual volume can swing sharply around input-cost shocks.
Ma'aden anchors regional supply through integrated rock-to-fertilizer capacity in Saudi Arabia; OCP Group and ICL Group compete on export scale and specialty grades; Mosaic and Yara International participate through trade and distribution positions.
| Company | Regional position | Strategic basis |
|---|---|---|
| Ma'aden (Saudi Arabia) | Anchor producer | Vertically integrated rock, acid, DAP/MAP; state backing |
| OCP Group (Morocco) | Major export supplier | Lowest-cost rock reserves; downstream expansion |
| ICL Group (Israel) | Specialty and potash-linked | High-value crop and specialty phosphate positions |
| Mosaic Company | Global integrated | Rock and finished product trade into region |
| Yara International | Distribution and blends | Commercial reach and crop nutrition services |
| Regional blenders | GCC last-mile | Water-soluble and custom blends, agronomic advice |
Differentiation is shifting from tonnage to integration and service. Control of rock and acid is the durable moat; for everyone else, the defensible position is formulation, logistics reliability, and agronomic support embedded with the grower. Vendors without either face structural margin compression.
Procurement decisions in this region hinge on supply security and grade fit more than on headline price. Integrated producers can weather input shocks; import-dependent buyers cannot, so contract structure matters as much as unit cost.
Buyers should prioritize suppliers with demonstrated acid and rock integration, because sulfur and ammonia volatility transmits directly into DAP/MAP pricing. Where fertigation is deployed, specify solubility and salt index explicitly — irrigation emitter fouling and salinity build-up are costly failure modes in Gulf conditions.
Switching costs are moderate for commodity granulation but rise sharply for water-soluble and blended grades tied to agronomic programs. Regulatory exposure is comparatively light versus European nutrient-reduction regimes, but export controls and trade policy in destination markets remain a live risk. Our analysis suggests dual-sourcing across at least one integrated and one regional blender is the pragmatic default.
The balance of evidence favors a grade-mix shift rather than a volume land-grab. Regional CAGR of 5.8% is respectable but not generous, and it is concentrated in soluble and specialty-adjacent applications growing faster than bulk granulation. Producers who treat MAP and DAP as undifferentiated commodities will compete on price against integrated low-cost rock owners and lose.
The strongest counter-argument is that food-security spending and capacity expansion in Saudi Arabia could unlock faster bulk volume than the base case assumes. That is credible — but it argues for supply-side opportunity, not margin expansion, since new integrated capacity tends to compress finished-product spreads. Our position holds unless destination-market demand accelerates materially.
What would change this conclusion: sustained sulfur and ammonia cost relief combined with a demand rebound in South Asian import markets would shift value back toward bulk DAP/MAP volume growth.
While this overview frames the strategic picture, precise grade-level forecasting, country-level volume splits, and vendor capacity mapping require the full dataset — particularly for the fast-growing soluble segment where public benchmarks are thin.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.53% |
| Jordan | 0.11% |
| Israel | 0.09% |
| UAE | 0.08% |
| Tunisia | 0.06% |
| Qatar | 0.04% |
| Kuwait | 0.03% |
| Oman | 0.02% |
| Rest of Middle East | 0.04% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.8% from 2020-2034 |
| Segmentation |
|
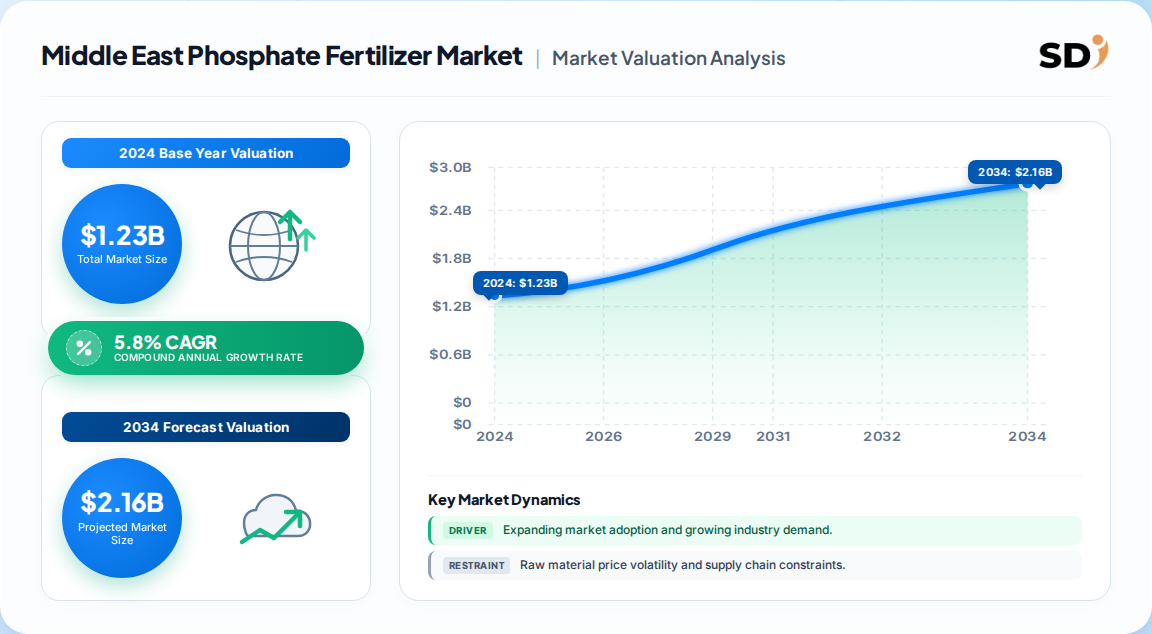
The Middle East phosphate fertilizer market was estimated at 1,232.5 Million in 2024 and is projected to reach 2,029.0 Million by 2033. Growth runs at 5.8% CAGR across 2025–2033, with Saudi Arabia contributing over half of regional revenue.
Saudi Arabia leads with 52.9% of 2024 regional revenue, driven by integrated phosphate rock reserves, captive phosphoric acid capacity, and state-backed expansion. Jordan, Israel and Tunisia follow as production-export markets, while GCC states are import-led consumers.
Monoammonium phosphate (MAP) held the largest product share at 30.0% in 2024, favored for its solubility and fit with drip irrigation. Triple superphosphate is the fastest-growing grade at roughly 5.3% CAGR on nutrient-density and logistics economics.
Fruits and vegetables are expected to grow at 6.1% CAGR through 2033, driven by greenhouse farming, horticulture investment, and export-oriented agribusiness. Cereals and grains remain the largest segment at 49.4% share on food-security policy support.
Ma'aden anchors regional supply through integrated rock-to-fertilizer capacity in Saudi Arabia. OCP Group, ICL Group, Mosaic Company and Yara International compete on export scale, specialty grades and distribution, alongside regional blenders serving GCC last-mile demand.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the phosphate value chain, including phosphate rock and acid suppliers, specialized fertilizer producers, contract formulators and blenders, and global distributors serving GCC and Levant markets. Interviewees were drawn from decision-maker designations including VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring both supply-side capacity and demand-side procurement behavior were captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 22% |
| Regulatory & Compliance Managers | 13% |
| Company Type | Representation (%) |
|---|---|
| Phosphate Rock & Acid Producers | 40% |
| Specialized Fertilizer Producers | 30% |
| Formulators & Blenders | 18% |
| Distributors & Traders | 12% |
Findings were cross-validated against UN Comtrade and WTO trade flows, national customs statistics, corporate annual filings and investor presentations, patent databases, and technical standards published by recognized industry associations. No third-party market research publisher data was used for validation.
Top-down macroeconomic and crop-segment allocation was run simultaneously with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Divergences between the two approaches were reconciled at country level before aggregation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |