Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Smart Agriculture Farming Market by Offering (Hardware, Software, Services), by Application (Precision Farming, Livestock Monitoring, Smart Greenhouse, Field Mapping, Farm Labor Management), by Farm Size (Small & Medium Farms, Large Farms), by Connectivity (Cellular IoT, LPWAN, Satellite IoT), by Farming Environment (Open-Field Agriculture, Indoor Farming, Controlled Environment Agriculture), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 259
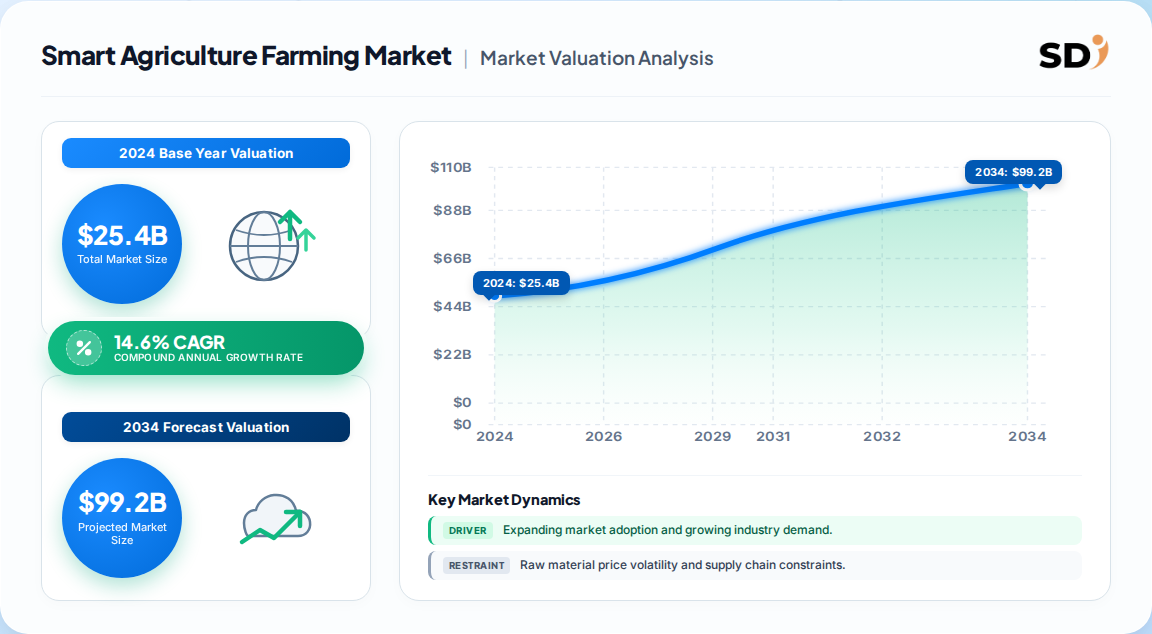
The global Smart Agriculture Farming Market was valued at 25.4 Billion in 2024 and is projected to reach 83.7 Billion by 2033 at a 14.6% CAGR (2025–2033).
Hardware dominated 2024 revenue at 66.1%, but software and services are the fastest-growing layers as growers shift to outcome-based models.
Precision farming led applications in 2024; smart greenhouse is the fastest-growing segment (17.3% CAGR) driven by urban agriculture.
North America held 43.5% of 2024 revenue; Asia-Pacific is the fastest-growing region (14.8% CAGR) on government digitalization subsidies.
Leading vendors include Deere & Company, Trimble, AGCO, CNH Industrial, and DJI, with consolidation accelerating around autonomous equipment and data platforms.
Why this matters for decision-makers: Vendors must pivot from selling hardware boxes to interoperable, data-driven service ecosystems—or risk margin compression as buyers demand guaranteed yield and sustainability ROI.
Smart Agriculture Farming Market Size (In Billion)
75.0B
60.0B
45.0B
30.0B
15.0B
0
25.40 B
2024
29.10 B
2025
33.40 B
2026
38.20 B
2027
43.80 B
2028
50.20 B
2029
57.50 B
2030
Smart Agriculture Farming Market Size (In Billion)
Year
Market Size
2024
25.40 B
2025
29.10 B
2026
33.40 B
2027
38.20 B
2028
43.80 B
2029
50.20 B
2030
57.50 B
What is the Smart Agriculture Farming Market?
Smart agriculture farming is the use of IoT sensors, GPS guidance, drones, AI analytics, and robotics to optimize crop and livestock production. It spans hardware, software, and services that enable real-time field monitoring, variable-rate input application, autonomous machinery, and data-driven farm management—helping growers raise yields, cut input waste, and meet traceability mandates.
Scope: what this report covers and excludes
This report covers the global smart agriculture farming market across hardware, software, and services, spanning precision farming, livestock monitoring, smart greenhouse, and field mapping applications. It analyzes farm-size segments, connectivity technologies, and five major regions. This analysis does not cover traditional farm machinery without digital connectivity, commodity trading platforms, or generic rural broadband infrastructure outside agricultural use.
How big is the market for Smart Agriculture Farming Market?
The market was valued at 25.4 Billion in 2024, with forecasts to 83.7 Billion by 2033 at a 14.6% CAGR—though competing estimates vary by definition and scope.
The 25.4B base is the most defensible: it aligns with mid-range CAGRs and consistent North American dominance. Higher 29.8B estimates likely include fish farming and adjacent software categories, inflating the base. Our analysis suggests the 14.6% CAGR is achievable only if satellite connectivity costs fall and interoperability standards mature.
How is the market segmented?
Segmentation is defined by offering, application, farm size, connectivity, and technology layer, with hardware still commanding the largest revenue pool.
Parent Segment
Children
By Offering
Hardware (Automation & Control, HVAC, LED Grow Lights, RFID, Sensors), Software (Farm Management, AI Analytics), Services (Integration, Managed Services)
Hardware's 66.1% share is a legacy of mechanization; the strategic battleground is software and services, where recurring revenue and switching costs are highest.
Which region leads in Smart Agriculture Farming Market?
North America leads with 43.5% of 2024 revenue, driven by large farm sizes, advanced GPS adoption, and capital availability. Asia-Pacific is the fastest-growing region at 14.8% CAGR.
Asia Pacific (China, Japan, India, South Korea, Australia)
Latin America (Brazil, Argentina, Mexico)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
Region
2024 Share
North America
43.5%
Europe
23.5%
Asia-Pacific
24.0%
South America
4.5%
Middle East & Africa
4.5%
Our analysis suggests Asia-Pacific's share will approach 30% by 2033 as government subsidy programs in India, China, and Southeast Asia close the adoption gap.
What is driving growth — and what is holding it back?
Drivers include labor shortages, IoT/AI equipment adoption, and government subsidies; restraints include high capex, poor rural connectivity, and data-ownership concerns.
USDA, EU, and APAC programs de-risk adoption and compress payback
Ag-labor shortages
Driver (+2.1% CAGR)
High
70,000 vacant US farm roles in 2024 accelerate robotics demand
Traceability mandates
Driver (+1.9% CAGR)
Medium
Retailer provenance requirements drive blockchain and data platforms
High upfront capex
Restraint (-2.3% CAGR)
High
Only farms above ~$113K revenue achieve positive NPV from precision tools
Rural connectivity gaps
Restraint (-1.2% CAGR)
Medium
Poor broadband limits cloud platforms and real-time data exchange
Data privacy concerns
Restraint (-1.8% CAGR)
Medium
55% of farmers worry about agronomic data misuse
The balance favors growth: subsidy programs and falling satellite costs offset capex barriers. However, the gap between large and small farms is widening—a structural risk for vendors targeting smallholders.
Who are the leading vendors?
The vendor landscape is medium-concentrated, with machinery incumbents and ag-tech specialists competing on autonomy, data platforms, and connectivity.
Company
Core Strength
Differentiation
Deere & Company
Autonomous tractors, precision ag
16-camera LiDAR autonomy; 500 acres/day
Trimble Inc.
GPS guidance, data platforms
Connected Climate Exchange; carbon data
AGCO Corporation
Precision planting, PTx Trimble JV
$2B JV targeting data-centric offerings
CNH Industrial
Equipment automation
Broad global dealer network
DJI Technology
Agricultural drones
Cost leadership in imaging drones
Kubota
Robotics, KATR robot
Multi-function autonomy, 530-lb haul
Incumbents' moats are dealer networks and field data; ag-tech specialists compete on software agility and AI. Our analysis suggests acquisitions will target connectivity and analytics startups, not hardware.
What do buyers and operators need to know?
Buyers must prioritize interoperability over feature depth: siloed vendor ecosystems create switching costs that erode ROI. Procurement should demand API access and data portability clauses before signing multi-year software contracts. Connectivity is the hidden risk—satellite IoT at 28% CAGR signals that rural coverage gaps will close, but only for buyers who plan for hybrid connectivity. Regulatory compliance around data ownership (EU GDPR, US state privacy laws) and carbon reporting (USDA interim rule) is becoming a procurement criterion. Smallholders should pursue cooperative or subsidy-backed purchasing to offset capex. Finally, validate ROI claims against farm size: tools profitable at 500 acres may fail at 100.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a 14.6% CAGR trajectory, anchored by labor shortages and subsidy programs that de-risk adoption. The strongest counter-argument is the capex barrier: if commodity prices fall, smallholder adoption stalls and growth concentrates in large-farm segments. This divergence implies vendors should segment go-to-market by farm size, not geography. Our analysis suggests the software/services layer will capture disproportionate value by 2030, as hardware commoditizes and buyers demand outcome guarantees. The satellite IoT disruption (28% CAGR) is underappreciated—it will unlock remote acres and reshape connectivity pricing.
Investors: Prioritize software platforms and satellite connectivity providers over hardware OEMs; margin expansion lies in recurring revenue.
Operators: Build interoperability and data portability into procurement; avoid single-vendor lock-in.
Vendors: Target Asia-Pacific subsidy programs and mid-size farms with financing models to capture the fastest-growing demand pool.
What would change our conclusion: a sustained drop in crop prices below 2023 levels or failure of interoperability standards would push CAGR below 12%, favoring consolidation over expansion.
Europe Smart Agriculture Farming Market Revenue Billion Forecast, by Offering 2020 & 2034
Frequently Asked Questions
1. How big is the Smart Agriculture Farming Market?
The market was valued at 25.4 Billion in 2024 and is projected to reach 83.7 Billion by 2033, growing at a 14.6% CAGR. North America led with 43.5% revenue share in 2024.
2. What is driving the smart agriculture farming market growth?
Labor shortages, IoT/AI-enabled equipment, and government subsidies are the primary drivers. Autonomous tractors and predictive analytics raise yields 15–20% while cutting inputs 25–30%.
3. Which region is fastest-growing in smart agriculture?
Asia-Pacific is the fastest-growing region at 14.8% CAGR, driven by government digitalization subsidies in India, China, and Southeast Asia. North America remains the largest market.
4. Who are the leading vendors in smart agriculture?
Leading vendors include Deere & Company, Trimble, AGCO, CNH Industrial, DJI Technology, and Kubota. Competition is shifting toward autonomous equipment and data-driven service platforms.
5. What are the main barriers to smart agriculture adoption?
High upfront capex, poor rural connectivity, and data-privacy concerns are the main barriers. Only farms above roughly $113,000 revenue achieve positive NPV from full precision suites.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain: sensor and hardware component suppliers, autonomous equipment manufacturers, farm management software providers, agricultural cooperatives, and regional distributors. Decision-makers interviewed include VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads across North America, Europe, and Asia-Pacific, ensuring coverage of both large-farm and smallholder adoption dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technology Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Regulatory & Compliance Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hardware & Equipment Manufacturers
40%
Software & Analytics Providers
30%
Distributors & Cooperatives
20%
Service & Integration Providers
10%
Secondary Benchmarking & Public Trade Validation
We triangulate findings against official multilateral databases including UN Comtrade, WTO trade statistics, US ITC, and Eurostat, alongside corporate 10-K filings, SEC disclosures, and annual investor presentations from leading equipment OEMs. Patent databases and recognized non-profit technical standards bodies—including ISO agricultural machinery standards and industry associations—provide validation of technology adoption curves and interoperability maturity.
Demand Modeling & Market Sizing Triangulation
Market sizing uses simultaneous top-down macroeconomic and industry segment allocation alongside bottom-up manufacturer capacity, pricing, and end-use consumption modeling. Connectivity adoption rates, farm-size distributions, and subsidy program allocations are cross-validated against national agricultural registries and trade flow data.
 Smart Agriculture Farming Market