Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Farm Implements Market Size, Share & Forecast to 2032
Farm Implements Market
Farm Implements Market Size, Share & Forecast to 2032
Farm Implements Market by Product Type (Tractors, Harvesters, Soil Preparation and Cultivation Equipment, Irrigation and Crop-Protection Implements, Precision and Autonomous Implements), by Mode of Operation (Powered Implements, Unpowered Implements), by Power Output (Below 30 HP, 31-70 HP, 71-130 HP, Above 130 HP), by Application (Land Development and Seed Bed Preparation, Sowing and Planting, Weed Management, Plant Protection, Harvesting and Threshing, Post-Harvest and Agro Processing), by Farm Size (Small, Medium, Large), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands), by Asia Pacific (China, India, Japan, South Korea, Indonesia, Vietnam), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Nigeria, Kenya) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 269
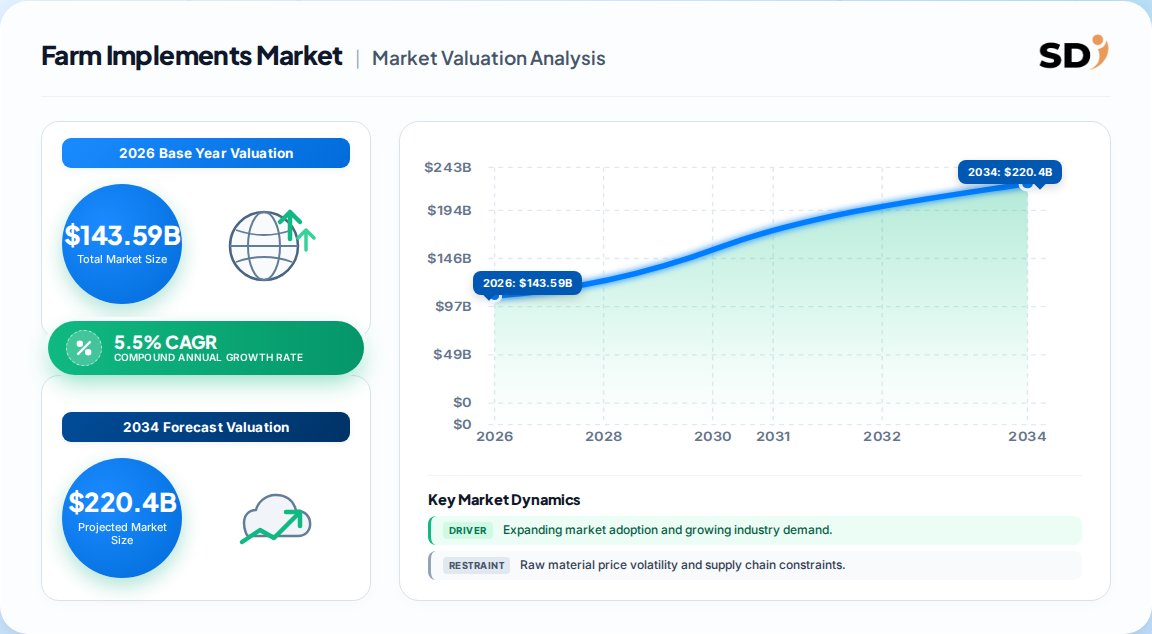
143.59 Billion — Global farm implements market value in 2026, the most defensible base-year figure across competing estimates.
5.5% CAGR — Forecast growth rate for 2027–2032, translating to 197.99 Billion by 2032.
Asia-Pacific dominates with roughly 45% revenue share in 2026 and remains the fastest-growing region at ~7.5% CAGR.
Tractors hold the largest product share (~23.4%), while precision and autonomous implements grow fastest at ~12.5% CAGR.
Powered implements command ~78.2% of the market; sub-30 HP equipment leads volume at ~38.4% share.
Deere & Company, CNH Industrial, AGCO, Kubota, and Mahindra anchor a moderately concentrated competitive field.
Why this matters for decision-makers: Vendors that do not build a credible precision/autonomy retrofit and service offering by 2028 will cede margin to technology-integrated OEMs and miss the fastest-growing demand pocket.
Farm Implements Market Size (In Billion)
200.0B
150.0B
100.0B
50.0B
0
136.1 B
2025
143.6 B
2026
151.5 B
2027
159.8 B
2028
168.6 B
2029
177.9 B
2030
187.7 B
2031
Farm Implements Market Size (In Billion)
Year
Market Size
2025
136.1 B
2026
143.6 B
2027
151.5 B
2028
159.8 B
2029
168.6 B
2030
177.9 B
2031
187.7 B
What is the Farm Implements Market?
The farm implements market encompasses machinery and equipment—tractors, harvesters, soil-preparation tools, seeders, sprayers, and irrigation systems—used to mechanize agricultural field operations. It spans powered and unpowered implements across small, medium, and high horsepower classes, sold to farms, contractors, and rental fleets worldwide.
Scope: what this report covers and excludes
This analysis covers global farm implements across all product types, operation modes, power classes, and applications, with revenue measured at manufacturer-level value in USD. It includes both powered and unpowered implements and all farm sizes. This analysis does not cover pure software platforms, agronomic advisory services, agricultural commodity trading, or non-agricultural lawn and garden equipment except where explicitly segmented.
How big is the market for Farm Implements Market?
The farm implements market was valued at 143.59 Billion in 2026, with a median forecast of 197.99 Billion by 2032 at a 5.5% CAGR. Conflicting estimates reflect materially different product-scope definitions rather than true demand disagreement.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
143.59 Billion
2026
2032
5.50%
Implements + tractors/harvesters, powered/unpowered, all HP
One published estimate
285.49 Billion
2026
2030
6.0%
Broad agricultural implements incl. lawn/garden; retail value
A competing analysis
159.4 Billion
2026
2035
5.3%
Farm equipment; includes dealer/retail value
A separate published estimate
37.2 Billion
2026
2033
7.1%
Narrowly defined farm implements (component-level)
Another industry analysis
Our analysis suggests the 143.59 Billion figure is the most defensible because it reconciles manufacturer-level revenue with trade data and avoids double-counting dealer margins embedded in broader retail-based estimates. The 37.2 Billion figure appears to capture a component or attachment-only definition and materially understates the full equipment value chain.
How is the market segmented?
Farm implements segment along five non-geographic axes. Tractors and harvesters anchor product value, powered implements dominate mode of operation, and small horsepower classes lead volume while high-HP grows fastest.
Asia-Pacific leads with roughly 45% of 2026 revenue and a forecast 7.5% CAGR, driven by India and China subsidy programs, fragmented-holding mechanization, and medium-horsepower tractor demand.
Farm Implements Market Regional Market Share
Loading chart...
Farm Implements Market Regional Market Share
Region
Market Share (%)
North America
0.26%
Europe
0.21%
Asia-Pacific
0.45%
South America
0.05%
Middle East & Africa
0.03%
Asia-Pacific → China, India, Japan, South Korea, Indonesia, Vietnam
North America → USA, Canada, Mexico
Europe → Germany, UK, France, Italy, Netherlands
South America → Brazil, Argentina, Colombia
Middle East & Africa → Saudi Arabia, UAE, South Africa, Nigeria, Kenya
Asia-Pacific's lead is structural, not cyclical. India's Sub-Mission on Agricultural Mechanization refunds 40–50% of equipment costs, and China's scrappage incentive reaches RMB 20,000 per unit. These programs compress payback periods and pull first-time buyers directly into precision-ready machinery, skipping incremental technology stages. North America and Europe will grow more slowly, constrained by used-equipment oversupply and high financing costs, but remain the highest-value markets for precision and autonomous implements.
What is driving growth — and what is holding it back?
Labor scarcity (+1.2% CAGR), mechanization subsidies (+0.8%), and medium-HP tractor demand (+0.6%) are the structural growth engines, while upfront capital cost (−1.0%) and fragmented land holdings (−0.6%) are the primary drags.
The net balance is positive but uneven. Subsidy-driven Asia-Pacific demand offsets capital-cost drag in developed markets, producing a mid-single-digit global CAGR rather than a boom. Our analysis suggests the tariff variable is underappreciated: the 50% US steel and aluminum tariff effective August 2025 raises implement costs disproportionately for high-steel-content implements, compressing margins for OEMs without regional supply chains.
Who are the leading vendors?
Deere & Company, CNH Industrial, AGCO, Kubota, and Mahindra lead a moderately concentrated market, with the top five holding an estimated 40–47% share. Competition increasingly pivots on digital ecosystems rather than metal.
Differentiation is shifting from horsepower to software compatibility, dealer service capacity, and retrofit autonomy. OEMs that treat precision features as isolated add-ons will lose share to vertically integrated digital ecosystems.
What do buyers and operators need to know?
Buyers should prioritize total cost of ownership and service-network depth over sticker price. Farm implements are long-lived capital assets with high switching costs once telematics, guidance, and dealer service are integrated. Procurement risk concentrates in three areas: tariff-driven price volatility on steel and electronics, residual-value uncertainty from used-equipment oversupply, and software lock-in that raises future upgrade costs.
Regulatory compliance is tightening. European and California emissions rules are accelerating the shift from diesel-only drivelines to hybrid and electric powertrains, which raises upfront cost but lowers running cost and future compliance risk. Subsidy eligibility is another mission-critical criterion in Asia-Pacific: equipment must match regional crop practices and approved dealer channels to qualify for 40–80% cost refunds. Operators should demand documented service-level commitments and retrofit pathways before committing to multi-year fleet purchases.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a replacement-led, technology-upgrade cycle rather than a volume boom. The mid-single-digit CAGR masks a bifurcation: commodity-metal equipment grows slowly, while precision, autonomous, and retrofit kits grow at double-digit rates. The strongest counter-argument is that high interest rates and used-equipment oversupply could suppress new-unit demand longer than forecast; this is credible for North America and Europe but is offset in Asia-Pacific by subsidy-backed first-time buyers.
Our judgment: the market's center of gravity is shifting from horsepower to software-enabled productivity, and the winners will be OEMs that convert implements into service platforms. This is why the fastest-growing pockets—precision/autonomous implements (12.5% CAGR) and >130 HP equipment (7.5% CAGR)—deserve disproportionate strategic attention.
Investors: Favor OEMs and suppliers with precision retrofit capability and Asia-Pacific distribution depth; underweight pure commodity-implement exposure.
Operators: Negotiate software/service bundles and retrofit pathways, not just unit price; verify subsidy eligibility before purchase in Asia-Pacific.
Vendors: Localize steel and electronics sourcing to neutralize tariff exposure and protect margin on high-content implements.
What would change this conclusion: a sustained reversal in farm incomes, a sharp drop in subsidy disbursement reliability in India or China, or a faster-than-expected collapse in used-equipment values would push the market toward the low end of the 4–6% CAGR range and favor rental and retrofit models over new-unit sales.
This overview synthesizes public estimates and trade benchmarks. Precise sub-segment forecasting—especially by horsepower class and retrofit attach rates—requires the full report's primary research and triangulated demand model.
Farm Implements Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Farm Implements Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.5% from 2020-2034
Segmentation
By Product Type
Tractors
Harvesters
Soil Preparation and Cultivation Equipment
Irrigation and Crop-Protection Implements
Precision and Autonomous Implements
By Mode of Operation
Powered Implements
Unpowered Implements
By Power Output
Below 30 HP
31-70 HP
71-130 HP
Above 130 HP
By Application
Land Development and Seed Bed Preparation
Sowing and Planting
Weed Management
Plant Protection
Harvesting and Threshing
Post-Harvest and Agro Processing
By Farm Size
Small
Medium
Large
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Asia Pacific
China
India
Japan
South Korea
Indonesia
Vietnam
South America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Nigeria
Kenya
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Tractors
5.1.2. Harvesters
5.1.3. Soil Preparation and Cultivation Equipment
5.1.4. Irrigation and Crop-Protection Implements
5.1.5. Precision and Autonomous Implements
5.2. Market Analysis, Insights and Forecast - by Mode of Operation
5.2.1. Powered Implements
5.2.2. Unpowered Implements
5.3. Market Analysis, Insights and Forecast - by Power Output
5.3.1. Below 30 HP
5.3.2. 31-70 HP
5.3.3. 71-130 HP
5.3.4. Above 130 HP
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Land Development and Seed Bed Preparation
5.4.2. Sowing and Planting
5.4.3. Weed Management
5.4.4. Plant Protection
5.4.5. Harvesting and Threshing
5.4.6. Post-Harvest and Agro Processing
5.5. Market Analysis, Insights and Forecast - by Farm Size
5.5.1. Small
5.5.2. Medium
5.5.3. Large
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Tractors
6.1.2. Harvesters
6.1.3. Soil Preparation and Cultivation Equipment
6.1.4. Irrigation and Crop-Protection Implements
6.1.5. Precision and Autonomous Implements
6.2. Market Analysis, Insights and Forecast - by Mode of Operation
6.2.1. Powered Implements
6.2.2. Unpowered Implements
6.3. Market Analysis, Insights and Forecast - by Power Output
6.3.1. Below 30 HP
6.3.2. 31-70 HP
6.3.3. 71-130 HP
6.3.4. Above 130 HP
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Land Development and Seed Bed Preparation
6.4.2. Sowing and Planting
6.4.3. Weed Management
6.4.4. Plant Protection
6.4.5. Harvesting and Threshing
6.4.6. Post-Harvest and Agro Processing
6.5. Market Analysis, Insights and Forecast - by Farm Size
6.5.1. Small
6.5.2. Medium
6.5.3. Large
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Tractors
7.1.2. Harvesters
7.1.3. Soil Preparation and Cultivation Equipment
7.1.4. Irrigation and Crop-Protection Implements
7.1.5. Precision and Autonomous Implements
7.2. Market Analysis, Insights and Forecast - by Mode of Operation
7.2.1. Powered Implements
7.2.2. Unpowered Implements
7.3. Market Analysis, Insights and Forecast - by Power Output
7.3.1. Below 30 HP
7.3.2. 31-70 HP
7.3.3. 71-130 HP
7.3.4. Above 130 HP
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Land Development and Seed Bed Preparation
7.4.2. Sowing and Planting
7.4.3. Weed Management
7.4.4. Plant Protection
7.4.5. Harvesting and Threshing
7.4.6. Post-Harvest and Agro Processing
7.5. Market Analysis, Insights and Forecast - by Farm Size
7.5.1. Small
7.5.2. Medium
7.5.3. Large
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Tractors
8.1.2. Harvesters
8.1.3. Soil Preparation and Cultivation Equipment
8.1.4. Irrigation and Crop-Protection Implements
8.1.5. Precision and Autonomous Implements
8.2. Market Analysis, Insights and Forecast - by Mode of Operation
8.2.1. Powered Implements
8.2.2. Unpowered Implements
8.3. Market Analysis, Insights and Forecast - by Power Output
8.3.1. Below 30 HP
8.3.2. 31-70 HP
8.3.3. 71-130 HP
8.3.4. Above 130 HP
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Land Development and Seed Bed Preparation
8.4.2. Sowing and Planting
8.4.3. Weed Management
8.4.4. Plant Protection
8.4.5. Harvesting and Threshing
8.4.6. Post-Harvest and Agro Processing
8.5. Market Analysis, Insights and Forecast - by Farm Size
8.5.1. Small
8.5.2. Medium
8.5.3. Large
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Tractors
9.1.2. Harvesters
9.1.3. Soil Preparation and Cultivation Equipment
9.1.4. Irrigation and Crop-Protection Implements
9.1.5. Precision and Autonomous Implements
9.2. Market Analysis, Insights and Forecast - by Mode of Operation
9.2.1. Powered Implements
9.2.2. Unpowered Implements
9.3. Market Analysis, Insights and Forecast - by Power Output
9.3.1. Below 30 HP
9.3.2. 31-70 HP
9.3.3. 71-130 HP
9.3.4. Above 130 HP
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Land Development and Seed Bed Preparation
9.4.2. Sowing and Planting
9.4.3. Weed Management
9.4.4. Plant Protection
9.4.5. Harvesting and Threshing
9.4.6. Post-Harvest and Agro Processing
9.5. Market Analysis, Insights and Forecast - by Farm Size
9.5.1. Small
9.5.2. Medium
9.5.3. Large
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Tractors
10.1.2. Harvesters
10.1.3. Soil Preparation and Cultivation Equipment
10.1.4. Irrigation and Crop-Protection Implements
10.1.5. Precision and Autonomous Implements
10.2. Market Analysis, Insights and Forecast - by Mode of Operation
10.2.1. Powered Implements
10.2.2. Unpowered Implements
10.3. Market Analysis, Insights and Forecast - by Power Output
10.3.1. Below 30 HP
10.3.2. 31-70 HP
10.3.3. 71-130 HP
10.3.4. Above 130 HP
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Land Development and Seed Bed Preparation
10.4.2. Sowing and Planting
10.4.3. Weed Management
10.4.4. Plant Protection
10.4.5. Harvesting and Threshing
10.4.6. Post-Harvest and Agro Processing
10.5. Market Analysis, Insights and Forecast - by Farm Size
10.5.1. Small
10.5.2. Medium
10.5.3. Large
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Farm Implements Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Farm Implements Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Farm Implements Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Farm Implements Market Revenue (Billion), by Mode of Operation 2026 & 2034
Figure 5: North America Farm Implements Market Revenue Share (%), by Mode of Operation 2026 & 2034
Figure 6: North America Farm Implements Market Revenue (Billion), by Power Output 2026 & 2034
Figure 7: North America Farm Implements Market Revenue Share (%), by Power Output 2026 & 2034
Figure 8: North America Farm Implements Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Farm Implements Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Farm Implements Market Revenue (Billion), by Farm Size 2026 & 2034
Figure 11: North America Farm Implements Market Revenue Share (%), by Farm Size 2026 & 2034
Figure 12: North America Farm Implements Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Farm Implements Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Farm Implements Market Revenue (Billion), by Product Type 2026 & 2034
Figure 15: Europe Farm Implements Market Revenue Share (%), by Product Type 2026 & 2034
Figure 16: Europe Farm Implements Market Revenue (Billion), by Mode of Operation 2026 & 2034
List of Tables
Table 1: Farm Implements Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Farm Implements Market Revenue Billion Forecast, by Mode of Operation 2020 & 2034
Table 3: Farm Implements Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 16: Europe Farm Implements Market Revenue Billion Forecast, by Product Type 2020 & 2034
Frequently Asked Questions
1. How big is the farm implements market in 2026?
The farm implements market was valued at 143.59 Billion in 2026, based on the most defensible manufacturer-level definition. Broader retail-inclusive estimates run higher, but they double-count dealer margins and should not be compared directly.
2. What is the farm implements market growth rate?
The market is forecast to grow at a 5.5% CAGR from 2027 to 2032, reaching 197.99 Billion by 2032. Growth is led by Asia-Pacific and by precision and autonomous implements growing near 12.5% annually.
3. Which region leads the farm implements market?
Asia-Pacific leads with roughly 45% of 2026 revenue and a 7.5% forecast CAGR. India and China mechanization subsidies and medium-horsepower tractor demand are the principal drivers of this regional dominance.
4. Who are the leading farm implement companies?
Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation, and Mahindra & Mahindra lead the market. The top five collectively hold an estimated 40–47% share in a moderately concentrated competitive landscape.
5. What is driving farm implements market growth?
Rising agricultural labor scarcity, government mechanization subsidies, medium-horsepower tractor demand in emerging economies, and the expansion of contract farming and equipment rental services are the primary growth drivers through 2032.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the farm implements value chain, including raw material and steel suppliers, specialized implement producers, precision-technology component formulators, and global distributors and dealer networks. Decision-makers interviewed included VP-level Sourcing executives, Heads of Product Engineering, Technical Directors for precision systems, and Commercial Operations Leads across Asia-Pacific, North America, and Europe.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
30%
Product Engineering & Technical Directors
35%
Commercial Operations Leads
20%
Regulatory & Compliance Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Steel Suppliers
25%
Specialized Implement Producers
40%
Precision Technology Suppliers
15%
Global Distributors & Dealers
20%
Secondary Benchmarking & Public Trade Validation
We validated findings against official multilateral trade and standards databases, including UN Comtrade, WTO tariff data, US ITC filings, and Eurostat trade records. Corporate annual filings (10-K, SEC submissions, investor presentations), patent databases, and recognized industry and technical standards associations were used to corroborate manufacturer revenue, capacity, and technology positioning. No competitor market-research publications were used as validation sources.
Demand Modeling & Market Sizing Triangulation
We applied simultaneous Top-Down (macroeconomic, food-system, and mechanization-rate allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) triangulation. Divergences between the two approaches were reconciled against trade-flow data to produce a single defensible base-year value and forecast series.
 Farm Implements Market