 Us Agricultural Tractor Market
US Agricultural Tractor Market Outlook 2026
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 268

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Agricultural Tractor Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 9.700 B |
| 2026 | 10.22 B |
| 2027 | 10.76 B |
| 2028 | 11.33 B |
| 2029 | 11.94 B |
| 2030 | 12.57 B |
| 2031 | 13.24 B |

The US agricultural tractor market covers the manufacture, distribution and aftermarket support of wheeled and track-laying tractors and their powered implements — plowing, planting, spraying and harvesting equipment — sold to US farms, ranches and specialty growers. Value is measured at manufacturer-level revenue, excluding used-unit resale and pure rental fleets.
This analysis covers new agricultural tractor and tractor-mounted implement revenue in the United States, segmented by product type, engine power, drivetrain and end-use farm size. It includes OEM software, telematics subscriptions and dealer-led equipment subscriptions where bundled with hardware. This analysis does not cover construction or forestry tractors, lawn and garden equipment, used-tractor auction values, standalone precision-agronomy software, or drone and robotics platforms sold without a tractor chassis.
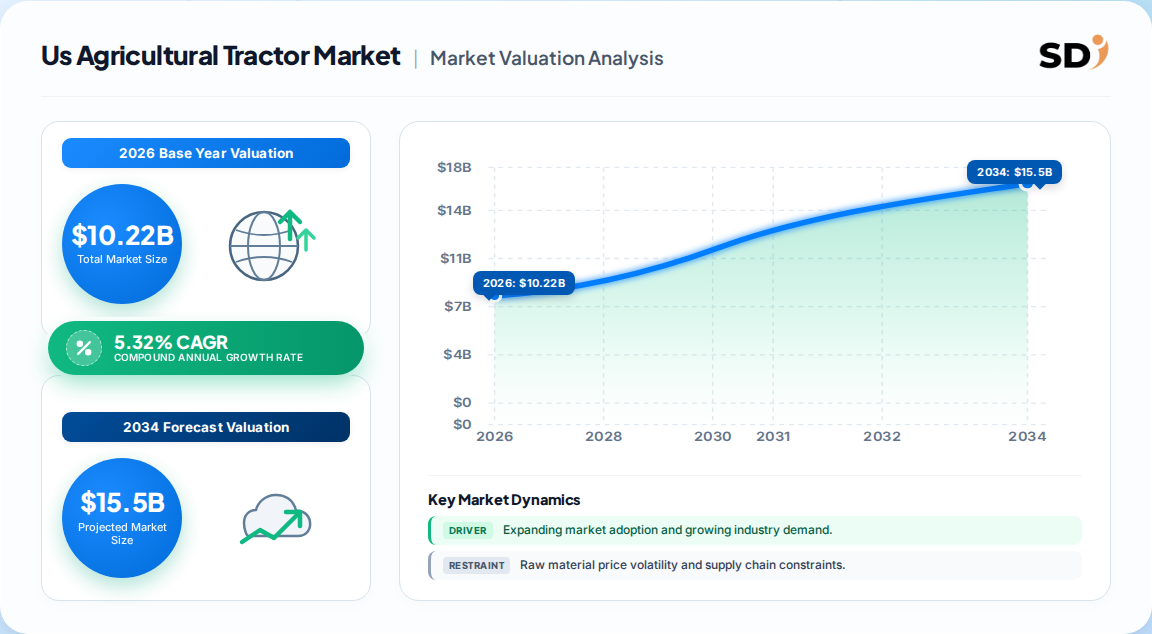
The most defensible 2026 base is USD 10.22 Billion, growing to USD 13.24 Billion by 2031 at 5.32% CAGR. The spread across published estimates is unusually wide — roughly 2.4 percentage points of CAGR — so buyers should anchor on the definitional scope rather than the headline number.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 10.22 Billion → USD 13.24 Billion | 2026 | 2031 | 5.32% | Tractor machinery incl. mounted implements, value terms | One published estimate |
| USD 10.3 Million → USD 12.6 Million | 2026 | 2033 | 2.9% | Agricultural tractors, engine-power segmentation | A competing analysis (unit likely misstated) |
| CAGR 3.47% | 2022 | 2032 | 3.47% | Tractors by type and horsepower, US only | A competing analysis |
| USD 37.0 Billion industry revenue | 2026 | — | −7.2% (2021–26) | NAICS 33311 manufacturing, incl. lawn & garden | IBISWorld (official industry statistic) |
Our analysis suggests the 5.32% figure is the most defensible for the tractor-plus-implement definition, because it is the only estimate that explicitly prices in precision-agriculture attach rates, electrification incentives and Section 232 localization. The 2.9% forecast appears to track tractor chassis alone and likely understates implement content per unit. The IBISWorld −7.2% historical figure is not contradictory: it measures total US manufacturing revenue including lawn and garden equipment, a category that collapsed post-2021. The divergence implies the implement and software layer is growing faster than the iron layer.
Segmentation matters because growth is concentrated at the edges: sprayers and above-100 HP units outgrow the aggregate, while sub-40 HP remains the revenue anchor through sheer unit volume.
| Parent segment | Children | 2025 position |
|---|---|---|
| By Product Type | Plowing & cultivating, planting machinery, sprayers, harvesting, hauling, other | Planting 30.62% share; sprayers 7.52% CAGR |
| By Engine Power | Below 40 HP, 40–100 HP, above 100 HP | Sub-40 HP largest; above-100 HP fastest |
| By Drivetrain | 2WD, 4WD, track-laying | 4WD dominant in row-crop |
| By Engine Type | ICE, hybrid, battery-electric | ICE dominant; electric fastest off small base |
| By Farm Size | Under 500 acres, 500–1,500, 1,500–3,000, above 3,000 | Above 3,000 acres drives autonomy spend |
The Midwest leads, accounting for an estimated 42% of US tractor machinery revenue, driven by corn and soybean acreage where GPS guidance has reached 75% penetration. The West follows at roughly 19%, shaped by specialty-crop electrification and drought-linked variable-rate irrigation investment.
| Region | Market Share (%) |
|---|---|
| Midwest | 0.42% |
| West | 0.19% |
| Southeast | 0.16% |
| Southwest | 0.12% |
| Northeast | 0.11% |
Regional shares are analyst estimates synthesized from acreage, crop value and mechanization intensity; the reference material provides directional rather than published state-level percentages. The implication is that dealer density and technician coverage must be concentrated in the Midwest and West to defend share, while the Southeast is the most price-sensitive and tariff-exposed region.
Precision agriculture is the single largest growth driver at an estimated +1.20% impact on CAGR, followed by labor-cost inflation (+1.00%) and electrification incentives (+0.80%). On the restraint side, high capital expenditure (−0.90%) and commodity-price volatility (−0.70%) offset roughly 1.6 points of the gross driver stack.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Precision agriculture adoption | Driver | High — 75% Midwest GPS planting | Raises tech content per unit, lifts switching costs |
| Labor cost inflation | Driver | High — +12% operator wages 2022–24 | Accelerates autonomy; payback under 3 years on large farms |
| Electrification incentives | Driver | Medium — 30% federal credit, CA diesel phase-out | Creates parallel sub-500-acre battery segment |
| Dealer subscription models | Driver | Medium — Deere, CNH dealer programs | Converts capex into recurring service revenue |
| High equipment capex | Restraint | High — acute in Southeast, Northeast | Delays replacement on mid-size farms |
| Commodity-price volatility | Restraint | High — Midwest, Southwest | Defers discretionary purchases |
| Technician skill gap | Restraint | High — 68% of dealers report shortages | Limits uptime benefits of precision implements |
| Steel/aluminum tariff pass-through | Restraint | Medium — USD 1,200–1,800 per 16-row planter | Raises unit prices, compresses dealer margins |
The balance favors growth, but only for vendors with the service network to deliver on precision promises. Our analysis suggests the technician gap is the binding constraint, not demand: 68% of dealers reporting shortages with 120+ day hiring times means unattended software is worth less than advertised. OEMs with dense service coverage convert this into a moat; new entrants cannot.
Five OEMs — Deere, CNH Industrial, AGCO, Kubota and Mahindra — anchor a high-concentration market. Differentiation has shifted from horsepower to software interoperability, dealer finance and aftermarket data capture.
| Company | HQ | Core US position | Strategic moat |
|---|---|---|---|
| Deere & Company | Moline, IL | Full-line row-crop leader; autonomous 8R, ExactShot | Deepest dealer network; proprietary data platform |
| CNH Industrial | Basildon, UK | Case IH, New Holland; broad power band | Dual-brand coverage; subscription finance |
| AGCO Corporation | Duluth, GA | Fendt, Massey Ferguson, Precision Planting | Precision-planting retrofit installed base |
| Kubota Corporation | Osaka, Japan | Compact and utility tractors | Sub-40 HP scale; strong Southeast dealer density |
| Mahindra & Mahindra | Mumbai, India | Value-tier utility tractors | Price leadership; emerging specialty niche |
Deere's advantage is structural: its dealer footprint and telematics install base make its subscription bundles harder to displace than any single product feature. AGCO's Precision Planting retrofit channel is the most credible counter-moat, because it captures growers without requiring a full tractor replacement. Kubota owns the sub-40 HP volume prize, which insulates it from row-crop commodity cycles but exposes it to tariff-driven input costs.
Procurement decisions should be scored on total cost of ownership over seven years, not sticker price. The dominant hidden costs are telematics subscription renewals, dealer service response time and software compatibility with existing implements — all of which rise with precision content.
Compliance is a real selection criterion. OECD Tractor Codes (Codes 2–10) govern official testing of performance, roll-over protective structures and noise at the driving position; buyers importing or exporting units should confirm the test report is issued by a designated national authority. State-level emissions rules, particularly California's phase-out of small diesel engines, effectively segment the market by geography and should be mapped before fleet standardization.
Switching costs are now the central procurement risk. Once a grower standardizes on a sensor-rich implement family feeding one cloud platform, the cost of changing brands exceeds the hardware differential. Buyers should negotiate data portability and aftermarket parts pricing at the point of sale, not after lock-in. Tariff pass-through of USD 1,200–1,800 per 16-row planter also means multi-year price holds are worth more than single-digit discounts.
The balance of evidence favors above-market growth concentrated in precision implements and autonomy, not in chassis volume. The 5.32% forecast is credible precisely because it prices software and service attach rather than iron shipments, and the 75% GPS planting penetration in the Midwest confirms the attach rate has room to run in the West and Southeast.
The strongest counter-argument is that commodity-price volatility and high capex could compress the replacement cycle faster than expected, pulling the CAGR toward the 2.9%–3.5% range published elsewhere. We take this seriously: the −0.90% capex restraint and −0.70% commodity restraint together offset over a quarter of gross driver impact. But the labor-cost driver is structural, not cyclical — a 12% wage increase does not reverse — and autonomy payback under three years on large farms keeps the replacement case intact even in a down-income year.
Actionable strategy:
What would change our conclusion: a sustained sub-USD 4 corn price combined with a reversal of federal electrification credits would likely push the market toward the low-3% CAGR scenario. Conversely, evidence of above-100 HP autonomy moving from pilot to fleet-scale adoption would justify a forecast above 6%. Precise sub-segment forecasting by horsepower band and state requires the full report's bottom-up model.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.32% from 2020-2034 |
| Segmentation |
|
One published estimate puts the US agricultural tractor machinery market at USD 10.22 Billion in 2026, up from USD 9.70 Billion in 2025. The forecast projects USD 13.24 Billion by 2031 at a 5.32% CAGR.
Sprayers are the fastest-growing product type at a 7.52% CAGR through 2031, while tractors above 100 HP are the fastest-growing horsepower band as autonomy scales on large row-crop farms.
The Midwest leads with an estimated 42% of US revenue, driven by corn and soybean acreage where 75% of planting was GPS-guided in 2024. The West follows at roughly 19%.
Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation and Mahindra & Mahindra lead a highly concentrated market. Differentiation now rests on telematics, dealer finance and aftermarket data rather than horsepower alone.
High equipment capital expenditure, commodity-price volatility, a technician skill gap reported by 68% of dealers, and steel and aluminum tariff pass-through together offset roughly 1.6 percentage points of gross driver impact.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Primary fieldwork comprised in-depth interviews across the US agricultural tractor value chain: component and drivetrain suppliers, specialized tractor and implement producers, precision-agronomy technology providers, dealer groups, and national distributors. Interviewees were designated decision-makers including VP-level Sourcing leads, Heads of Product and R&D, Technical Directors responsible for OECD Tractor Code compliance, and Commercial Operations Leads managing subscription and finance programs. Interviews were structured to capture capacity, pricing, attach rates and replacement-cycle intent.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 30% |
| Product & R&D Directors | 30% |
| Technical & Compliance Directors | 22% |
| Commercial Operations Leads | 18% |
| Company Type | Representation (%) |
|---|---|
| Component & Drivetrain Suppliers | 30% |
| Tractor & Implement Producers | 35% |
| Precision-Ag Technology Providers | 20% |
| Dealers & Distributors | 15% |
Secondary validation draws on official multilateral and national databases — UN Comtrade, US ITC tariff and trade data, Eurostat Access2Markets for HS 8701 tractor classifications, and OECD Tractor Codes documentation for testing and protective-structure standards — alongside corporate annual filings (10-K and investor presentations), patent databases, and recognized industry associations.
We run simultaneous top-down allocation from macroeconomic and agricultural-segment aggregates and bottom-up modeling of manufacturer capacity, unit pricing and end-use consumption by farm size. Divergences between the two models are reconciled at the segment level before forecasts are published.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |