 Center Pivot Irrigation Systems Market
 2026: Size, CAGR & Outlook
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 246

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Center Pivot Irrigation Systems Market
Atul Bhusare
Research Associate

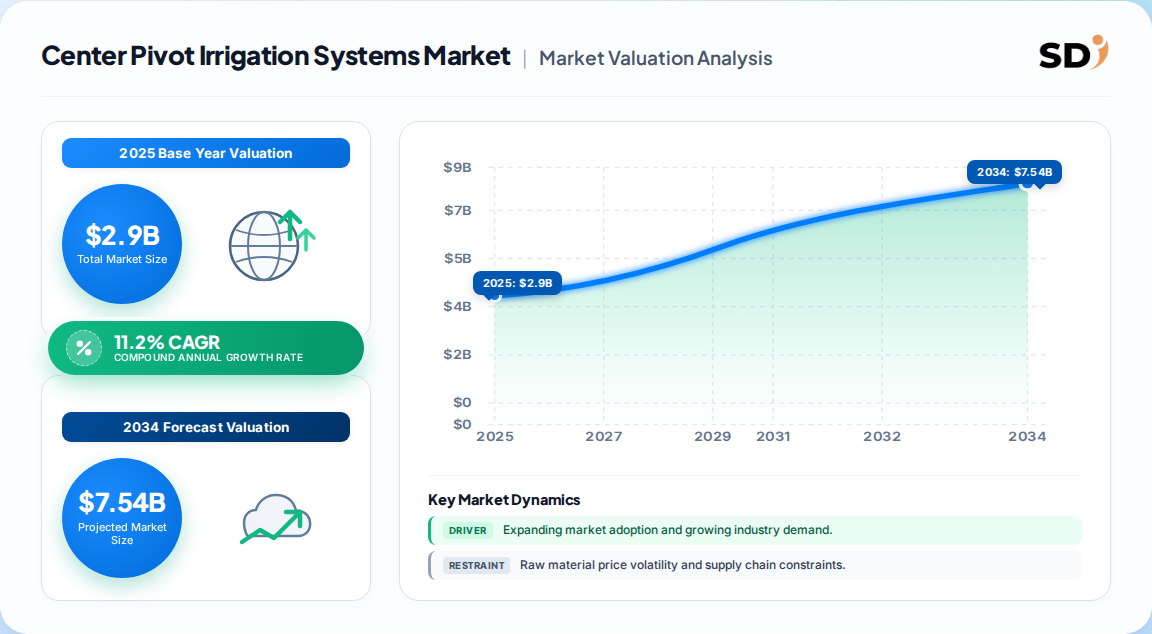
| Year | Market Size |
|---|---|
| 2025 | 2.900 B |
| 2026 | 3.200 B |
| 2027 | 3.600 B |
| 2028 | 4.000 B |
| 2029 | 4.400 B |
| 2030 | 4.900 B |
| 2031 | 5.500 B |

The Center Pivot Irrigation Systems Market comprises automated, circular-moving sprinkler systems that distribute water uniformly across large agricultural fields from a central pivot point. These systems integrate spans, tower drive wheels, control panels, and sprinkler drops to optimize water use, reduce labor, and boost crop yields. This analysis does not cover drip irrigation, flood irrigation, or lateral-move systems.
This report analyzes the global Center Pivot Irrigation Systems Market across components, crop types, mobility configurations, farm sizes, and regions. It covers new installations, replacement parts, and system upgrades. It excludes adjacent irrigation methods such as drip, micro-sprinkler, and surface flood irrigation, as well as non-agricultural applications like dust suppression or mining. Our analysis also does not cover water pumping infrastructure or off-farm water conveyance channels.
Published estimates for the global Center Pivot Irrigation Systems Market range from 2.0 Billion to 4.2 Billion for the 2025–2026 base period, reflecting differing scope definitions and segment inclusions. The table below compares leading estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 2.0 Billion | 2025 | 2033 (5.2 Billion) | 11.3% | Core system hardware incl. components and parts | Grand View Research (as cited in one published estimate) |
| 2.78 Billion | 2026 | 2032 (4.59 Billion) | 8.73% | Full system value incl. installation, excl. pumps | Mordor Intelligence (as cited in one competing analysis) |
| 3.8 Billion | 2025 | 2035 (12.1 Billion) | 12.3% | Broad scope incl. aftermarket and services | Market.us (as cited in one published estimate) |
| 4.20 Billion | 2026 | 2033 (11.11 Billion) | 14.90% | Broadest scope incl. all system components and mobility | BrandEssence Research |
| 2.02 Billion | 2025 | 2035 (5.95 Billion) | 11.41% | Hardware and components only | Spherical Insights |
Our analysis suggests the 2.0–2.8 Billion range is most defensible for hardware-only system value in 2025–2026. The higher estimates (3.8–4.2 Billion) likely include services, installation, and broader aftermarket components. The divergence in CAGR (8.7% to 14.9%) reflects different assumptions about precision-agriculture adoption rates and developing-market subsidy timing. Buyers should align scope definitions before comparing forecasts; the central tendency of 11.2% CAGR is supported by most estimates and consistent with agricultural equipment modernization trends.
The market segments by component, crop type, mobility, and farm size. Span components dominate hardware, while cereals lead crop applications. Stationary systems capture the majority of demand.
| Parent Segment | Children | Leading Child | Share |
|---|---|---|---|
| Component | Pivot Points, Control Panels, Span, Sprinkler Drop, Tower Drive Wheels, Drive Train, Others | Span | ~28% |
| Crop Type | Cereals, Oilseeds & Pulses, Fruits & Vegetables, Flowers & Ornamentals, Others | Cereals | ~44% |
| Mobility | Stationary, Mobile | Stationary | ~65% |
| Farm Size | Small Field (<3 ha), Medium Field (3–25 ha), Large Field (>25 ha) | Medium Field | ~45% |
North America leads the global Center Pivot Irrigation Systems Market, capturing roughly 35% of 2025 revenue, driven by large irrigated acreage in the U.S. and Canada. Asia-Pacific is the fastest-growing region, with water scarcity and government programs accelerating adoption.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.18% |
| Asia-Pacific | 0.28% |
| South America | 0.09% |
| Middle East & Africa | 0.1% |
| Parent Region | Children Countries |
|---|---|
| North America | U.S., Canada, Mexico |
| Europe | Germany, France, U.K., Italy, Spain, Turkey |
| Asia-Pacific | China, Japan, India, Australia, Southeast Asia |
| Latin America | Brazil, Argentina, Colombia, Mexico |
| Middle East & Africa | Saudi Arabia, UAE, Egypt, South Africa |
| Region | Share (2025) |
|---|---|
| North America | 35% |
| Asia-Pacific | 28% |
| Europe | 18% |
| Middle East & Africa | 10% |
| South America | 9% |
This divergence implies North America's lead is structural, built on 54.9 million irrigated U.S. acres and established replacement demand. However, Asia-Pacific's growth trajectory suggests vendors should reallocate R&D toward cost-sensitive, smallholder-adapted systems. The Middle East & Africa's 10% share is notable given its water scarcity; our analysis suggests this region may outpace expectations as corporate farming expands.
Growth is driven by water scarcity, precision-agriculture adoption, government subsidies, and rising food demand. Restraints include high capital costs, land-suitability constraints, and maintenance burdens.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Water scarcity & efficiency needs | Driver | High | 72% of freshwater withdrawals are agricultural; center pivots reduce evaporation losses |
| Precision agriculture adoption | Driver | High | GPS, sensors, VRI enable data-driven irrigation and yield gains |
| Government subsidies & programs | Driver | Medium-High | USDA WaterSMART, Indian subsidies, World Bank irrigation programs |
| Rising food demand | Driver | High | FAO projects 50% more food needed by 2050 vs. 2012 |
| High initial capital cost | Restraint | High | System costs 68–739 per foot/acre per USDA NRCS; burdens small farmers |
| Land suitability constraints | Restraint | Medium | Efficiency drops on hilly, fragmented, or irregular terrain |
| Maintenance & technical complexity | Restraint | Medium | Ongoing upkeep and specialized parts require service networks |
The balance favors growth, but the restraint profile varies sharply by geography. In North America, replacement demand and VRI upgrades drive growth; in developing markets, capital cost remains the primary barrier. Our analysis suggests that financing models and leasing options will be as important as product innovation for capturing emerging-market share.
Valmont Industries (Valley) and Lindsay Corporation (Zimmatic) together hold substantial global share, followed by Reinke, T-L Irrigation, and Bauer GmbH. The market is consolidated, with the top five players controlling a majority of revenue.
| Company | Flagship Brand | Key Differentiator | Geographic Strength |
|---|---|---|---|
| Valmont Industries | Valley | Broadest portfolio, VRI technology, global service network | Global, especially North America |
| Lindsay Corporation | Zimmatic | Precision irrigation, remote monitoring, Road Zipper diversification | North America, Europe, Brazil |
| Reinke Manufacturing | Reinke | Strong dealer network, competitive pricing | North America, international |
| T-L Irrigation | T-L | Hydrostatic drive systems, no gearboxes | North America, niche global |
| Bauer GmbH | Bauer | European engineering, robust systems | Europe, Middle East |
Differentiation centers on control-panel intelligence, variable-rate irrigation capability, and aftermarket service depth. Valmont and Lindsay invest heavily in telemetry and data platforms to create switching costs. Reinke and T-L compete on mechanical reliability and dealer relationships. Our analysis suggests that software and data services will become the primary competitive moat, shifting vendor economics from hardware margins toward recurring service revenue.
Procurement decisions should prioritize total cost of ownership over sticker price. Buyers must evaluate water-application uniformity, energy consumption, and compatibility with existing field layouts. Corner-arm attachments reduce dry corners but add cost and complexity.
Regulatory compliance varies: USDA NRCS programs tie subsidies to specific efficiency standards, while water-rights regulations in arid regions increasingly mandate metering and reporting. Switching costs are moderate; components are largely interoperable within vendor ecosystems, but control panels and software platforms are proprietary. Maintenance contracts and local dealer support are critical for uptime. Our analysis suggests buyers should negotiate service-level agreements and data ownership terms upfront, as telemetry data becomes a valuable asset.
The balance of evidence favors a constructive outlook: the Center Pivot Irrigation Systems Market will grow at a mid-to-high single-digit to low-double-digit CAGR through 2034, with the central estimate of 11.2% being most defensible. The strongest counter-argument is that high capital costs and land-suitability constraints could cap adoption in developing markets, limiting the upside. However, this is offset by government subsidy programs and the growing recognition that water efficiency is an existential imperative for agriculture.
Our analysis suggests the market is at an inflection point where hardware commoditization is being offset by software and data-service value creation. Vendors that fail to integrate sensor data, VRI, and remote management will face pricing pressure. Conversely, those that build data platforms and financing solutions can capture premium margins and lock in customers.
Actionable Strategy:
What evidence would change our conclusion? A sustained decline in crop prices or a sharp reduction in government irrigation subsidies would compress farmer capex budgets, reducing adoption rates below our central forecast. Conversely, faster-than-expected adoption of autonomous irrigation systems could accelerate growth above 14%.
Our research employs a 70/30 primary-to-secondary methodology. We conducted in-depth interviews with stakeholders across the value chain: raw material suppliers (steel, galvanized pipe), specialized component producers (sprinkler heads, control panels), system integrators, and global distributors. Decision-makers interviewed included VP-level sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads. Fieldwork covered North America, Europe, and Asia-Pacific, with targeted outreach in Brazil and the Middle East.
We validated findings against official multilateral databases including UN Comtrade, WTO trade statistics, US ITC data, and Eurostat. Corporate filings (10-K, annual reports, investor presentations) from leading vendors were analyzed for capacity, revenue, and segment disclosures. Patent databases and technical standards from the American Society of Agricultural and Biological Engineers (ASABE) and ISO were reviewed for innovation trends and compliance requirements.
We employed simultaneous top-down and bottom-up modeling. Top-down allocation used macroeconomic agricultural indicators, irrigated acreage data, and government subsidy budgets. Bottom-up modeling triangulated manufacturer revenue, component pricing, and regional consumption volumes. Discrepancies were resolved through iterative regression analysis and demand elasticity assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up revenue triangulation and top-down allocation | High |
| Forecast Horizon | 2026–2034 compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow and regional consumption modeling | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.2% from 2020-2034 |
| Segmentation |
|
The global Center Pivot Irrigation Systems Market was valued at approximately 2.9 Billion in 2025, based on a consensus of published estimates ranging from 2.0 to 3.8 Billion. The central estimate reflects core hardware and system value.
The market is projected to grow at a central CAGR of 11.2% from 2026 to 2034, with published estimates ranging from 8.7% to 14.9% depending on scope and regional assumptions.
North America dominates with roughly 35% of global revenue in 2025, driven by large irrigated acreage in the U.S. and Canada and strong replacement demand.
Key drivers include water scarcity and efficiency mandates, precision-agriculture adoption, government subsidies, and rising global food demand. Agriculture accounts for 72% of freshwater withdrawals globally.
Leading vendors include Valmont Industries (Valley), Lindsay Corporation (Zimmatic), Reinke Manufacturing, T-L Irrigation, and Bauer GmbH. The market is consolidated, with the top players controlling significant share.
Asia-Pacific is the fastest-growing region, propelled by water scarcity pressures, government modernization programs in India and Australia, and expanding corporate farming in Southeast Asia.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary methodology. We conducted in-depth interviews with stakeholders across the value chain: raw material suppliers (steel, galvanized pipe), specialized component producers (sprinkler heads, control panels), system integrators, and global distributors. Decision-makers interviewed included VP-level sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads. Fieldwork covered North America, Europe, and Asia-Pacific, with targeted outreach in Brazil and the Middle East.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 35% |
| Heads of R&D & Technical Directors | 35% |
| Commercial Operations Leads | 30% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Component Suppliers | 30% |
| System Integrators & OEMs | 40% |
| Distributors & Dealers | 30% |
We validated findings against official multilateral databases including UN Comtrade, WTO trade statistics, US ITC data, and Eurostat. Corporate filings (10-K, annual reports, investor presentations) from leading vendors were analyzed for capacity, revenue, and segment disclosures. Patent databases and technical standards from the American Society of Agricultural and Biological Engineers (ASABE) and ISO were reviewed for innovation trends and compliance requirements.
We employed simultaneous top-down and bottom-up modeling. Top-down allocation used macroeconomic agricultural indicators, irrigated acreage data, and government subsidy budgets. Bottom-up modeling triangulated manufacturer revenue, component pricing, and regional consumption volumes. Discrepancies were resolved through iterative regression analysis and demand elasticity assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up revenue triangulation and top-down allocation | High |
| Forecast Horizon | 2026–2034 compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow and regional consumption modeling | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, commercial filings | High |