 Surgical Retractor Market
 Size, Trends & Forecast 2026
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 225

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Surgical Retractor Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 2.520 B |
| 2026 | 2.670 B |
| 2027 | 2.850 B |
| 2028 | 3.040 B |
| 2029 | 3.240 B |
| 2030 | 3.460 B |
| 2031 | 3.690 B |

The surgical retractor market covers instruments that hold an incision or operative site open during surgery, preserving visibility and tissue exposure. It spans handheld and self-retaining devices in reusable stainless steel, titanium and plastic/disposable formats, sold to hospitals and ambulatory surgical centers across neurosurgery, abdominal, cardiovascular, orthopedic and gynecologic procedures.
This analysis covers global demand for handheld and self-retaining surgical retractors by product type, application, material and end use, with regional breakdowns and vendor positioning. This analysis does not cover adjacent surgical instrumentation such as scissors, forceps, trocars, staplers, or robotic surgical platforms, nor does it cover sterile processing consumables independently of retractor systems.
Estimates cluster tightly around the mid-2-Billion range for 2025, but diverge meaningfully on forward trajectory — a gap driven by differing forecast horizons and base-year treatment rather than genuine disagreement on current demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 2.52 Billion | 2025 | 2035 | 6.7% | Global surgical retractors, all formats | One published estimate |
| 2.57 Billion | 2025 | 2030 | 7.3% | Global surgical retractors, handheld + self-retaining | A competing analysis |
| 2.76 Billion | 2026 | 2030 | 7.2% | Global, broader instrument definition | A competing analysis |
Our analysis treats the 2.52 Billion / 6.7% base case as most defensible: it is anchored to a documented 2.39 Billion 2024 revenue figure and a decade-long horizon that absorbs near-term capital-spending volatility. The higher-CAGR reading likely reflects a shorter window that captures the ASC migration inflection more aggressively. Importantly, both agree the market adds roughly 1.5–2.3 Billion in absolute value over their respective horizons — the strategic signal, not the decimal, is what buyers should act on.
Segmentation follows four axes — product type, application, material and end use — with material choice emerging as the sharpest commercial differentiator between price-sensitive and workflow-driven buyers.
| Parent segment | Children |
|---|---|
| By Product Type | Handheld (Ribbon, Volkmann, Senn, Gelpi, Malleable); Self-Retaining (Balfour, Bookwalter, Weitlaner, O'Connor-O'Sullivan, Fan) |
| By Application | Neurosurgery, Abdominal Surgery, Cardiovascular, Orthopedic, Obstetrics & Gynecology, Other |
| By Material | Stainless Steel, Titanium, Plastic / Disposable |
| By End Use | Hospitals, Ambulatory Surgical Centers, Other End Users |
Our analysis suggests the material axis is where competitive advantage is shifting. Stainless steel remains the volume backbone but is expected to grow at only ~5.6% CAGR under procurement pressure, while plastic/disposable formats outpace the blended market on infection-control and turnover economics.
North America leads global surgical retractor revenue, supported by high procedure volumes and concentrated ASC infrastructure. Asia Pacific is the fastest-growing region, driven by surgical capacity expansion and infrastructure investment rather than price-led demand.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.24% |
| Asia-Pacific | 0.29% |
| Latin America | 0.06% |
| Middle East & Africa | 0.07% |
This divergence implies two different commercial playbooks. In North America, value accrues through procedure-specific disposable kits and ASC channel access; in Asia Pacific, durable reusable fleets still dominate tender frameworks, so share gains depend on distribution depth and localized manufacturing rather than premium pricing.
Procedure volume growth and outpatient migration are the dominant demand engines, while constrained healthcare capital expenditure is the primary brake on premium-mix acceleration.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising global surgical volumes | Driver | High | ~313 million procedures annually sustain baseline retractor consumption |
| ASC procedure migration | Driver | High | ASC volume per Medicare beneficiary grew 3.5% in 2024, favoring disposable and self-retaining formats |
| Single-use innovation | Driver | Medium-High | Integrated illumination and smoke evacuation address infection-control protocols |
| Uneven health capital investment | Restraint | High | OECD health capex ~0.6% of GDP (2021–2024) favors durable reusables over premium lines |
| Global surgical access gap | Restraint | Medium-High | ~160 million unmet procedures annually limit addressable breadth in low-income markets |
The balance favors growth, but not uniform growth. Our analysis suggests the restraint is really a price-mix constraint: volume demand is robust, yet capital-starved systems will trade down to standardized stainless steel, capping blended ASP escalation even as premium disposable lines expand in high-throughput outpatient networks.
B. Braun/Aesculap leads with over 5.5% share, but the top five players together hold only ~15% — an unusually fragmented structure for a mature instrument category.
| Vendor | Position | Basis of differentiation |
|---|---|---|
| B. Braun / Aesculap | Market leader (~5.5%+) | Broad reusable portfolio, surgical workflow integration |
| Stryker | Top-five | Orthopedic and procedure-specific configuration depth |
| Medtronic | Top-five | Cross-portfolio pull-through in hospital accounts |
| Thompson Retractor | Top-five | Self-retaining systems for complex open surgery |
| CooperSurgical | Top-five | Gynecologic and obstetrics procedure focus |
Differentiation rests less on instrument steel than on procedural fit and channel access. With 85% of share dispersed across smaller and regional players, moats are built through ASC distribution relationships, procedure-specific kit design, and reprocessing-validated documentation rather than brand alone.
Selection criteria should prioritize clinical utility and total cost of ownership over unit price. Buyers must weigh reprocessing burden, sterilization validation against AAMI ST79 and ISO 17664 standards, and the labor cost of setup and turnover — factors that often dwarf the sticker difference between reusable and disposable formats.
Procurement risk concentrates in supply continuity and standardization. Single-vendor tenders for reusable fleets create switching costs at instrument-tray standardization, while disposable adoption introduces single-source dependency and shelf-life management. Operators should validate that any disposable platform integrates into existing perioperative workflows without retraining overhead.
Regulatory compliance is non-negotiable: device classification, sterility assurance and reprocessing instructions must be documented before formulary approval, particularly for ASCs with limited sterile processing capacity. Our analysis suggests buyers who model total procedural cost — not unit cost — systematically capture better value in high-turnover outpatient settings.
The balance of evidence favors a mix-shift thesis over a volume thesis. Absolute procedure growth is reliable but modest; the disproportionate value creation sits in disposable and self-retaining configurations serving outpatient workflows, where differentiation on illumination, smoke evacuation and setup speed supports premium pricing.
The strongest counter-argument is that capital constraints across OECD health systems will suppress premium adoption and push buyers toward durable stainless steel fleets, capping blended ASP growth near 5–6%. That is credible — but it describes hospital procurement, not ASCs, and the ASC channel is growing faster than the rest. The two forces can coexist: reusables defend hospital volume while disposables expand outpatient value.
Actionable strategy:
What would change this conclusion: a sustained reversal in ASC migration rates, or regulatory tightening that raises disposable-device approval friction enough to restore reusable economics. Absent those signals, the mix-shift case holds.
While this overview frames the strategic direction, precise sub-segment forecasting — by material, application and country — requires the full report's granular dataset and vendor-level modeling.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.7% from 2020-2034 |
| Segmentation |
|
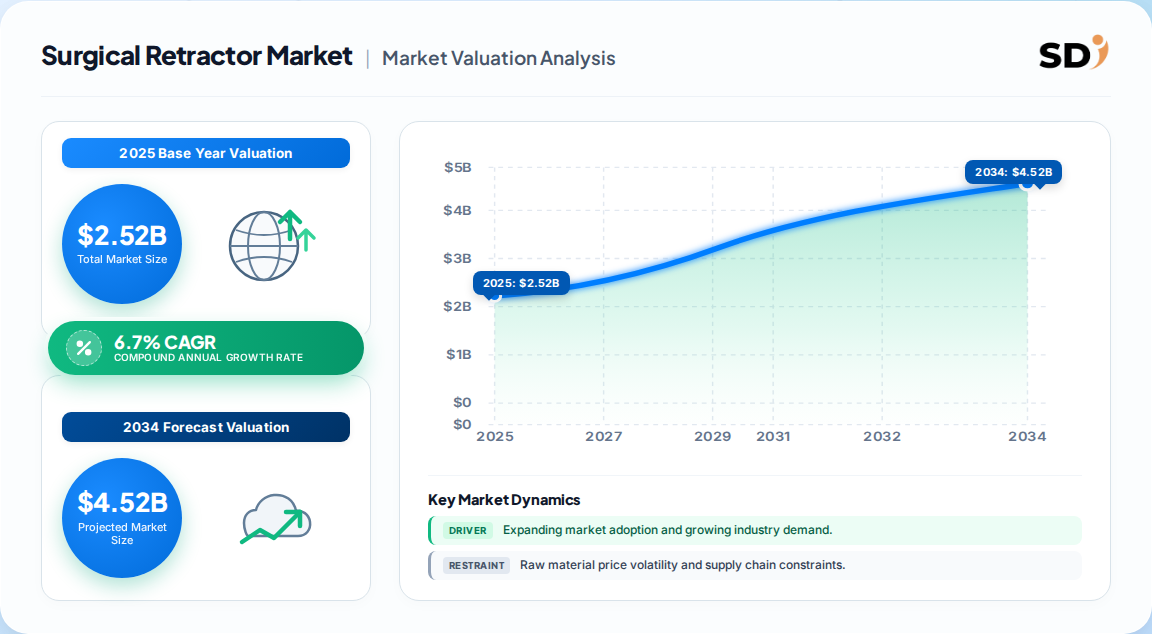
The global surgical retractor market was valued at approximately 2.52 Billion in 2025, with a competing analysis placing it near 2.57 Billion. Both readings reflect consistent baseline demand from roughly 313 million annual surgical procedures worldwide.
The base-case forecast projects a 6.7% CAGR from 2026 to 2035, reaching 4.80 Billion by 2035. A shorter-horizon alternative estimate uses 7.3% CAGR, reflecting faster ambulatory surgical center migration.
North America leads regional revenue on high procedure volumes and concentrated ASC infrastructure. Asia Pacific is the fastest-growing region, driven by surgical capacity expansion and healthcare infrastructure investment rather than premium pricing.
B. Braun/Aesculap leads with over 5.5% share, followed by Stryker, Medtronic, Thompson Retractor and CooperSurgical. Together the top five hold only about 15%, indicating a highly fragmented competitive landscape.
Single-use retractors with integrated illumination and smoke evacuation address post-pandemic infection-control protocols, reduce sterile-processing workload and enable faster operating-room turnover — advantages that matter most in high-volume outpatient settings.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain with raw material and medical-grade steel suppliers, specialized retractor producers, contract manufacturing and finishing specialists, and global surgical instrument distributors. Within these organizations we engaged decision-makers including VP-level Sourcing leads, Heads of Surgical Instrument R&D, Technical Directors responsible for sterilization validation, and Commercial Operations Leads managing ASC and hospital channels.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement VPs | 35% |
| Surgical Instrument R&D Heads | 30% |
| Sterilization & Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Medical-Grade Material & Component Suppliers | 30% |
| Specialized Retractor Manufacturers | 40% |
| Contract Manufacturing & Finishing | 15% |
| Global Surgical Instrument Distributors | 15% |
Estimates are cross-checked against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings and investor presentations (10-K and equivalent disclosures), patent databases tracking retractor design activity, and recognized technical standards bodies including ISO and AAMI sterilization and reprocessing guidelines.
We run simultaneous Top-Down allocation (macroeconomic surgical volume data and procedure-segment allocation) and Bottom-Up modeling (manufacturer capacity, product pricing and end-use consumption). Divergences between the two approaches are reconciled against trade-flow and corporate-revenue evidence before a consensus figure is adopted.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |