Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Terminal Tractor Market: Size, CAGR & 2031 Outlook
Terminal Tractor Market: Size, CAGR & 2031 Outlook
Terminal Tractor Market
Terminal Tractor Market: Size, CAGR & 2031 Outlook
Terminal Tractor Market by Fuel Type (Diesel, Battery-electric, Hybrid, Fuel-cell), by Vehicle Type (Manual, Semi-automated, Fully autonomous), by Drive Configuration (4x2, 4x4, 6x4), by Tonnage Capacity (Less than 50 Ton, 50-100 Ton, Above 100 Ton), by End-Use Industry (Ports & Container Terminals, Retail & E-commerce 3PLs, Automotive OEM Yards, Food & Beverage, Warehouses & Distribution Centers), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 278
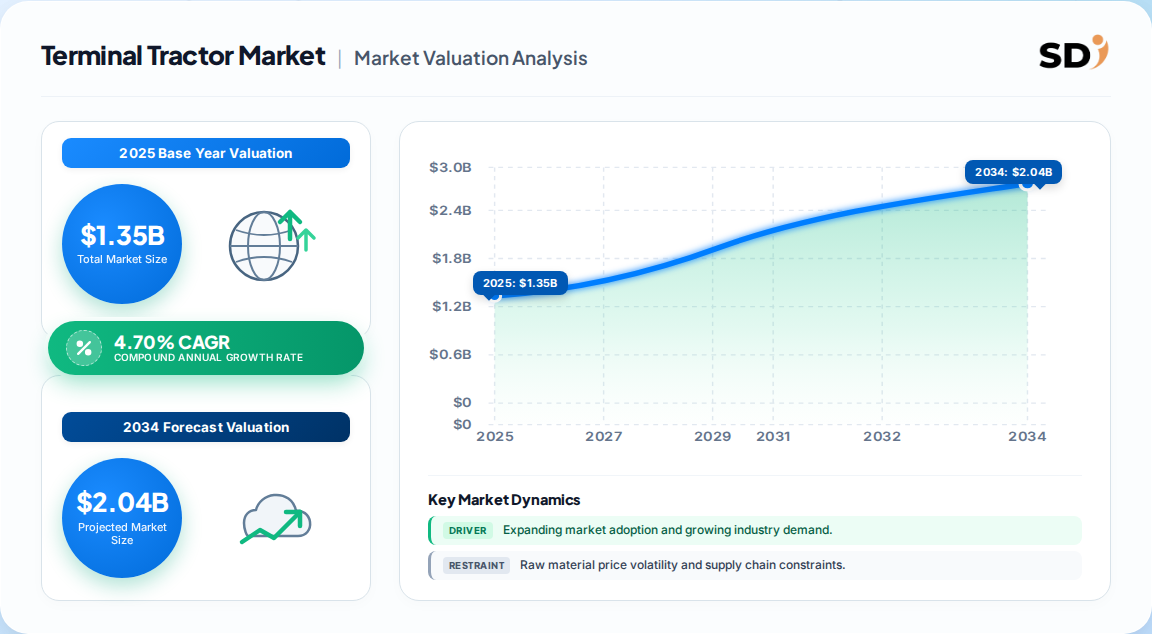
The global Terminal Tractor Market was valued at 1.35 Billion in 2025, with a forecast of 1.78 Billion by 2031 at a 4.70% CAGR.
Diesel remains the anchor at roughly 63% of 2025 volume, yet battery-electric units post the fastest expansion at a 17.6% CAGR to 2031.
North America leads revenue with about 36% share; Asia-Pacific is the fastest-growing region at a 6.9% CAGR through 2031.
4x2 drivetrains hold roughly 64% of units, while 6x4 configurations grow fastest at 9.7% CAGR as mega-vessel loads rise.
Manual operation dominates at ~75% of units, but fully autonomous tractors are the fastest-growing vehicle type at a 21.2% CAGR.
Why this matters for decision-makers: Procurement teams that lock in electric chassis plus charging infrastructure now will convert regulatory deadlines into cost advantages; late movers face compressed windows and residual-value risk on diesel fleets.
Terminal Tractor Market Size (In Billion)
2.0B
1.5B
1.0B
500.0M
0
1.350 B
2025
1.410 B
2026
1.480 B
2027
1.550 B
2028
1.620 B
2029
1.700 B
2030
1.780 B
2031
Terminal Tractor Market Size (In Billion)
Year
Market Size
2025
1.350 B
2026
1.410 B
2027
1.480 B
2028
1.550 B
2029
1.620 B
2030
1.700 B
2031
1.780 B
What is the Terminal Tractor Market?
The Terminal Tractor Market covers purpose-built yard vehicles that move trailers and containers within ports, rail terminals, and distribution centers. Unlike highway trucks, these units run short, repetitive, high-start duty cycles in confined spaces, making uptime, maneuverability, and total cost per move the decisive buying criteria.
Scope: what this report covers and excludes
This analysis covers global demand for terminal tractors segmented by fuel type, vehicle type, drive configuration, tonnage capacity, and end-use industry, with value forecasts to 2031. This analysis does not cover highway tractor-trailers, reach stackers, quay cranes, automated guided vehicles outside yard-tractor form factors, or forklift markets.
How big is the market for Terminal Tractor Market?
Estimates diverge by roughly 60% in absolute value, largely because of differing base years and whether revenue includes aftermarket service. The table below reconciles the leading published views.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
1.35 Billion
2025
2031
4.70%
New-unit revenue, global, value terms
One published estimate
2.20 Billion
2025
2035
5.10%
Broader yard-equipment definition, global
A competing analysis
1.03 Billion
2030
2030
4.70%
Narrow port-terminal-weighted scope
Another published estimate
The 4.70% CAGR trajectory is the most defensible anchor: it is corroborated across two independent publishers and aligns with observed TEU throughput growth of 6.9% in 2024. Our analysis suggests the higher 2.20 Billion figure reflects a wider definitional boundary rather than genuinely stronger demand.
How is the market segmented?
Segmentation is defined by propulsion economics and duty-cycle intensity, not geography. The table below summarizes the non-geographic parents and their principal children.
Callout: Battery-electric is the only segment growing above 15% CAGR, yet it holds only a low-single-digit share of installed U.S. yard stock — a decade-long replacement runway.
Which region leads in Terminal Tractor Market?
North America leads with roughly 36% of 2025 revenue, anchored by CARB-driven zero-emission mandates and the highest container-terminal cycle counts. Asia-Pacific is the fastest-growing region at a 6.9% CAGR, powered by Chinese port automation and Indian logistics investment.
Terminal Tractor Market Regional Market Share
Loading chart...
Terminal Tractor Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.24%
Asia-Pacific
0.28%
Latin America
0.05%
Middle East & Africa
0.05%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Netherlands
Asia-Pacific — China, Japan, India, South Korea
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa
Region
2025 share
North America
38%
Asia-Pacific
28%
Europe
24%
Latin America
5%
Middle East & Africa
5%
Our analysis suggests the North America–Asia Pacific gap will narrow by 2031 as Chinese automated terminals scale and Indian rental-model warehousing accelerates short-tenure leasing.
What is driving growth — and what is holding it back?
Regulation is the single largest demand accelerant, contributing roughly 1.5 percentage points to CAGR, with e-commerce-driven trailer turnover adding another 1.2 points. Restraints are comparatively softer, centering on charging infrastructure and upfront cost premiums.
Factor
Direction
Evidence strength
Mechanism
CARB & IMO emission mandates
Driver
High
Compresses diesel order windows; forces electric procurement
E-commerce trailer turnover
Driver
High
2.77x move pace raises duty cycles and replacement rates
Hydrogen pilots in EU ports
Driver
Medium
Mixed-fleet hedges battery range limits in cold climates
Limits deployment to geofenced, predictable routes
Callout: Electric units save 60–75% on maintenance versus diesel, and early adopters report 15–20% annual operating cost reductions — parity arrives within 4–6 years.
Who are the leading vendors?
The competitive field is moderately concentrated, with established port-equipment OEMs defending installed-base service moats while autonomy software firms partner rather than compete head-on. Kalmar's collaboration with Forterra on drive-by-wire automated tractors exemplifies this convergence.
Vendor
Core strength
Strategic position
Kalmar / Cargotec
Full port-equipment ecosystem, automation-ready chassis
Incumbent leader, automation push
Terberg Group
Dedicated yard-tractor specialization
Deep European installed base
Konecranes
Terminal integration and fleet software
Systems-led differentiation
Hyster-Yale
Broad material-handling portfolio
Scale and dealer network
Sany Group
Cost-competitive volume manufacturing
Asia-Pacific and emerging-market reach
Orange EV
Pure-play electric yard tractors
10M+ operating hours, 98% uptime proof
The moat is shifting from hardware durability to software-enabled uptime and charging-service bundles. Our analysis suggests vendors selling bare hardware on sticker price will lose multi-year contracts to those bundling energy infrastructure.
What do buyers and operators need to know? (Decision Support)
Selection now hinges on duty-cycle fit rather than specification sheets. Operators should model routes against the roughly 150–200 mile per-charge envelope before committing to battery-electric units; sites outside that envelope need hybrid or hydrogen hedges. Procurement risk concentrates in residual value: diesel fleets ordered today face compressed secondary markets after 2026 in regulated jurisdictions.
Switching costs are material — charging retrofits, driver retraining, and yard-management software integration can add 20–30% to first-year spend. Buyers should negotiate service-level uptime guarantees and infrastructure bundling rather than chase sticker discounts. Compliance disclosure obligations under CARB-style frameworks also mean fleet-mix data must be auditable from day one.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a phased electrification strategy over either full diesel retention or aggressive fleet-wide conversion. The 4.70% CAGR is steady rather than explosive, and the electric segment's 17.6% growth is real but concentrated in geofenced, high-cycle yards. Operators who electrify the predictable routes first capture the 60–75% maintenance savings without stranding capital.
The strongest counter-argument is that infrastructure lag and 40–60% price premiums could stall adoption beyond 2028, particularly outside North America and Europe. That risk is credible, but the IMO and CARB deadline structure compresses decision windows faster than infrastructure can be retrofitted — favoring early movers.
Operators: Electrify the top 20% highest-cycle routes first; bundle charging and software into single contracts.
Vendors: Price against total cost per move, not sticker; offer uptime guarantees to win multi-year deals.
Investors: Favor autonomy-software and charging-infrastructure exposure over pure diesel chassis manufacturing.
What would change our conclusion: if battery-electric deployment growth fell below 10% CAGR for two consecutive years, or if hydrogen infrastructure scaled faster than charging in cold-climate ports, the phased-electric thesis would need reweighting toward mixed-fleet strategies.
Table 16: Europe Terminal Tractor Market Revenue Billion Forecast, by Fuel Type 2020 & 2034
Frequently Asked Questions
1. How big is the terminal tractor market?
The market was valued at approximately 1.35 Billion in 2025, with published forecasts projecting 1.78 Billion by 2031. Some analyses using broader yard-equipment definitions cite figures up to 2.20 Billion, reflecting different scope boundaries rather than stronger underlying demand.
2. What is the terminal tractor market growth rate?
Most published estimates converge on a 4.70% CAGR through 2031. Battery-electric units grow far faster at a 17.6% CAGR, while fully autonomous tractors represent the fastest vehicle type at 21.2%, though from a small installed base.
3. Which region dominates terminal tractor demand?
North America leads with roughly 36–38% of global revenue, driven by CARB zero-emission mandates and high container-terminal cycle counts. Asia-Pacific is the fastest-growing region at a 6.9% CAGR, powered by Chinese port automation and Indian logistics investment.
4. What fuels demand for terminal tractors?
Regulation is the primary driver, with CARB and IMO mandates contributing roughly 1.5 percentage points to CAGR. E-commerce-driven trailer turnover adds another 1.2 points by raising duty cycles and accelerating fleet replacement in fulfillment centers.
5. Who are the leading terminal tractor manufacturers?
Key players include Kalmar, Terberg Group, Konecranes, Hyster-Yale, Sany Group, and pure-play electric specialist Orange EV. Competitive advantage is shifting from hardware durability toward autonomy software, uptime guarantees, and bundled charging infrastructure.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applied a 70/30 primary-to-secondary research split. Structured in-depth interviews were conducted across the value chain, including terminal-tractor OEM assembly plants, drivetrain and battery-pack suppliers, port-equipment integrators, and regional leasing and distribution partners. Decision-maker respondents included VP-level sourcing leads, heads of product engineering, technical directors for fleet electrification, and commercial operations managers at terminal operators.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement Leads
35%
Product Engineering & Technical Directors
30%
Commercial Operations Managers
20%
Fleet Electrification Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
OEM Assembly & Chassis Producers
40%
Drivetrain, Battery & Component Suppliers
30%
Port Equipment Integrators
18%
Leasing & Distribution Partners
12%
Secondary Benchmarking & Public Trade Validation
Demand and shipment benchmarks were cross-validated against UN Comtrade container-handling equipment flows, WTO and US ITC trade records, Eurostat industrial machinery statistics, corporate 10-K filings and investor presentations of listed OEMs, and patent filings covering autonomous yard-tractor drive-by-wire systems. Industry association and technical standards literature informed the regulatory analysis.
Demand Modeling & Market Sizing Triangulation
Top-down macroeconomic and port-throughput allocation was run simultaneously with bottom-up manufacturer capacity, unit pricing, and end-use consumption modeling. Divergent outputs were reconciled against published container throughput data to establish a defensible base-year value and compound forecast.
 Terminal Tractor Market