 Us Agricultural Adjuvants Market
US Agricultural Adjuvants Market: 2034 Outlook & Analysis
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 227

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Agricultural Adjuvants Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 631.0 M |
| 2026 | 664.0 M |
| 2027 | 698.0 M |
| 2028 | 733.0 M |
| 2029 | 771.0 M |
| 2030 | 810.0 M |
| 2031 | 852.0 M |

The US agricultural adjuvants market covers non-pesticidal additives — surfactants, oils, drift control agents, water conditioners, defoamers and activators — sold to enhance the performance of herbicides, fungicides and insecticides applied to US field, specialty and horticultural crops.
This analysis covers adjuvant products sold into US agricultural end-uses, segmented by product type, application, source, formulation and crop type, with state-level demand allocation across the Northeast, Midwest, South and West. This analysis does not cover the underlying pesticide active-ingredient market, fertilizer additives, non-agricultural adjuvants (industrial, turf-only and household), or spray equipment hardware.
The market is genuinely contested: published 2024–2025 base values range from about USD 514 Million to USD 631 Million, a spread too wide to be explained by definition alone and largely attributable to differing treatment of in-can/formulation additives versus tank-mix products.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 589.6 Million | 2023 | 2030 | 3.1% | Full adjuvant market incl. activator and utility | One published estimate |
| 514.25 Million | 2024 | 2035 | 4.67% | Tank-mix-weighted adjuvant spend | A competing analysis |
| 631.3 Million | 2025 | 2034 | 5.12% | Full adjuvant market, type/crop/application split | A competing analysis |
The 5.12% track is the most defensible for planning. Our analysis suggests the 3.1% figure reflects a 2023 base captured before the current cycle of biological and drift-reduction formulary additions, while the 4.67% series is credible but appears to under-count in-can adjuvant value embedded in premix formulations. Buyers should treat USD 630–640 Million as the 2025 anchor and 5.0–5.2% as the planning CAGR.
The segmentation is product-led: activator adjuvants carry roughly three-quarters of value, utility adjuvants the balance, and application mix tilts heavily toward herbicide programs.
| Parent segment | Children |
|---|---|
| Product type | Activator adjuvant (surfactants, oils, wetting/spreading agents); Utility adjuvant (drift control, water conditioners, defoamers, compatibility agents) |
| Application | Herbicides; Insecticides; Fungicides; Others |
| Crop type | Cereals and oilseeds; Fruits and vegetables; Others (turf, pasture, specialty) |
| Source | Synthetic; Bio-based / renewable |
| Formulation | Tank-mix; In-can / built-in |
Two structural notes matter. First, activator dominance is stable but not immutable: drift-reduction mandates pull volume toward utility adjuvants, which historically carry lower price per acre. Second, the bio-based flank is small but priced at a premium, and it is where new formulary approvals are concentrating.
Midwest. The Midwest accounts for roughly 38% of national adjuvant demand, reflecting corn, soybean and wheat acreage intensity, followed by the South at about 33% on cotton, rice and specialty crop exposure.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.14% |
| Midwest | 0.38% |
| South | 0.33% |
| West | 0.15% |
| Parent | Children |
|---|---|
| Midwest | Iowa, Illinois, Indiana, Nebraska, Kansas, Minnesota, Missouri, Ohio, Wisconsin, Michigan, Dakotas |
| South | Texas, Arkansas, Louisiana, Mississippi, Alabama, Georgia, Florida, Carolinas, Tennessee, Kentucky, Oklahoma |
| West | California, Idaho, Washington, Oregon, Arizona, Colorado, Montana |
| Northeast | New York, Pennsylvania, New England states, Mid-Atlantic |
Region-level share should be read as acreage-weighted demand, not as vendor presence. Our analysis suggests the South is the more attractive incremental market for utility adjuvants because humid, high-humidity spray windows and cotton herbicide programs generate disproportionate drift-control and water-conditioner demand. The West is the highest-value niche per acre given specialty crop mix and California's stricter application rules.
Productivity pressure and precision spraying are the primary growth engines; the binding constraints are small-farm awareness gaps and tightening synthetic-adjuvant regulation.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Yield and food-demand pressure | Driver | High | Higher active-ingredient efficiency per treated acre |
| Cost of premium actives | Driver | High | Adjuvants reduce required active dose and respray rates |
| Precision agriculture adoption | Driver | Medium-High | Variable-rate, low-volume spraying needs tailored adjuvants |
| Bio-based / sustainable formulations | Driver | Medium | Regulatory and retailer preference for reduced residues |
| Low awareness among small-scale farmers | Restraint | Medium | Under-adoption in lower-acreage operations |
| EPA and state-level adjuvant regulation | Restraint | High | Registration burden and label-restricted use patterns |
| Compatibility complexity | Restraint | Medium | Tank-mix incompatibility raises liability and support cost |
The balance favors growth. Adjuvant demand is largely derivative of pesticide spend, so a soft crop-price year compresses grower budgets faster than it compresses adjuvant attach rates — adjuvants are among the last inputs cut because they protect sunk active-ingredient cost. The offsetting risk is regulatory: state-level drift rules can shift mix toward lower-margin utility products even as treated acres hold.
The landscape is moderately concentrated, with global crop-protection majors competing against focused adjuvant specialists and regional formulators.
| Company | Positioning | Notable strength |
|---|---|---|
| BASF SE | Integrated major | Broad adjuvant portfolio; 2023 fungicide-efficacy launch |
| Syngenta AG | Integrated major | Bundled active-plus-adjuvant programs |
| Corteva Agriscience | Integrated major | Seed-to-spray agronomic integration |
| Dow Inc. | Chemistry-led | Surfactant and silicone chemistry depth |
| Nufarm Limited | Formulation specialist | Tank-mix adjuvant range |
| Nutrien Ltd. | Retail/agronomy | Direct grower channel reach |
| FMC Corporation | Integrated major | Herbicide program alignment |
| UPL Limited | Value-tier | Price-competitive formulations |
| Adama Agricultural Solutions | Value-tier | Broad generic-adjacent portfolio |
Differentiation is shifting from chemistry breadth to compatibility assurance and data services. Integrated majors hold a moat through bundling adjuvants with actives and agronomic advisory; specialists defend with formulation IP and tank-mix compatibility databases. Our analysis suggests the real switching cost is not product price but the risk of an incompatible tank — which favors vendors that publish compatibility matrices and provide on-call agronomy support.
Selection criteria are converging on three fronts: verified compatibility with the specific active-ingredient load, documented drift and deposition performance, and full EPA/state label alignment. Growers and retailers should demand trial data under local water hardness and spray-volume conditions, because adjuvant performance is water-chemistry sensitive and generic labels routinely under-specify this.
Procurement risk is concentrated in supply continuity of specialty surfactants and in single-source tank-mix programs; qualifying a secondary adjuvant supplier is cheap insurance. Switching costs are moderate at product level but high at program level, where agronomists have built recommendations around a specific adjuvant. Regulatory compliance is non-negotiable — a mislabeled or unregistered adjuvant exposes the applicator, not just the vendor, to enforcement. Buyers should also pressure-test claims of bio-based content, since "renewable" is inconsistently defined across suppliers.
The balance of evidence favors a 5.0–5.2% growth path with a 2025 base near USD 630 Million. The low-end 3.1% forecast is the strongest counter-argument — it correctly notes awareness gaps and regulatory friction — but it anchors on a pre-cycle base and understates the mix shift toward drift-control and bio-based products that is already visible in formulary behavior.
Our judgment is that value growth will outpace volume growth modestly, driven by bio-based premium pricing and compatibility-service attach, even as average use rates per acre decline under precision spraying. That combination rewards suppliers with technical service depth and punishes undifferentiated commodity surfactant sellers, who face margin compression as buyers consolidate tank-mix programs.
What would change this conclusion: a federal or multi-state restriction on a major adjuvant class, or two consecutive seasons of sharply lower crop prices that force growers to cut adjuvant attach rates rather than active-ingredient volumes.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.12% from 2020-2034 |
| Segmentation |
|
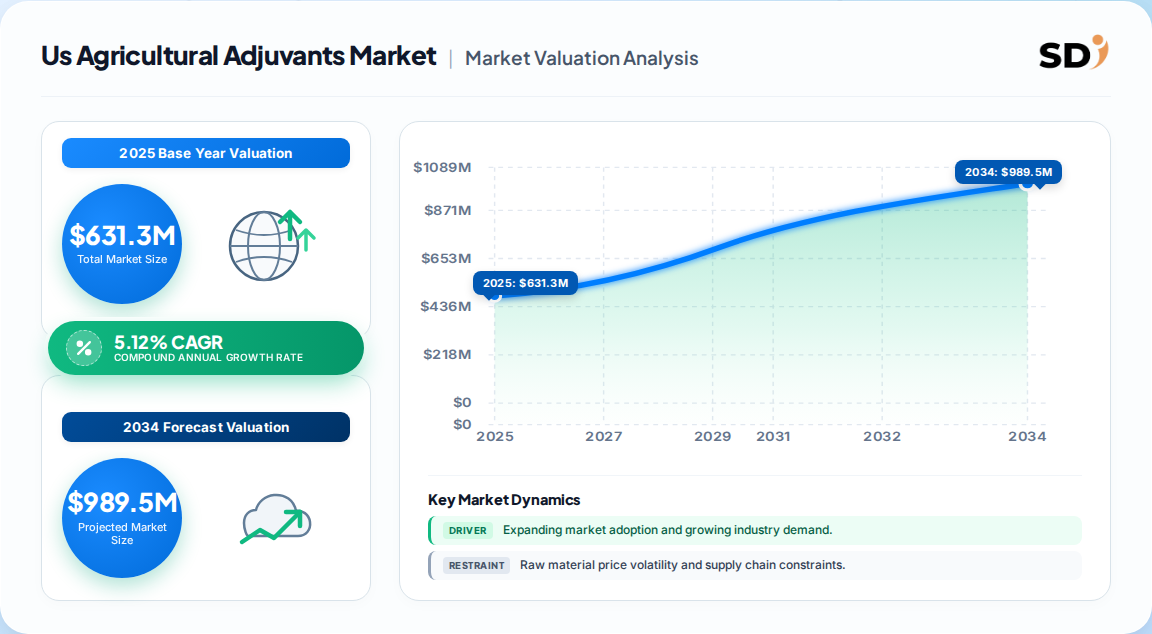
The US agricultural adjuvants market was estimated at USD 631.3 Million in 2025, with forecasts reaching USD 989.2 Million by 2034. Competing published estimates range from roughly USD 514 Million to USD 631 Million depending on whether in-can formulation additives are counted.
Published CAGRs range from 3.1% to 5.12% depending on base year and scope. The 5.12% figure for 2026–2034 is the most defensible for planning because it uses a recent base and captures the drift-control and bio-based mix shift.
Activator adjuvants hold about 72% of revenue, driven by surfactants and oils that improve spreading, wetting and penetration. Utility adjuvants such as drift control agents and water conditioners are the faster-growing flank as spray regulations tighten.
Cereals and oilseeds account for roughly 39% of demand, reflecting corn, wheat and soybean acreage. Fruits and vegetables are the fastest-growing crop segment at about 3.6% CAGR, driven by high-value specialty pest management.
Key players include BASF, Syngenta, Corteva, Dow, FMC, Nufarm, Nutrien, UPL and Adama. Integrated majors compete through bundled active-plus-adjuvant programs, while specialists defend with formulation IP and compatibility data.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised structured depth interviews with stakeholders across the adjuvant value chain: specialty surfactant and oil raw-material suppliers, dedicated adjuvant producers, contract formulators and blenders, and national/regional agricultural distributors. Within those organizations we targeted decision-maker designations including VP of Sourcing, Heads of R&D and Formulation, Technical and Agronomy Directors, and Commercial Operations Leads, using semi-structured interview guides to capture formulary behavior, tank-mix compatibility requirements and purchasing criteria.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Agronomy & Technical Directors | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Specialty Surfactant & Oil Producers | 40% |
| Dedicated Adjuvant Formulators | 35% |
| Distributors & Ag Retailers | 25% |
Secondary validation draws on official multilateral trade and standards databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and SEC 10-K disclosures, patent and trademark databases for formulation IP tracking, and recognized technical standards and industry associations active in crop-protection chemistry and application safety.
We run simultaneous Top-Down allocation from macroeconomic and crop-protection segment spend, and Bottom-Up modeling of manufacturer capacity, product pricing and end-use consumption by crop and application. Divergences between the two models are reconciled at segment level before base-year values are fixed.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | State-level share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |