Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Digestate Based Fertilizer Market Outlook 2026
Digestate Based Fertilizer Market
Digestate Based Fertilizer Market Outlook 2026
Digestate Based Fertilizer Market by Form (Solid, Liquid), by Product (Direct Digestate Fertilizers(Whole Digestate, Liquid Digestate, Solid Digestate), Processed Digestate Fertilizers(Dried Digestate, Pelletized/Granulated Digestate, Composted Digestate), Nutrient-Recovered Digestate Fertilizers(Nitrogen-Recovered Fertilizers, Phosphorus-Recovered Fertilizers, N/P/NK-Recovered Fertilizers)), by Feedstock (Agricultural Manure, Crop Residues/Crops, Industrial/Food Waste, Organic Municipal Waste, Sewage Sludge, Other Feedstocks), by Crop Type (Cereals & Grains, Oilseeds & Pulses, Fruits & Vegetables, Pasture & Forage), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, India, Japan, South Korea), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 265
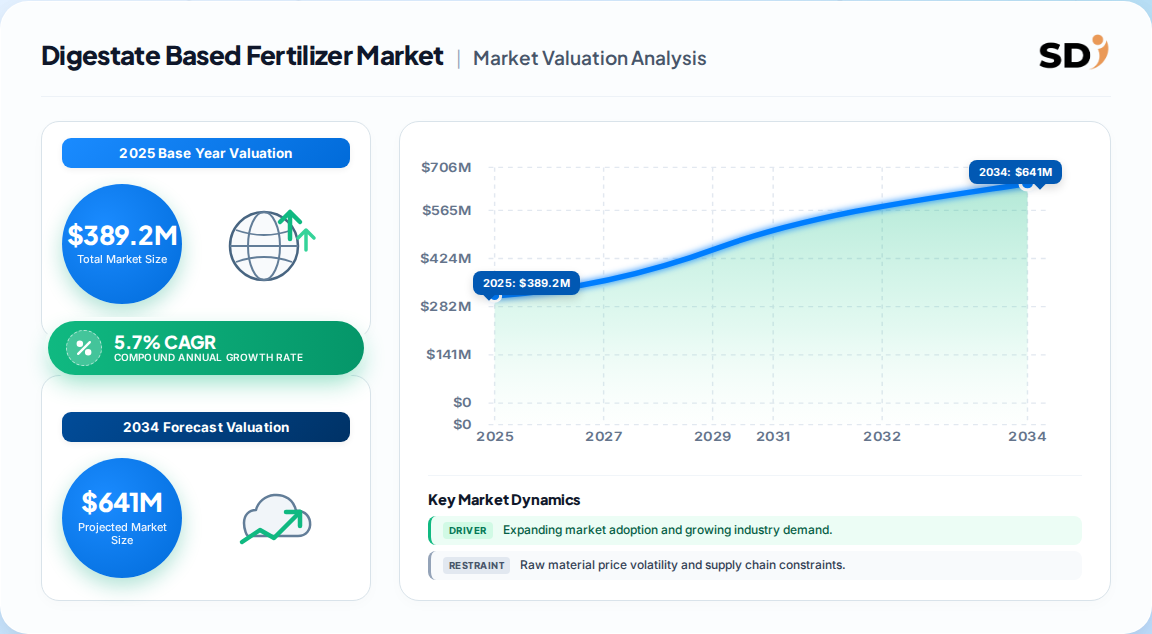
The global digestate-based fertilizer market was valued at USD 389.2 million in 2025, with forecasts converging on a 5.6–5.8% CAGR through the mid-2030s.
End-2034/2035 projected value ranges from USD 647 to 663 million, implying roughly 1.7x expansion from the 2025 base.
Solid and liquid form leadership is disputed across sources; processed (dried, pelletized, nutrient-recovered) products are the consensus fastest-growing tier.
Europe leads with ~39–40% revenue share, underpinned by the EU Fertiliser Action Plan and RENURE expansion; Latin America is the fastest-growing region at 6.7–7.2% CAGR.
Cereals & grains dominate end-use (~31–48% depending on definition), while organic municipal waste is the fastest-growing feedstock.
Leading vendors include Yara, HoSt Bio-Energy, ReFood, Future Biogas, Condorchem, NDDB Mrida and regional biogas operators.
Why this matters for decision-makers: digestate is shifting from a disposal cost to a branded fertilizer input — operators without processing or offtake integration face margin compression as compliance-grade products take share.
Digestate Based Fertilizer Market Size (In Million)
750.0M
600.0M
450.0M
300.0M
150.0M
0
389.0 M
2025
411.0 M
2026
435.0 M
2027
460.0 M
2028
486.0 M
2029
514.0 M
2030
543.0 M
2031
Digestate Based Fertilizer Market Size (In Million)
Year
Market Size
2025
389.0 M
2026
411.0 M
2027
435.0 M
2028
460.0 M
2029
486.0 M
2030
514.0 M
2031
543.0 M
What is the Digestate Based Fertilizer Market?
The digestate based fertilizer market covers nutrient-rich material recovered from anaerobic digestion of manure, biowaste and residues, sold as liquid or solid fertilizer. It spans raw land-applied digestate and processed forms such as dried, pelletized or nutrient-recovered products that substitute mineral NPK inputs.
Scope: what this report covers and excludes
This analysis covers global digestate-derived fertilizer in solid and liquid forms, across direct, processed and nutrient-recovered product tiers, all major feedstocks, crop categories and five regions. This analysis does not cover synthetic mineral fertilizer markets, standalone biogas/biomethane energy markets, compost unrelated to anaerobic digestion, or sewage-sludge-only biosolids products.
How big is the market for Digestate Based Fertilizer?
Base-year 2025 estimates cluster tightly between USD 380 and 389 million, with horizon forecasts in the USD 647–663 million range and CAGRs of 5.6–5.8%, indicating a maturing but still policy-sensitive category.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 570.4M
2025
2033
5.6%
Global digestate-based fertilizer, all forms
One published estimate
USD 663.3M
2025
2035
5.71%
Global, direct + processed + nutrient-recovered
A competing analysis
USD 647.1M
2025
2034
5.81%
Global, all feedstock types
A competing analysis
Our analysis treats the USD 380–389 million 2025 band as the most defensible consensus, because two independent models converge within 2%. The higher 2033 trajectory (USD 570 million) implies a steeper back-loaded curve; we view that as an optimistic case contingent on accelerated RENURE adoption in Europe.
How is the market segmented?
Segmentation spans form, product tier, feedstock and crop type; processed and nutrient-recovered tiers are where pricing power concentrates.
Callout: Processed digestate is projected to grow fastest at ~5.7–6.1% CAGR, versus ~4.9% for direct land application — the clearest structural signal in the dataset.
Which region leads in Digestate Based Fertilizer Market?
Europe leads with roughly 39–40.5% of global revenue in 2025, supported by mature anaerobic digestion infrastructure, RENURE criteria and the EU Fertiliser Action Plan; Latin America is the fastest-growing region at 6.7–7.2% CAGR.
Digestate Based Fertilizer Market Regional Market Share
Loading chart...
Digestate Based Fertilizer Market Regional Market Share
Region
Market Share (%)
Europe
0.4%
North America
0.23%
Asia-Pacific
0.21%
Latin America
0.1%
Middle East & Africa
0.06%
Europe — Germany, UK, France, Italy, Spain, Nordics
North America — USA, Canada, Mexico
Asia Pacific — China, India, Japan, South Korea
Latin America — Brazil, Argentina, Mexico
Middle East & Africa — Saudi Arabia, South Africa
Region
2025 share (synthesized)
Europe
40%
North America
23%
Asia-Pacific
21%
Latin America
10%
Middle East & Africa
6%
What is driving growth — and what is holding it back?
Policy-driven nutrient circularity and fertilizer price volatility are the dominant demand drivers; variable product quality, transport economics and fragmented regulation are the principal brakes on faster adoption.
Factor
Direction
Evidence strength
Mechanism
EU Fertiliser Action Plan / RENURE extension
Driver
High
Legalizes processed digestate as mineral-N substitute
Synthetic fertilizer price volatility
Driver
High
Raises relative value of recovered nutrients
Anaerobic digestion capacity growth
Driver
High
Expands digestate feedstock supply
Nutrient-recovery tech (stripping, struvite)
Driver
Medium
Improves concentration and transportability
Variable nutrient consistency
Restraint
High
Limits farmer trust and precision application
Transport & storage costs
Restraint
High
Caps economic radius for liquid digestate
Patchy national fertilizer regulations
Restraint
Medium
Slows cross-border commercialization
Our analysis suggests the driver-restraint balance is tilting toward growth because the regulatory constraint is being actively dismantled in Europe, the largest market. However, outside the EU the absence of equivalent RENURE-style frameworks means growth will be slower and more project-specific than headline CAGR implies.
Who are the leading vendors?
No single vendor holds dominant share; the landscape is bifurcated between diversified fertilizer majors leveraging distribution and biogas-native processors leveraging feedstock proximity.
Company
Positioning
Strategic moat
Yara
Global fertilizer major
Brand, distribution, agronomic advisory
HoSt Bio-Energy
Digester and digestate technology
Engineering IP, installed base
ReFood
Food-waste recycling operator
Feedstock access, collection networks
Future Biogas
UK biogas plant operator
Plant portfolio, offtake agreements
Condorchem Enviro Solutions
Nutrient recovery / treatment
Ammonia stripping, P-recovery tech
NDDB Mrida
India dairy cooperative
Manure feedstock, rural distribution
Differentiation rests on three axes: feedstock control (proximity and contracted volumes), processing capability (drying, pelletizing, stripping), and certification (OMRI, EU 2019/1009 conformity). Vendors strong in only one axis will struggle to command premium pricing.
What do buyers and operators need to know?
Procurement decisions hinge on nutrient consistency, contaminant assurance (plastics, heavy metals, pathogens) and certification status more than headline price. Buyers should demand batch-level nutrient analysis and third-party conformity documentation, because variability is the category's principal adoption barrier.
Switching costs are moderate for large arable farms already equipped for solid fertilizer handling, but high for horticultural and specialty growers requiring precise formulations. Contract structures increasingly bundle digestate offtake with biogas plant agreements, locking buyers into multi-year supply — a benefit for price certainty but a constraint on flexibility.
Regulatory compliance varies sharply by jurisdiction; EU buyers should verify conformity with Regulation 2019/1009 and emerging RENURE criteria, while US buyers should track state-level organics diversion rules and OMRI listing status. Finally, logistics economics mean buyers more than ~50 km from a plant using liquid digestate face prohibitive transport costs — favor processed or pelletized forms at distance.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a structural growth story with a regulatory catalyst dependency. The consensus 5.6–5.8% CAGR is credible, but it embeds European policy execution that has not yet been fully legislated. Our view is that the category will outperform in Europe and underperform in Asia-Pacific relative to headline forecasts, because feedstock aggregation and fertilizer-registration frameworks still lag.
The strongest counter-argument is that fertilizer majors could crowd out digestate specialists through distribution and brand power, capping specialist margins. We consider this partially valid — but feedstock proximity and anaerobic digestion integration are genuine structural moats that majors cannot easily replicate, which is why co-opetition (as with Yara's positioning) is more likely than displacement.
Actionable strategy:
Operators should prioritize nutrient-recovery and pelletization capability to escape the low-margin local land-application segment and target distant, higher-value buyers.
Investors should underwrite integrated business cases (gate fees + biogas + fertilizer sales), not fertilizer revenue alone, and stress-test against feedstock contract concentration.
Buyers should secure multi-year offtake with batch-level quality guarantees before competitor-driven price escalation arrives with processed-product standardization.
What would change our conclusion: evidence that RENURE extension stalls at the EU Parliament, or a sustained normalization of synthetic fertilizer prices, would materially flatten the 2027–2030 growth curve.
Gap note: this overview synthesizes segment-level estimates, but precise sub-segment forecasts (e.g., struvite recovery revenue by country) and vendor-level capacity maps require the full report's bottom-up modeling.
Digestate Based Fertilizer Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Digestate Based Fertilizer Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.7% from 2020-2034
Segmentation
By Form
Solid
Liquid
By Product
Direct Digestate Fertilizers(Whole Digestate, Liquid Digestate, Solid Digestate)
10.3. Market Analysis, Insights and Forecast - by Feedstock
10.3.1. Agricultural Manure
10.3.2. Crop Residues/Crops
10.3.3. Industrial/Food Waste
10.3.4. Organic Municipal Waste
10.3.5. Sewage Sludge
10.3.6. Other Feedstocks
10.4. Market Analysis, Insights and Forecast - by Crop Type
10.4.1. Cereals & Grains
10.4.2. Oilseeds & Pulses
10.4.3. Fruits & Vegetables
10.4.4. Pasture & Forage
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Digestate Based Fertilizer Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Digestate Based Fertilizer Market Revenue (Million), by Form 2026 & 2034
Figure 3: North America Digestate Based Fertilizer Market Revenue Share (%), by Form 2026 & 2034
Figure 4: North America Digestate Based Fertilizer Market Revenue (Million), by Product 2026 & 2034
Figure 5: North America Digestate Based Fertilizer Market Revenue Share (%), by Product 2026 & 2034
Figure 6: North America Digestate Based Fertilizer Market Revenue (Million), by Feedstock 2026 & 2034
Figure 7: North America Digestate Based Fertilizer Market Revenue Share (%), by Feedstock 2026 & 2034
Figure 8: North America Digestate Based Fertilizer Market Revenue (Million), by Crop Type 2026 & 2034
Figure 9: North America Digestate Based Fertilizer Market Revenue Share (%), by Crop Type 2026 & 2034
Figure 10: North America Digestate Based Fertilizer Market Revenue (Million), by Country 2026 & 2034
Figure 11: North America Digestate Based Fertilizer Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Digestate Based Fertilizer Market Revenue (Million), by Form 2026 & 2034
Figure 13: Europe Digestate Based Fertilizer Market Revenue Share (%), by Form 2026 & 2034
Figure 14: Europe Digestate Based Fertilizer Market Revenue (Million), by Product 2026 & 2034
Figure 15: Europe Digestate Based Fertilizer Market Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Digestate Based Fertilizer Market Revenue (Million), by Feedstock 2026 & 2034
List of Tables
Table 1: Digestate Based Fertilizer Market Revenue Million Forecast, by Form 2020 & 2034
Table 2: Digestate Based Fertilizer Market Revenue Million Forecast, by Product 2020 & 2034
Table 3: Digestate Based Fertilizer Market Revenue Million Forecast, by Feedstock 2020 & 2034
Table 4: Digestate Based Fertilizer Market Revenue Million Forecast, by Crop Type 2020 & 2034
Table 5: Digestate Based Fertilizer Market Revenue Million Forecast, by Region 2020 & 2034
Table 6: North America Digestate Based Fertilizer Market Revenue Million Forecast, by Form 2020 & 2034
Table 7: North America Digestate Based Fertilizer Market Revenue Million Forecast, by Product 2020 & 2034
Table 8: North America Digestate Based Fertilizer Market Revenue Million Forecast, by Feedstock 2020 & 2034
Table 9: North America Digestate Based Fertilizer Market Revenue Million Forecast, by Crop Type 2020 & 2034
Table 10: North America Digestate Based Fertilizer Market Revenue Million Forecast, by Country 2020 & 2034
Table 11: USA Digestate Based Fertilizer Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 12: Canada Digestate Based Fertilizer Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 13: Mexico Digestate Based Fertilizer Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 14: Europe Digestate Based Fertilizer Market Revenue Million Forecast, by Form 2020 & 2034
Table 15: Europe Digestate Based Fertilizer Market Revenue Million Forecast, by Product 2020 & 2034
Europe Digestate Based Fertilizer Market Revenue Million Forecast, by Feedstock 2020 & 2034
Frequently Asked Questions
1. What is digestate based fertilizer?
It is the nutrient-rich material left after anaerobic digestion of manure, food waste or crop residues, applied to soil as a liquid or solid fertilizer. It supplies nitrogen, phosphorus, potassium and organic matter, substituting part of conventional mineral fertilizer use.
2. How big is the digestate based fertilizer market?
The market was valued at roughly USD 389 million in 2025, with independent forecasts converging on USD 647–663 million by 2034–2035. That implies a compound annual growth rate of about 5.6–5.8% over the forecast period.
3. Which region leads digestate based fertilizer adoption?
Europe leads with about 40% of global revenue, driven by mature anaerobic digestion infrastructure and the EU Fertiliser Action Plan. Latin America is the fastest-growing region, expanding at roughly 6.7–7.2% annually on strong agricultural feedstock availability.
4. What is the fastest-growing digestate fertilizer segment?
Processed digestate — including dried, pelletized and nutrient-recovered products — is growing fastest at about 6% annually, as producers seek standardized, transportable products that command premium pricing over raw land-applied digestate.
5. Who are the leading companies in this market?
Key players include Yara, HoSt Bio-Energy, ReFood, Future Biogas, Condorchem Enviro Solutions, NDDB Mrida, Hydrotech Engineering and Doranova. The landscape is fragmented, with no single vendor holding dominant share across regions.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program is built on a 70/30 primary-to-secondary split, prioritizing direct intelligence from operators and buyers over published proxies. We conducted in-depth interviews with stakeholders across the digestate value chain: anaerobic digestion plant operators, digestate processing technology suppliers, contract fertilizer formulators, and agricultural distributors serving large-scale growers. Interviews targeted decision-makers with direct procurement and formulation authority, including VP-level Sourcing Leads, Heads of R&D and Agronomy, Technical Directors of processing facilities, and Commercial Operations Leads responsible for offtake agreements across Europe, North America and Latin America.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
32%
R&D & Agronomy Heads
28%
Technical & Processing Directors
24%
Commercial Operations Leads
16%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Anaerobic Digestion Plant Operators
35%
Digestate Processing Technology Suppliers
25%
Contract Fertilizer Formulators
22%
Agricultural Distributors & Cooperatives
18%
Secondary Benchmarking & Public Trade Validation
Secondary research triangulated official trade and standards databases including UN Comtrade, Eurostat, US ITC and USDA trade statistics, alongside corporate filings (10-K, annual reports and investor presentations), patent activity in nutrient recovery and pelletization, and technical standards from recognized industry associations. Regulatory texts, notably EU Regulation 2019/1009 and the European Biogas Association's digestate reporting, were used to validate compliance-driven demand assumptions.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous Top-Down and Bottom-Up models. The top-down model allocates macroeconomic agricultural input spend by crop category and region to derive digestate's addressable share. The bottom-up model builds from individual plant capacity, digestate output volumes, product pricing by form, and end-use consumption to derive total revenue. Divergence between the two models was reconciled through weighted averaging.


 Digestate Based Fertilizer Market