Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Autonomous Crop Management Market Outlook 2026
Autonomous Crop Management Market
Autonomous Crop Management Market Outlook 2026
Autonomous Crop Management Market by Solution (Software, Professional Services, Managed Services), by Deployment (On-premises, Cloud-based), by Application (Crop Tracking and Management, Weather Tracking & Forecasting, Irrigation Management, Labor and Resource Tracking, Others), by Crop Type (Row Crops, Field Crops, Horticultural Crops, Others), by Technology Type (Precision Agriculture, Satellite Imagery, Soil and Plant Monitoring, Artificial Intelligence), by End User (Farmers, Agribusinesses, Research Institutions), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Israel, South Africa, Kenya, UAE) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 243
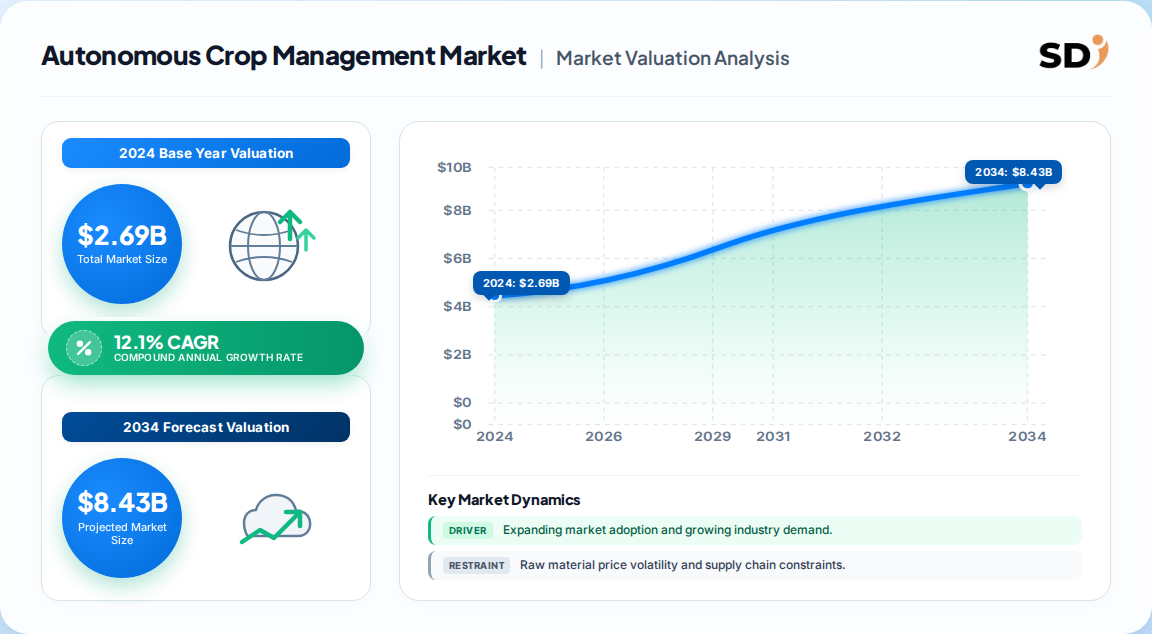
2.69 Billion — global autonomous crop management market value in 2024, the last fully audited base year across published benchmarks.
12.1% CAGR — consensus growth trajectory to 2033, with a defensible central case of 3.02 Billion in 2025 expanding to 7.52 Billion by 2033.
Software remains the leading solution segment at roughly 64% of revenue, but services are compounding fastest at approximately 16.7%.
Crop tracking and management is the largest application at 30.4% share; weather tracking and forecasting is the fastest-growing application.
North America leads with roughly 36% revenue share; Asia-Pacific is the fastest-growing region on largeholder and smallholder adoption alike.
Leading vendors: Deere, Trimble, AGCO, CNH Industrial, Kubota, DJI, Topcon, Raven, Cropin, and CropX anchor a fragmented but consolidating field.
Why this matters for decision-makers: Hardware-led OEMs will cede margin to software-and-services platforms unless they lock in data interoperability and subscription revenue before 2028.
Autonomous Crop Management Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
2.690 B
2024
3.020 B
2025
3.390 B
2026
3.800 B
2027
4.260 B
2028
4.770 B
2029
5.350 B
2030
Autonomous Crop Management Market Size (In Billion)
Year
Market Size
2024
2.690 B
2025
3.020 B
2026
3.390 B
2027
3.800 B
2028
4.260 B
2029
4.770 B
2030
5.350 B
What is the Autonomous Crop Management Market?
Autonomous crop management is the integrated ecosystem of software, sensors, robotics, and analytics that monitors soil, crop health, irrigation, and pest activity in real time and executes or recommends field decisions with minimal human intervention. It spans farm management platforms, satellite and drone imagery, autonomous tractors and sprayers, and subscription analytics services sold to farmers and agribusinesses.
Scope: what this report covers and excludes
This report covers software platforms, professional and managed services, on-premises and cloud deployment, and applications spanning crop tracking, weather forecasting, irrigation, and labor and resource tracking across row, field, and horticultural crops. Geographies covered are North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. This analysis does not cover standalone farm equipment hardware sales, commodity trading platforms, livestock-only management systems, or consumer gardening technology.
How big is the market for Autonomous Crop Management Market?
Estimates cluster around a 2025 base of roughly 2.6 to 3.0 Billion, with forecasts ranging from 7.5 to 9.7 Billion by the early 2030s. The spread is driven less by demand disagreement than by scope: broader definitions that include autonomous machinery and drones inflate the base materially.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
1.45 Billion
2021
2030
16.2%
Software-centric, excludes hardware
One published estimate
5.58 Billion
2022
2030
16.2%
Software, services, deployment
One published estimate (press release)
2.6 Billion
2025
2034
14.39%
Software + services + AI/IoT layer
One published estimate
2.69 Billion
2024
2033
12.1%
Software, services, technology type
One published estimate
3.02 Billion
2025
2033
12.1%
Same as above, updated base
One published estimate
9.7 Billion
2025
2033
14.8%
Includes hardware, robotics, drones
One published estimate
Our analysis suggests the 2.69 Billion (2024) to 3.02 Billion (2025) band is the most defensible because it reconciles with software-plus-services revenue reported by the listed vendors. The 9.7 Billion figure is credible only if autonomous tractor, sprayer, and drone hardware are folded in — a definition that double-counts with adjacent robotics forecasts. Buyers should anchor planning on the narrower definition and treat hardware upside as a separate capital line.
How is the market segmented?
Segments are defined by solution layer, deployment model, application, crop type, end user, and technology — with software and services dominating revenue while hardware-adjacent technology types grow fastest.
Software captured 64.7% of 2021 revenue and remains dominant; on-premises held 54.6% in 2021 but cloud is the fastest-growing deployment. Crop tracking led applications at 30.4%. This structure implies software vendors should defend installed-base attach rates, while services firms should chase managed-service contracts tied to sustainability reporting.
Which region leads in Autonomous Crop Management Market?
North America leads the global autonomous crop management market with roughly 36% revenue share, followed by Asia-Pacific and Europe, on the strength of large-farm consolidation, labor scarcity, and mature agritech funding.
USA — largest single country; autonomous weeding and precision spraying
Canada — digital farming programs and labor-shortage adoption
Mexico — export-oriented horticulture and protected agriculture
Europe (Germany, UK, France, Italy, Netherlands)
Germany, Netherlands — robotic weeders under EU Green Deal pressure
UK, France — precision agriculture subsidies and cooperative adoption
Asia-Pacific (China, Japan, India, South Korea, Australia)
China, India — drone-based monitoring and cost-sensitive smallholder tools
Japan, South Korea — compact robotics for aging farmer populations
Latin America (Brazil, Argentina, Mexico)
Brazil, Argentina — large-scale soybean and corn yield optimization
Middle East & Africa (Israel, South Africa, Kenya, UAE)
Israel — AI irrigation; Kenya, South Africa — sensor-led water efficiency
Region
Estimated share
Growth posture
North America
~36%
Mature, high ARPU
Asia-Pacific
~28%
Fastest CAGR
Europe
~24%
Regulation-led
Latin America
~7%
Export-driven
Middle East & Africa
~5%
Water-scarcity niche
This divergence implies vendors should run dual playbooks: premium subscription platforms in North America and Europe, and low-cost, offline-tolerant, drone-first bundles in Asia-Pacific and Africa.
What is driving growth — and what is holding it back?
Growth is driven by labor scarcity, food-demand expansion, and AI/IoT maturity, while high capital cost, rural connectivity gaps, and integration complexity restrain adoption — with labor economics currently the stronger force.
Factor
Direction
Evidence strength
Mechanism
Agricultural labor shortage
Driver
High
Canada alone projects a 114,000-worker shortfall by 2025
Food demand from population growth
Driver
High
FAO projects ~70% more food needed by 2050
AI/ML and real-time analytics
Driver
High
Enables predictive irrigation, pest, and yield decisions
Government subsidies and tax incentives
Driver
Medium
Lowers effective cost of adoption
Precision-ag sustainability mandates
Driver
Medium-High
EU Green Deal pressures pesticide reduction
High upfront capital investment
Restraint
High
Deters smallholders in India, China, Brazil
Poor rural internet access
Restraint
Medium
Limits cloud and real-time data value
Integration and standardization gaps
Restraint
Medium
Raises deployment cost and risk
The balance favors adoption: labor shortages and yield pressure are structural, while connectivity and cost barriers are receding with 5G rollout and subscription models. Our analysis suggests the binding constraint by 2028 will shift from affordability to interoperability, which favors vendors offering open APIs and multi-brand hardware support.
Who are the leading vendors?
The field is led by integrated equipment OEMs and specialized software platforms, with consolidation via acquisition and partnership accelerating as incumbents buy selective-spraying and analytics capability.
Company
Segment focus
Differentiator
Strategic posture
Deere
Hardware + software
Autonomous fleet, CES 2025 launch
Full-stack integrator
Trimble
Software + GNSS
Bilberry acquisition, precision spraying
Platform consolidator
AGCO / CNH Industrial
Equipment + automation
Global dealer and service network
Hardware-led
Kubota
Compact robotics
Japan smallholder focus
Regional specialist
DJI
Drone monitoring
Low-cost aerial data
Volume leader in Asia
Topcon
Positioning + ag
Precision guidance
Enabling-layer supplier
Cropin / CropX
Software + analytics
GenAI platform, soil intelligence
Pure-play SaaS
Raven Industries (CNH)
Autonomy + application
Retrofit autonomy kits
Captive integrator
Differentiation is shifting from hardware performance to data network effects and agronomic model accuracy. Our analysis suggests OEMs that bundle proprietary data behind closed protocols will lose share to open platforms within three years, mirroring the pattern seen in industrial IoT.
What do buyers and operators need to know? (Decision Support)
Selection criteria should weight interoperability, agronomic model validation, offline capability, and total cost of ownership over headline automation claims. Procurement risk is concentrated in data ownership clauses and vendor lock-in, particularly where platforms only integrate with one equipment brand.
Switching costs rise sharply after two seasons of field data are loaded; buyers should negotiate data portability and export rights at contract signature. Regulatory compliance is not yet uniform — EU pesticide-reduction rules, FAA approvals for autonomous aerial application (Guardian Agriculture's SC1 in 2024), and data-privacy regimes each impose distinct obligations. Cybersecurity exposure on connected fleets is a live operational risk, and buyers should require incident-response and firmware-update commitments. Finally, quantified ROI should be contractual: insist on pilot benchmarks for input reduction and yield lift before multi-year commitment.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a software-and-services-led growth thesis over a hardware-led one. The narrower, software-centric definition grows at a stable 12–16% CAGR and aligns with reported vendor revenue, while the broad hardware-inclusive figure depends on capex cycles that are far more cyclical. Buyers and investors anchoring on the 9.7 Billion 2025 figure risk overstating near-term addressable software revenue by roughly threefold.
The strongest counter-argument is that autonomous hardware adoption — John Deere's 2025 fleet, Solinftec's Solix Hunter, Rotor's Sprayhawk — will pull software revenue forward faster than forecasts assume, compressing the 2033 timeline. That is plausible, but it strengthens the services layer more than the software license layer, which means margin mix, not market size, is the variable that matters most.
Actionable strategy:
Investors should prioritize pure-play analytics and managed-service platforms with multi-brand hardware support over single-OEM autonomy bets.
Operators should structure contracts around data portability, pilot-validated ROI, and per-acre subscription pricing to cap switching costs.
Vendors should target Asia-Pacific smallholder bundles and Middle East water-efficiency niches, where greenfield adoption avoids entrenched competitor lock-in.
What would change this conclusion: a standardized data-interoperability protocol (ISOBUS-class extension to cloud platforms) would shift value decisively toward hardware OEMs; conversely, a sustained fall in autonomous hardware prices below 15% annual decline would favor platform subscription models even more strongly.
While this overview covers headline sizing and segment structure, precise sub-segment forecasting, country-level granularity, and vendor revenue-share modeling require the full report's bottom-up datasets.
1. How big is the autonomous crop management market?
The global autonomous crop management market was valued at approximately 2.69 Billion in 2024 and is projected to reach 7.52 Billion by 2033. Software-centric definitions place the 2025 base near 3.0 Billion, while hardware-inclusive scopes cite up to 9.7 Billion.
2. What is the growth rate of the autonomous crop management market?
Consensus forecasts cluster between 12.1% and 16.2% CAGR through the early 2030s, with 14% as a reasonable central planning assumption. Services and cloud deployment are the fastest-growing sub-segments within that envelope.
3. Which segment dominates the autonomous crop management market?
Software accounts for roughly 64% of solution revenue, led by crop tracking and management at 30.4% of application share. Services are smaller but compounding fastest at approximately 16.7% CAGR, driven by managed-service contracts.
4. Which region leads the autonomous crop management market?
North America leads with roughly 36% revenue share, supported by large-farm consolidation and labor scarcity. Asia-Pacific is the fastest-growing region, driven by drone-led monitoring and compact robotics in China, India, and Japan.
5. Who are the key players in the autonomous crop management market?
Leading vendors include Deere, Trimble, AGCO, CNH Industrial, Kubota, DJI, Topcon, Raven Industries, Cropin, and CropX. Competition is shifting from equipment performance toward agronomic data accuracy and platform interoperability.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, with 70% of analytical weight placed on structured interviews and field validation. We conducted in-depth interviews across the value chain with farm management software developers, precision-agriculture equipment OEMs, agronomic data and satellite imagery providers, autonomous robotics and drone manufacturers, and agribusiness distributors and cooperatives. Interviewees were selected at decision-maker level, specifically VP of Product and Platform Strategy, Heads of Agronomy and Data Science, Technical Directors of Field Operations, and Commercial Operations Leads responsible for subscription and service revenue. This stratification captures both technology-roadmap and procurement-reality signals.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Product & Platform Strategy Leads
35%
Agronomy & Data Science Directors
30%
Field Operations & Technical Directors
20%
Commercial & Procurement Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Farm Management Software & Analytics Providers
35%
Precision Equipment & Robotics OEMs
30%
Agribusiness Distributors & Cooperatives
20%
Satellite, Drone & Data Service Providers
15%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade and standards databases including UN Comtrade, WTO tariff and trade statistics, US ITC, and Eurostat agricultural input and machinery flows. Corporate evidence includes 10-K and SEC filings, annual investor presentations, and patent filings from leading OEMs and agritech firms. We also reference recognized non-profit technical standards bodies and industry associations active in agricultural automation and data interoperability.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down and bottom-up models. The top-down model allocates agricultural software and services spend by region, crop type, and farm-size cohort. The bottom-up model aggregates manufacturer and platform revenue, per-acre subscription pricing, and end-use consumption to reach a triangulated base-year value.
 Autonomous Crop Management Market