 Agriculture Sensor Market
 Size, Forecast & Trends 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 186

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Agriculture Sensor Market
Atul Bhusare
Research Associate
| Year | Market Size |
|---|---|
| 2025 | 2.100 B |
| 2026 | 2.360 B |
| 2027 | 2.650 B |
| 2028 | 2.980 B |
| 2029 | 3.340 B |
| 2030 | 3.750 B |
| 2031 | 4.210 B |

The agriculture sensor market covers physical devices that capture soil, weather, water, crop, and livestock data at the point of production. These sensors feed irrigation scheduling, input application, disease management, and automation systems. The scope excludes software platforms, GPS guidance, and drone airframes where the sensor payload is not the primary commercial value driver.
This report sizes and forecasts dedicated physical sensing hardware deployed in field, orchard, greenhouse, and livestock operations, segmented by sensor type and application. Revenue reflects device-level sales to growers, integrators, and OEMs.
Excluded from scope: farm-management software platforms, satellite imagery subscriptions, autonomous machinery, drone airframes, and GPS guidance systems where sensors are embedded components rather than the commercial product. Also excluded are laboratory-grade instruments and non-agricultural environmental monitoring.
The market is growing at a double-digit pace, but published estimates diverge sharply—ranging from 1.41 Billion to 3.0 Billion for 2025—because each analyst defines scope differently. The table below reconciles the competing figures.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 1.41 Billion | 2025 | 2035 | 9.6% | Dedicated field-sensing hardware only; excludes software, GPS, drone airframes | One published estimate |
| 2.1 Billion | 2025 | 2031 | 12.3% | Sensor hardware segmented by type and application, global | A competing analysis |
| 3.0 Billion | 2025 | 2033 | 12.6% | Broader sensor definition including location and airflow sensors | A competing analysis |
Our analysis suggests the 2.1–2.4 Billion range is the most defensible base year because it aligns with the 27.6% soil-moisture share and the 33.6% soil-management application share reported by segment-level sources. The 1.41 Billion figure likely reflects a narrower hardware-only definition that strips out embedded sensing revenue. The 3.0 Billion figure likely bundles location sensors and broader categories that inflate the addressable base.
Segmentation follows two non-geographic axes—sensor type and application—with type capturing the physical measurement technology and application capturing the farm workflow being optimized.
| Parent segment | Children |
|---|---|
| By Type | Soil-moisture, humidity, temperature, electrochemical, mechanical, airflow, optical, pressure, water, livestock biosensors, location |
| By Application | Soil management, climate management, water management, dairy management, crop health, irrigation control |
| By Deployment | Wired in-field networks, wireless LPWAN (LoRaWAN/NB-IoT), drone-mounted, handheld |
Soil-moisture sensors captured 27.6% of type revenue in 2025, while livestock biosensors recorded the fastest growth at roughly 9.4% CAGR through 2031. On the application side, soil management held 33.6%, and climate management is expanding at an 8.2% CAGR. This mix implies that water and soil optimization remain the commercial center of gravity, while livestock health is the emerging high-growth flank.
North America leads the global agriculture sensor market, holding an estimated 31–43% revenue share in 2025 depending on scope definition, with Asia-Pacific the fastest-growing region.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.24% |
| Asia-Pacific | 0.28% |
| South America | 0.08% |
| Middle East & Africa | 0.06% |
The regional spread is uneven. North America's lead rests on large commercial farm size, established precision-ag subsidies, and dense dealer networks. Asia-Pacific's faster CAGR reflects a lower starting base, government digitization programs, and rising water scarcity in China and India. Our analysis suggests Asia-Pacific will close roughly half the share gap with North America by 2031, but infrastructure gaps—only 22.5% of global cropland is irrigated—will keep adoption concentrated in large commercial operations.
Water scarcity, smart-farming adoption, and government subsidies are the primary growth engines, while high upfront cost, weak rural connectivity, and sensor calibration drift are the main restraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Water stress and precision irrigation | Driver | High (FAO) | Regulatory limits and extraction costs make sensor-guided irrigation a risk-management purchase |
| Smart-farming and IoT adoption | Driver | High | Continuous field data replaces periodic manual scouting; sensors become the data layer |
| Government precision-ag subsidies | Driver | High (GAO) | Cost-share programs cut payback periods and expand mid-tier addressable demand |
| MEMS miniaturization and LPWAN | Driver | Medium-High | Sub-USD 100 multi-parameter nodes shift buying from single devices to integrated assemblies |
| High upfront cost for smallholders | Restraint | High | Only 27% of U.S. farms used precision-ag practices in 2023 |
| Infrastructure gaps | Restraint | High (FAO) | Only 22.5% of global cropland is irrigated, limiting executable decision value |
| Calibration drift and protocol fragmentation | Restraint | Medium | SDI-12 and Modbus interoperability gaps raise total cost of ownership |
The balance of evidence favors the drivers. Subsidies provide short-term demand certainty, while water scarcity creates a structural, non-discretionary pull that outlasts policy cycles. However, the restraints are not trivial: they cap adoption in smallholder segments and slow replacement cycles in multi-vendor networks. This divergence implies that growth will be concentrated among large and mid-size commercial farms through 2028, with smallholder adoption dependent on financing bundles and sub-USD 100 node pricing arriving later in the forecast window.
The vendor landscape is medium-concentration, with Deere & Company, Trimble/AGCO, Topcon, Hexagon, and Robert Bosch leading, while specialty sensor makers hold strong positions in soil-moisture and weather niches.
| Company | Primary positioning | Noted strength |
|---|---|---|
| Deere & Company | Integrated precision-ag platform | Largest installed base; ~13.5% share in 2025 |
| Trimble / AGCO | Guidance, telematics, sensor integration | Strong OEM and aftermarket channel |
| Topcon Corporation | Precision positioning and field sensors | Strong in Asia-Pacific and OEM supply |
| Hexagon AB | Geospatial and sensing hardware | Portfolio breadth across optical and location sensors |
| Robert Bosch GmbH | MEMS and environmental sensing | Component-scale cost leadership |
| METER Group / Campbell Scientific | Soil and weather instrumentation | Scientific credibility and calibration expertise |
Competitive moats are shifting from hardware specifications to data integration and workflow lock-in. The top five players hold roughly 21.4% combined share, indicating room for specialists to win on calibration accuracy, durability, and compatibility with farm-management platforms. Our analysis suggests vendors that bundle sensor hardware with analytics subscriptions will capture a disproportionate share of value as standalone node prices compress.
Sensor procurement is not a hardware purchase—it is a decision-system purchase. Buyers should prioritize calibration stability, power autonomy, and protocol compatibility (SDI-12, Modbus, LoRaWAN) over headline price. A node that drifts after one season or cannot be integrated into an existing irrigation controller destroys more value than it creates.
Key selection criteria:
Procurement risks include multi-vendor interoperability gaps, which raise integration costs, and unclear data ownership terms. Switching costs rise sharply once a sensor network is embedded in irrigation scheduling, creating a lock-in effect that favors incumbents. Regulatory compliance—water-use reporting and, increasingly, carbon-credit verification—is becoming a procurement driver, particularly in North America and Europe. Buyers should also model total cost of ownership over five years, not just node price.
The balance of evidence favors a 12%+ CAGR base case, with the market reaching approximately 4.2 Billion by 2031. The 9.6% CAGR estimate is defensible for hardware-only scope but underestimates the value migrating into integrated sensor-plus-analytics systems. The strongest counter-argument is that infrastructure gaps and smallholder affordability could cap growth below 10%; however, water scarcity and subsidy programs provide a structural floor that makes a sub-10% outcome unlikely outside a severe macroeconomic shock.
Actionable strategy:
What would change our conclusion: a sustained freeze in U.S. and EU precision-ag subsidy budgets, or a failure of LPWAN coverage to expand in Asia-Pacific, would push growth toward the low single digits. Similarly, a breakthrough in satellite-based soil-moisture estimation at no marginal cost could erode demand for in-field nodes. Buyers requiring sub-segment forecasting, vendor-level market share, or country-level pricing should consult the full report, which includes granular forecasts by sensor type, application, and region.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.3% from 2020-2034 |
| Segmentation |
|
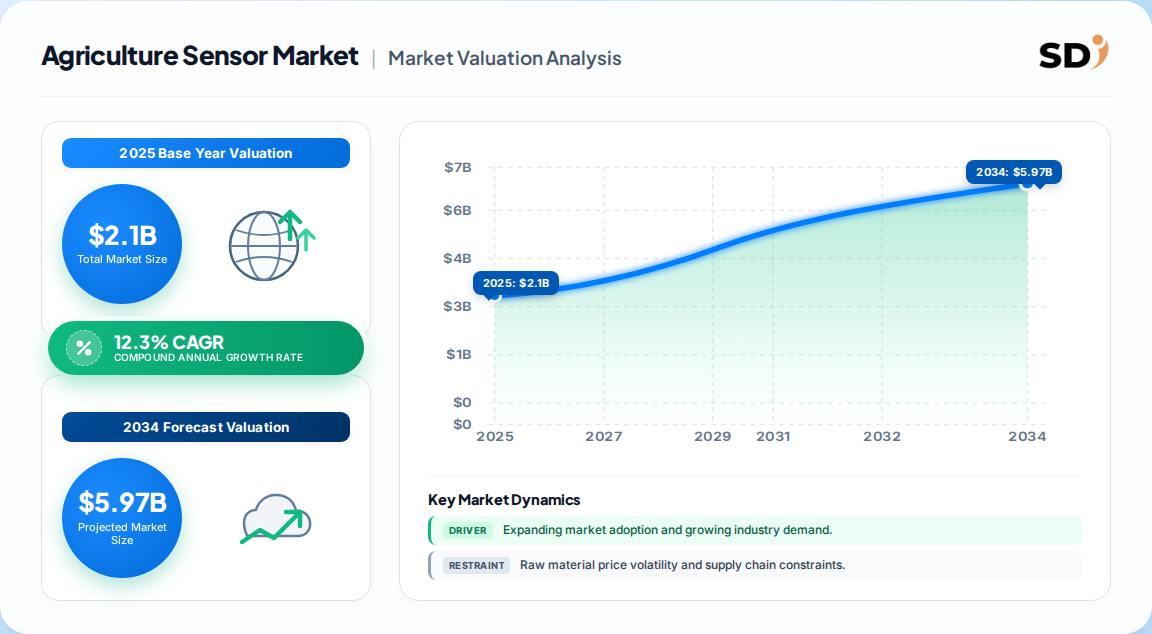
The global agriculture sensor market is estimated at 2.36 Billion in 2026, growing from 2.1 Billion in 2025, based on a consensus of published estimates and segment-level triangulation.
The market is growing at a 12.3% CAGR from 2026 to 2031, with some estimates ranging from 9.6% to 12.6% depending on whether software and location sensors are included.
North America leads with roughly 31–43% revenue share in 2025, driven by large commercial farms, precision-ag subsidies, and established dealer networks. Asia-Pacific is the fastest-growing region.
Water scarcity and precision irrigation, smart-farming and IoT adoption, government subsidies, and MEMS/LPWAN cost reductions are the primary growth drivers through 2031.
Deere & Company, Trimble/AGCO, Topcon, Hexagon, Robert Bosch, METER Group, and Campbell Scientific are among the leading vendors, with the top five holding roughly 21.4% combined share.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis relies on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the agricultural sensor value chain, including MEMS and sensing-element suppliers, specialized sensor manufacturers, system integrators, and global distributors. Decision-maker designations interviewed included VP-level Sourcing Leads, Heads of R&D, Technical Directors, and Commercial Operations Leads. Interviews focused on calibration protocols, deployment economics, channel margins, and procurement criteria.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of R&D | 35% |
| VP Sourcing & Procurement | 25% |
| Technical Directors | 25% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Sensing Element & MEMS Suppliers | 30% |
| Specialized Sensor Manufacturers | 40% |
| System Integrators | 20% |
| Global Distributors | 10% |
We validated primary findings against official multilateral databases—UN Comtrade, WTO, US ITC, and Eurostat—alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and technical standards from IEEE and ISO. Trade flow data was used to cross-check regional revenue allocation, while patent filings informed our view on MEMS and LPWAN innovation trajectories.
We applied simultaneous top-down and bottom-up modeling. The top-down approach allocated macroeconomic agricultural output and precision-ag adoption rates to sensor categories. The bottom-up approach modeled manufacturer capacity, average selling prices, and end-use consumption by farm type. Divergences between the two approaches were resolved through weighted averaging and segment-level validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
