 Agricultural Lubricants Market
 Size, Share & Forecast 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 263

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Agricultural Lubricants Market
Atul Bhusare
Research Associate
| Year | Market Size |
|---|---|
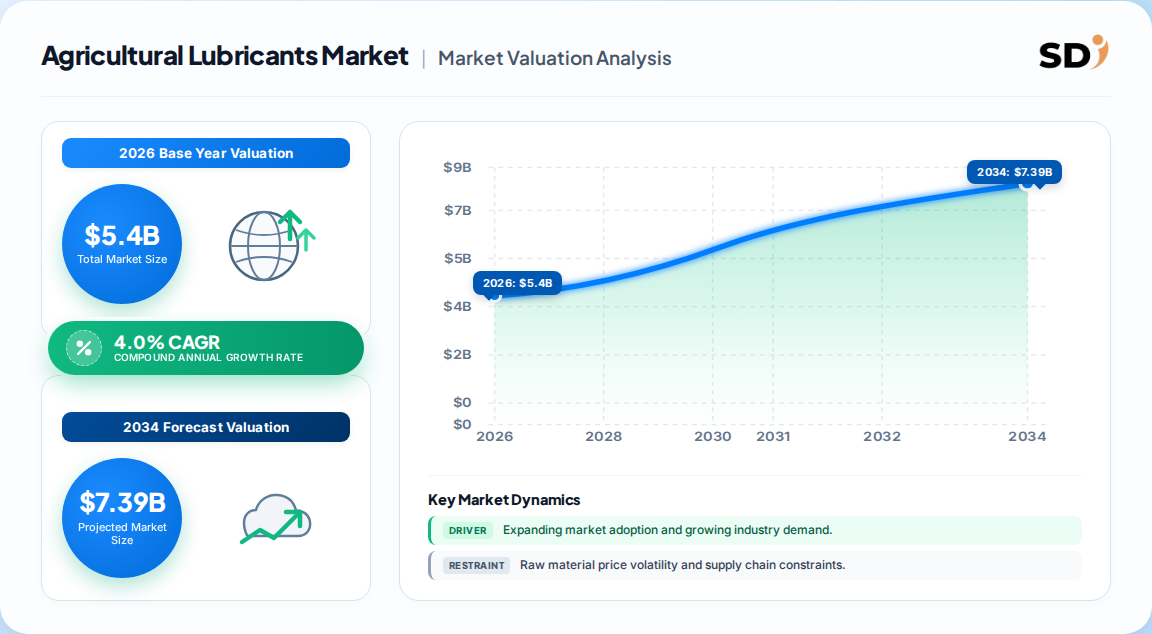
| 2025 | 5.200 B |
| 2026 | 5.400 B |
| 2027 | 5.620 B |
| 2028 | 5.840 B |
| 2029 | 6.080 B |
| 2030 | 6.320 B |
| 2031 | 6.570 B |

Agricultural lubricants are specialty fluids and greases formulated to protect tractors, combine harvesters, sprayers, balers and irrigation systems operating under dust, moisture, heavy load and temperature extremes. They include engine oils, hydraulic fluids, transmission and gear oils and greases, engineered to reduce wear, extend service intervals and preserve fuel efficiency in farm machinery.
This analysis covers finished lubricants consumed by agricultural machinery across engine, hydraulic, transmission, gear and grease categories, split by base-oil chemistry (mineral, synthetic, bio-based) and distribution channel, across five continents. This analysis does not cover industrial or automotive lubricants, base-oil feedstock markets, fuel, DEF/AdBlue, or lubricant additives sold as standalone commodities.
The agricultural lubricants market is defensibly sized at roughly 5.4 Billion USD in 2026, with published estimates diverging by nearly 40% because of base-year vintage and definitional differences rather than genuine disagreement about physical demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 5.2 Billion | 2025 | 2033 | 4.0% | Finished ag lubricants, all base oils, value | Recent published benchmark |
| 5.4 Billion | 2026 | 2033 | 4.0% | Same scope, rolled forward one year | Same publisher, 2026 estimate |
| 3.3 Billion | 2025 | 2034 | 2.77% | Finished ag lubricants, narrower product set | Competing analysis |
| 2.9 Billion | 2021 | 2027 | 2.5% | Older vintage, pre-revision scope | Earlier published edition |
The 5.2–5.4 Billion figures are the most defensible because they reconcile with global tractor and harvester parc estimates and align with observed OEM specification tightening. Our analysis suggests the lower 3.3 Billion figure largely excludes greases and aftermarket specialty channels, which mechanically suppresses value without contradicting underlying volume.
Segmentation runs along three axes — base-oil chemistry, product function and distribution channel — with product function the primary lens because it maps directly to equipment maintenance schedules and procurement budgets.
| Parent segment | Children |
|---|---|
| By Base Oil | Mineral oil-based, Synthetic oil-based, Bio-based |
| By Product | Engine oils, Hydraulic oil, Transmission & gear oils, Greases, Others |
| By Distribution | Offline (dealers, distributors, specialty stores), Online (direct, third-party) |
Engine oil's 51.3% share reflects the simple reality that every powered machine needs crankcase lubricant, while hydraulic fluid demand scales with implement attachment and loader usage. Offline channels still dominate because farmers buy lubricants alongside parts and service, a bundling effect online channels have not broken.
Asia Pacific leads the agricultural lubricants market with roughly 37% of global revenue in 2025, and it is also the fastest-growing region at approximately 3.4% CAGR, driven by rapid mechanization across China, India and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.37% |
| North America | 0.26% |
| Europe | 0.22% |
| Latin America | 0.09% |
| Middle East & Africa | 0.06% |
| Region | 2025 share | Growth posture |
|---|---|---|
| Asia-Pacific | 35–38% | Fastest, mechanization-led |
| North America | 24–26% | Mature, fleet-replacement-led |
| Europe | 21–23% | Regulation-led, bio-based premium |
| Latin America | 9–10% | Volatile, commodity-cycle linked |
| Middle East & Africa | 5–7% | Subsidy and irrigation-led |
Our analysis suggests Europe punches above its volume weight in value because EU-Ecolabel and biodegradable mandates force premium formulation. That creates a margin pool North American vendors cannot access without reformulation.
Mechanization and farm consolidation are the dominant drivers, while raw-material volatility and tightening environmental rules are the principal constraints on margin rather than on volume.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising farm mechanization | Driver | Strong | Larger machinery parc raises lubricant consumption per hectare |
| Commercial agribusiness expansion | Driver | Strong | Fleet-scale operations demand consistent, premium specification supply |
| Precision and smart farming | Driver | Moderate | Higher-spec machinery requires tighter lubricant performance |
| Government subsidies for equipment | Driver | Moderate | Directly lifts tractor and harvester sales in developing markets |
| Base-oil and additive price volatility | Restraint | Strong | Compresses manufacturer margin and raises contract renegotiation risk |
| Environmental regulation on formulations | Restraint | Moderate | Compliance cost and reformulation burden, especially in Europe |
| Bio-based demand shift | Opportunity | Moderate | Premium pricing but feedstock cost and performance trade-offs persist |
The balance favors volume growth over price growth. This divergence implies lubricant manufacturers should hedge base-oil exposure and pre-qualify bio-based formulations early, because regulation will migrate from Europe outward faster than most portfolios can adapt.
The competitive field is dominated by integrated oil majors with global distribution, contested by specialty lubricant houses that win on formulation depth and OEM technical approvals.
| Vendor | Positioning | Differentiation |
|---|---|---|
| Shell | Global integrated | Broad OEM approvals, premium brand equity |
| ExxonMobil | Global integrated | Synthetic leadership and technical service depth |
| BP | Global integrated | Scale distribution and aftermarket reach |
| Chevron | Global integrated | Heavy-duty engine oil strength |
| TotalEnergies | Global integrated | European regulatory alignment |
| FUCHS | Specialty formulator | Application engineering and niche grades |
| Valvoline | Specialty and retail | Channel brand and installer relationships |
| Petro-Canada | Specialty | Severe-duty and extreme-climate formulations |
| Condat | Specialty | Bio-based and European compliance focus |
Our analysis suggests the real moat is not formulation chemistry but OEM technical approval and dealer shelf position. Majors own approvals; specialists own technical credibility; distributors control the farmer relationship. Acquisition of regional distributors is the fastest route to share.
Buyers should treat lubricant selection as an equipment-lifecycle decision, not a consumable purchase. The dominant selection criteria are OEM specification compliance, viscosity grade availability across seasonal temperature swings, and proven performance under dust and moisture loading. Mis-specification voids warranty coverage and accelerates wear in hydraulic systems, where contamination tolerance is lowest.
Procurement risk concentrates in supply continuity and price variability. Base-oil and additive shortages can force allocation, leaving operators with mismatched grades across mixed fleets — a real maintenance hazard. Contracting on indexed pricing with grade-flexibility clauses mitigates this. Switching costs are moderate: lubricant changes require flushing and OEM notification, so bulk buyers rarely switch mid-season. Regulatory compliance is the binding constraint in Europe, where EOCLabel and EU-Ecolabel specifications restrict formulation options and disposal practice.
The balance of evidence favors a mechanization-led expansion story with a modest-but-durable 4.0% CAGR — not a commodity upcycle. The upward revision from earlier 2.5% vintages reflects genuine structural change: larger machines, tighter specifications and rising bio-based penetration are lifting value per unit of equipment regardless of acreage.
The strongest counter-argument is that raw-material volatility and price-sensitive emerging-market farmers could compress realized pricing faster than volume grows, leaving dollar growth closer to 2.5%. That risk is real in Latin America and parts of Asia, but it is a margin risk, not a demand risk, and it does not alter the strategic direction.
Actionable strategy:
The evidence that would change this conclusion: a sustained sub-3% mechanization growth reading out of China and India, or a regulatory rollback of biodegradable mandates in Europe, either of which would collapse the premium-formulation thesis.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.0% from 2020-2034 |
| Segmentation |
|
The global agricultural lubricants market was valued at 5.2 Billion USD in 2025 and is estimated at 5.4 Billion USD in 2026, with forecast growth to 7.1 Billion USD by 2033 at a 4.0% CAGR.
The market is projected to grow at approximately 4.0% CAGR over the 2026–2033 forecast period, driven primarily by rising farm mechanization rather than acreage expansion.
Asia Pacific holds the largest share at roughly 35–38% of global revenue, led by China, followed by North America at approximately 25% and Europe at roughly 22%.
Engine oil is the largest product segment, accounting for 51.3% of revenue in 2025, reflecting universal crankcase lubricant demand across tractors, harvesters and sprayers.
Base-oil and additive price volatility compresses manufacturer margins, while tightening environmental regulation on formulations adds compliance and reformulation cost, particularly in Europe.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the agricultural lubricant value chain with base-oil and additive suppliers, specialized lubricant formulators and blenders, contract manufacturers, and global and regional distributors serving farm equipment dealers. Interviewees were selected at decision-maker level, including VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring that both formulation economics and channel dynamics were captured directly.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 40% |
| Commercial & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Base Oil & Additive Suppliers | 30% |
| Specialized Formulators & Blenders | 40% |
| Distributors & Dealers | 30% |
Figurings were cross-checked against multilateral trade databases including UN Comtrade and WTO statistics, US ITC and Eurostat trade flows, corporate annual filings and 10-K disclosures, patent databases tracking bio-lubricant formulation activity, and recognized technical standards bodies such as ISO and ASTM alongside national agricultural machinery associations.
Top-down allocation from macroeconomic agricultural machinery production and fleet data was run simultaneously with bottom-up modeling of formulator capacity, product pricing and end-use consumption per machine-hour. Divergences between the two approaches were reconciled at the regional and product-segment level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
