 Irrigation Controllers Market
 Outlook 2025
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 229

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Irrigation Controllers Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2024 | 1.300 B |
| 2025 | 1.470 B |
| 2026 | 1.650 B |
| 2027 | 1.860 B |
| 2028 | 2.100 B |
| 2029 | 2.370 B |
| 2030 | 2.670 B |

The irrigation controllers market covers devices that automate watering schedules by activating valves — from fixed clock timers to weather-based and soil-moisture-responsive smart controllers with cloud analytics, remote monitoring and evapotranspiration inputs.
This analysis covers irrigation controllers across weather-based, sensor-based and basic/clock categories, segmented by product, irrigation type and application across agriculture and non-agriculture end uses. It includes hardware plus embedded connectivity and software layers where bundled. This analysis does not cover irrigation valves, pumps, dripline or emitter hardware as standalone categories, nor does it cover municipal water utility metering or desalination infrastructure.
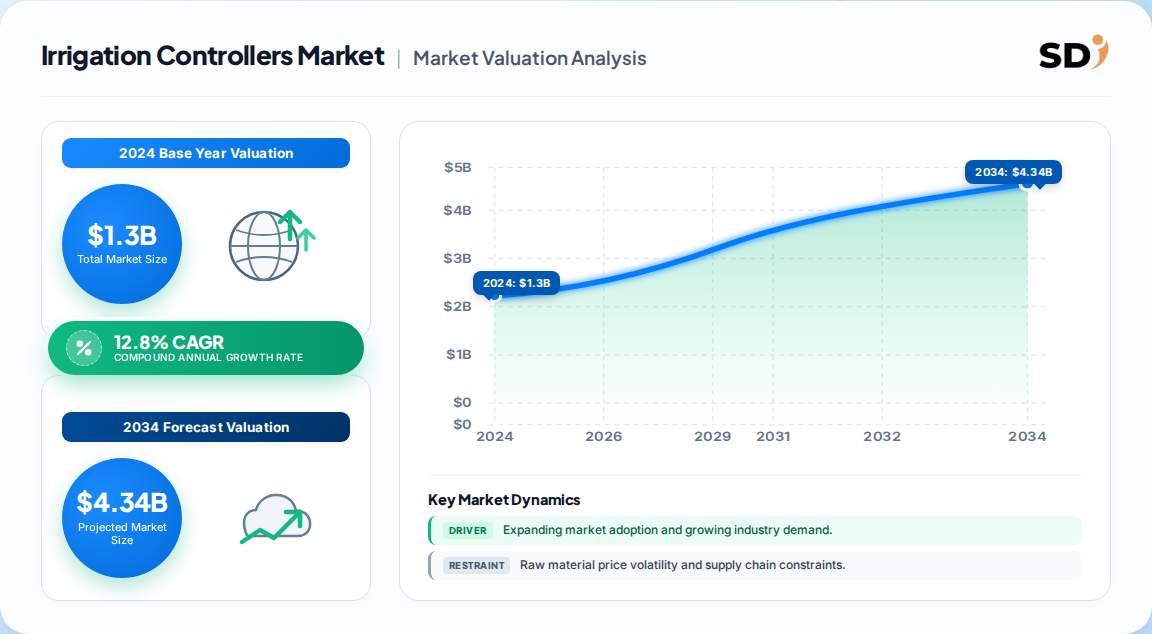
Global irrigation controllers revenue was approximately USD 1.3 Billion in 2024, and published forecasts converge on USD 4.3 Billion by 2034 at a 12.8% compound rate — a roughly 3.3x expansion in a decade.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.3 Billion | 2024 | 2034 | 12.8% | Controllers incl. smart, tap timer, basic; hardware-led | One published estimate |
| USD 1.32 Billion | 2024 | 2032 | 13.40% | Controllers by type, irrigation type, product, application | A competing analysis |
| USD 3.74 Billion (terminal) | 2024 | 2032 | 13.40% | Same segmentation, shorter horizon | A competing analysis |
| USD 4.3 Billion (terminal) | 2024 | 2034 | 12.8% | Same segmentation, extended horizon | One published estimate |
Our analysis suggests the two base values are effectively identical and the CAGR gap is 60 basis points — a difference attributable to horizon length rather than methodology. The longer 2034 horizon is more defensible for capital planning because it spans a full replacement cycle for smart controllers, whereas 2032 truncates the installed-base refresh. Buyers should treat USD 1.3 Billion as the anchor and 12.8–13.4% as the planning corridor.
Segment definitions matter more than segment labels here: controller value concentrates where scheduling intelligence and connectivity sit, not where the valve does.
| Parent Segment | Children | 2024 Share Signal |
|---|---|---|
| By Type | Weather-based, Sensor-based, Others | Weather-based 54.8% |
| By Product | Smart controllers, Tap timers, Basic controllers | Smart controllers 66.6% |
| By Irrigation Type | Drip/trickle, Sprinkler, Others | Drip/trickle 59.1% |
| By Application | Agriculture (open field, controlled environment), Non-agriculture (residential, golf/sports turf, others) | Agriculture 67.3% |
Two observations follow. First, product share (smart at 66.6%) runs materially ahead of type share (weather-based at 54.8%), implying roughly a fifth of smart controllers are sensor- or ET-driven without a weather-forecast service subscription — a monetisation gap. Second, drip dominates irrigation type because it delivers the highest water-savings payback per controller dollar, which is why subsidy programmes channel into it.
North America led in 2024 with 42.9% of global revenue (about USD 0.6 Billion), driven by WaterSense-labelled rebate programmes, golf and commercial landscape penetration, and large-farm automation.
| Region | Market Share (%) |
|---|---|
| North America | 0.4% |
| Europe | 0.19% |
| Asia-Pacific | 0.26% |
| Latin America | 0.08% |
| Middle East & Africa | 0.07% |
| Region | Share |
|---|---|
| North America | 40% |
| Europe | 19% |
| Asia-Pacific | 26% |
| Latin America | 8% |
| Middle East & Africa | 7% |
Our analysis suggests North America's lead is a policy artefact as much as a technology one: EPA WaterSense replacement savings of up to 15,000 gallons per household per year create a measurable customer rebate case that other regions lack at scale. Asia Pacific is the fastest-growing region and will likely compress North America's share, but not its absolute revenue, through 2034.
Water stress plus public cost-sharing is the dominant growth engine; rural connectivity deficits are the binding constraint, not farmer willingness to pay.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Agricultural water intensity (~70–72% of freshwater withdrawals) | Driver | Strong (FAO) | Forces scheduling efficiency |
| USDA EQIP + Inflation Reduction Act conservation funding | Driver | Strong (public filings) | Cuts upfront capex, accelerates timing |
| India Micro Irrigation Fund (₹5,000 crore corpus) | Driver | Strong (PIB/NABARD) | Expands drip installed base feeding controllers |
| Municipal rebate and code programmes | Driver | Moderate | Pull-through residential replacement |
| Rural internet access (~48% of rural population, 2024) | Restraint | Strong (ITU) | Blocks cloud-linked control |
| Low-income 5G coverage (~4% vs 84% high-income) | Restraint | Strong (ITU) | Structurally caps emerging-market uptake |
| Digital-literacy and installer skill gaps | Restraint | Moderate | Raises commissioning failure risk |
The balance favours growth: subsidised demand is contractual rather than discretionary, and water-efficiency documentation increasingly gates project approval. The counterweight is real but geographically ring-fenced — connectivity-constrained smallholder segments will lag, so volume growth will be bifurcated rather than uniform.
The competitive field is hardware-anchored and moderately concentrated: the top five players held roughly 51% of the adjacent smart irrigation market in 2025, with Rain Bird above 15%.
| Company | Archetype | Basis of differentiation |
|---|---|---|
| Rain Bird Corp. | Irrigation specialist | Brand, contractor channel, WaterSense-certified portfolio |
| Netafim Ltd. | Drip systems leader | Drip-integrated control, agronomic services |
| Hunter Industries | Irrigation specialist | Residential/commercial turf strength, sensors |
| The Toro Company | Diversified turf/ag | Golf and landscape dealer network |
| Valmont / Valley Irrigation | Pivot & infrastructure | Large-farm automation, telemetry integration |
| Lindsay Corporation | Pivot & infrastructure | Remote pivot management |
| HydroPoint Data Systems | Software-led | WeatherTRAK cloud scheduling, water reporting |
| Galcon, Orbit, Holman | Value-tier | Tap timers and entry-level smart units |
Our analysis suggests moats sit in two places: the installer/contractor channel and the agronomic data set behind scheduling algorithms. Pure hardware IP is decaying — differentiated vendors are those converting installed controllers into subscription water-management relationships.
Selection should be driven by water-savings documentation and interoperability, not by controller feature lists. Buyers funding through subsidy programmes should confirm the model qualifies for the relevant rebate or cost-share schedule before procurement — non-qualifying hardware silently destroys the payback case.
Switching costs are moderate and asymmetric: replacing a controller is cheap, but migrating historical scheduling rules, sensor pairings and zone maps across platforms is not. That lock-in favours vendors with open APIs and penalises closed ecosystems. Procurement risk concentrates in connectivity — where rural bandwidth is absent, specify locally-stored schedule logic with store-and-forward telemetry rather than cloud-dependent control.
Regulatory compliance is increasingly evidential: efficiency programmes and lenders require auditable water-use records, so controllers that log and export consumption data carry a lower compliance burden. Installer competence is the most under-priced risk; commissioning errors are the leading cause of unrealised savings.
The balance of evidence favours a hardware-to-software margin pivot. With smart controllers at 66.6% of product revenue and weather-based at only 54.8% of type revenue, a meaningful slice of installed smart units are generating no recurring subscription revenue. Meanwhile, subsidised demand from EQIP, WaterSMART and India's Micro Irrigation Fund is durable but price-elastic, meaning hardware ASPs will erode as volume accelerates.
The strongest counter-argument is that connectivity gaps and cost-sensitive smallholders make software monetisation uneconomic outside high-income markets — and that is partly true. But it argues for tiered architecture, not for abandoning recurring revenue; offline-capable controllers with paid analytics sync still capture value in latency-tolerant segments.
Actionable strategy:
What would change our conclusion: a sustained decline in smart-controller attach rates below 60%, or evidence that subsidy programmes shift from controller-level to system-level procurement, would compress the software opportunity materially. Precisely quantifying that shift requires zone-level forecasting beyond this overview.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.8% from 2020-2034 |
| Segmentation |
|
The global irrigation controllers market was valued at approximately USD 1.3 Billion in 2024 and is projected to reach USD 4.3 Billion by 2034, growing at a 12.8% CAGR. A competing analysis puts the market at USD 3.74 Billion by 2032.
Smart controllers dominate with 66.6% of product revenue, weather-based units lead by type at 54.8%, and agriculture accounts for 67.3% of total application demand. Drip/trickle irrigation holds 59.1% of irrigation-type value.
North America led in 2024 with 42.9% of global revenue, roughly USD 0.6 Billion, supported by WaterSense rebate programmes and high golf, landscape and large-farm automation penetration. Asia Pacific is the fastest-growing region.
Leading vendors include Rain Bird, Netafim, Hunter Industries, The Toro Company and Valmont/Valley Irrigation, which together held about 51% of the adjacent smart irrigation market in 2025, with Rain Bird above 15%.
Rural connectivity is the binding constraint: only 48% of rural populations used the internet in 2024, and 5G coverage reached just 4% in low-income countries versus 84% in high-income economies, limiting cloud-linked controller deployment.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research programme maintains a deliberate 70/30 primary-to-secondary split. Primary fieldwork comprised structured depth interviews across the controller value chain, spanning semiconductor and communications module suppliers, controller OEMs, sensor and valve manufacturers, system integrators/installers, and agricultural distributors. Interviews were conducted with decision-makers holding direct procurement and specification authority, specifically VP-level Sourcing leads, Heads of Product and R&D, Technical Directors for irrigation systems, and Commercial Operations Leads responsible for channel and rebate programme alignment. Fieldwork was sequenced to validate segment definitions before sizing, avoiding retrospective reconciliation errors.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & R&D Directors | 38% |
| Procurement & Sourcing Leads | 32% |
| Commercial & Channel Operations | 18% |
| Compliance & Programme Managers | 12% |
| Company Type | Representation (%) |
|---|---|
| Controller OEMs & Hardware Manufacturers | 40% |
| Component & Connectivity Suppliers | 25% |
| Distributors & Installers | 22% |
| Software & Platform Providers | 13% |
Secondary validation draws on official multilateral and national databases, including UN Comtrade for cross-border irrigation equipment flows, US ITC and Eurostat trade statistics, and municipal and federal conservation programme records. Corporate 10-K filings and investor presentations from listed irrigation and infrastructure manufacturers were used to anchor capacity and product-mix estimates. Patent filings informed our assessment of where scheduling-intelligence IP is concentrating, while non-profit technical standards bodies and irrigation industry associations provided definitional consistency across regions.
We run top-down and bottom-up models simultaneously. The top-down model allocates macroeconomic irrigation and landscape spend by segment and region; the bottom-up model builds from manufacturer capacity, average selling prices, and end-use consumption across agriculture, residential and turf segments. Divergence between models is resolved through trade-flow reconciliation and subsidy-programme acreage data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, filings | High |