 Us Vertical Farming Market
US Vertical Farming Market: Size, CAGR & 2031 Outlook
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 181

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Vertical Farming Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 1.530 B |
| 2026 | 1.580 B |
| 2027 | 1.750 B |
| 2028 | 1.940 B |
| 2029 | 2.140 B |
| 2030 | 2.370 B |
| 2031 | 2.620 B |

The US vertical farming market encompasses controlled-environment agriculture (CEA) systems that grow crops in vertically stacked layers within buildings, warehouses, or shipping containers. It utilises hydroponic, aeroponic, or aquaponic mechanisms to produce leafy greens, herbs, microgreens, and increasingly fruits and berries, serving retail, foodservice, and pharmaceutical end users across the United States.
This report covers the US vertical farming market for the forecast period 2026–2031, segmented by growth mechanism, structure, crop type, component, and end user. It analyses market sizing, growth drivers, restraints, competitive landscape, and regional dynamics within the United States. This analysis does not cover conventional open-field agriculture, greenhouse farming (unless vertically integrated), or ancillary markets such as agricultural inputs and traditional distribution logistics.
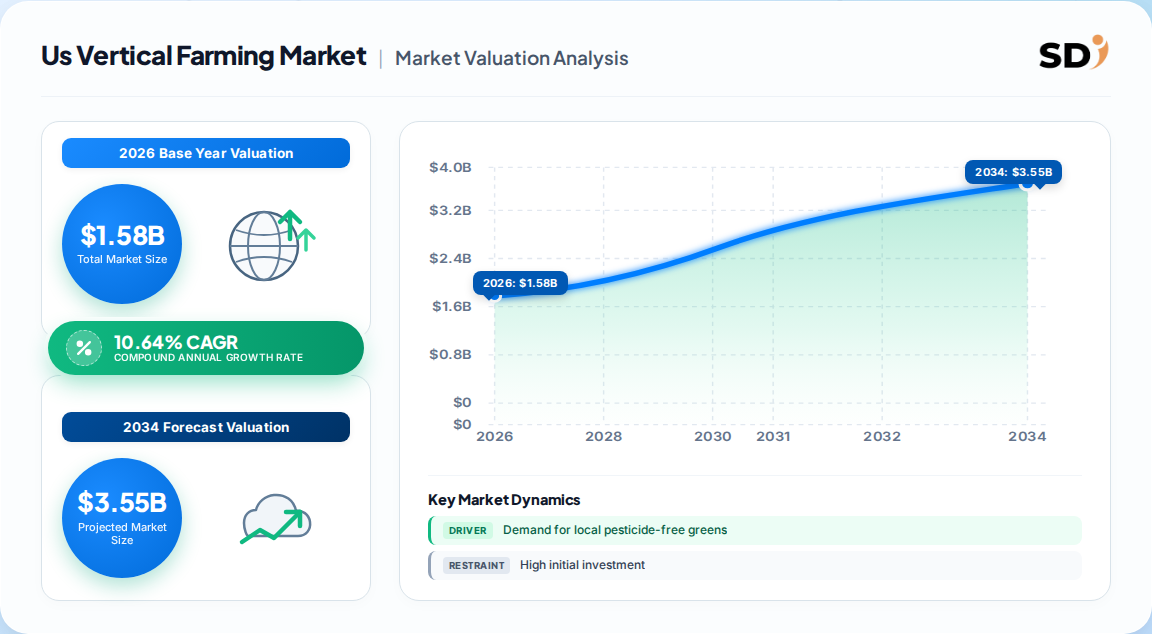
The US vertical farming market is most defensibly sized at USD 1.58 billion in 2026, growing to USD 2.62 billion by 2031 at a 10.64% CAGR. Competing estimates vary significantly due to scope differences and varying definitions of vertical farming versus broader CEA.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 1.58 billion | 2026 | 2031 | 10.64% | US vertical farming, structured CEA | Industry reference document |
| USD 1.73 billion | 2023 | 2033 | 22.8% | US vertical farming, broader technology scope | Competing analysis |
| USD 9.6 billion (global) | 2025 | 2033 | 19.3% | Global vertical farming, hardware-inclusive | Global benchmark study |
| USD 1.53 billion | 2025 | 2031 | 10.6% | US vertical farming, base year calibration | Industry reference document |
Our analysis suggests the 10.64% CAGR figure is the most defensible for the US market specifically. The higher 22.8% CAGR estimate likely overstates near-term growth by conflating global market dynamics with US-specific conditions and by including broader CEA categories. The lower-cost, retailer-backed model now dominating US vertical farming supports steady, double-digit growth rather than exponential expansion.
The US vertical farming market is segmented by growth mechanism, structure, crop type, component, and end user. Hydroponics leads the growth mechanism segment, while building-based structures dominate, and leafy greens remain the primary crop category.
| Parent Segment | Sub-Segments |
|---|---|
| Growth Mechanism | Hydroponics, Aeroponics, Aquaponics |
| Structure | Building-Based, Warehouse, Container |
| Crop Type | Leafy Greens, Herbs, Microgreens, Fruits & Berries, Others |
| Component | Hardware (Lighting, Hydroponic Components, Climate Control, Sensors), Software, Services |
| End User | Retail & Supermarkets, Foodservice, Pharmaceutical & Cosmetic, Others |
Hardware accounts for 63.7% of the component market in 2025, underscoring the capital-intensive nature of vertical farming infrastructure. Software is the fastest-growing component at 12.4% CAGR, driven by AI-assisted spectral control and crop recipe optimisation. This divergence implies that while hardware remains the revenue backbone, software is becoming the differentiation lever for operational efficiency and crop-mix expansion.
The Northeast leads the US vertical farming market, driven by dense urban populations, high fresh-produce turnover, and strong retail procurement standards for pesticide-free greens.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.24% |
| West | 0.22% |
| South | 0.21% |
| Midwest | 0.19% |
| Southwest | 0.14% |
The Northeast and West Coast urban corridors represent the strongest retail pull, where premium fresh produce turns faster and shelf-life losses carry direct margin implications. Our analysis suggests the West will gain share through the forecast period as water security shapes sourcing decisions in California, Arizona, and Colorado, with spillover demand in Texas.
The primary growth driver is retail demand for local, pesticide-free greens, contributing +2.3% to CAGR. This is reinforced by food-mile reduction (+1.5%), water-efficient production under drought pressure (+1.2%), and retailer demand for year-round supply resilience (+1.6%). Renewable power contracting (+0.9%) and AI-enabled premium fruit crops (+1.1%) provide long-term upside.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Local pesticide-free greens demand | Driver | High | Retail procurement standards favour zero-pesticide indoor farms |
| Food-mile reduction & same-day freshness | Driver | High | Proximity sourcing reduces postharvest losses by 18–22% |
| Water-efficient production | Driver | Medium | Hydroponic lettuce uses 140g/L vs. 15.3g/L in open field |
| Retailer year-round supply resilience | Driver | High | Weather-related field crop disruptions drive indoor contracts |
| High initial investment | Restraint | High | Capital-intensive infrastructure limits new entrants |
| Limited crop varieties | Restraint | Medium | Leafy greens dominate; fruits and berries still scaling |
| Funding tightness | Restraint | Medium | Venture capital discipline post-2024 reset |
On balance, drivers outweigh restraints. The pesticide-free standard is now a contractual requirement for major grocery chains, not a consumer preference. However, the high initial investment and limited crop varieties mean operators must achieve scale quickly or face margin pressure. Our analysis suggests the market is bifurcating: well-capitalised operators with retail contracts will thrive, while sub-scale farms will struggle.
The US vertical farming market is moderately concentrated, with Bowery Farming, AeroFarms, Gotham Greens, Plenty Unlimited, and 80 Acres Farms leading the competitive landscape. These players have secured retail partnerships, renewable power contracts, and AI-assisted crop recipes that create defensible moats.
| Company | Specialisation | Structure | Key Differentiator |
|---|---|---|---|
| Bowery Farming | Leafy greens, herbs | Building-based | AI-driven growth recipes, retail partnerships |
| AeroFarms | Leafy greens, microgreens | Building-based | Aeroponic technology, brand recognition |
| Gotham Greens | Leafy greens, herbs | Greenhouse + vertical | Regional distribution, premium retail presence |
| Plenty Unlimited | Leafy greens, berries | Building-based | High-density vertical architecture, berry expansion |
| 80 Acres Farms | Leafy greens, microgreens | Building-based | Renewable power contracts, Midwest expansion |
Differentiation is shifting from technology to supply reliability and cost visibility. Companies with renewable power contracts and microgrid arrangements can better manage electricity cost volatility, which is a critical margin factor. Our analysis suggests the moat is moving toward retail category management and supply assurance, not merely technological sophistication.
Buyers and operators must prioritise supply reliability over technology novelty when selecting vertical farming partners. The market's shift to a retailer-backed model means contracts are increasingly awarded based on consistent, year-round delivery of pesticide-free produce, not pilot programmes. Operators should evaluate renewable power contracts and microgrid arrangements as critical cost-control mechanisms, given electricity's outsized impact on margins.
Procurement risks include sub-scale vendor failure—the 2022–2024 reset eliminated several operators, and funding tightness persists. Buyers should conduct balance-sheet due diligence and seek multi-sourcing arrangements to avoid supply disruption. Regulatory compliance is relatively straightforward for pesticide-free and organic claims, but water-use certifications are becoming a procurement standard in drought-prone western states.
Switching costs are moderate: retail buyers can pivot between vertical farms, but same-day freshness contracts create regional lock-in. Operators should focus on AI-assisted spectral control and pollination technology to expand crop mixes into berries and premium formats, which offer higher margins than leafy greens.
The balance of evidence favors a steady-growth, consolidation-driven thesis for the US vertical farming market. The 10.64% CAGR reflects a market that has matured beyond venture-funded experimentation, with retailers treating indoor greens as a supply-continuity option rather than a premium niche. This is a healthier foundation for durable growth, even if headline growth rates are lower than earlier forecasts.
The strongest counter-argument is that AI-enabled premium fruit crops could accelerate growth beyond 10.64%, particularly if berries achieve commercial scale in New Jersey, Virginia, and California. We assign a moderate probability to this upside scenario, but it would require breakthroughs in pollination and spectral control that are not yet proven at scale. A second counter-argument is that water stress in western agriculture could drive faster adoption, but this depends on policy and pricing signals that remain uncertain.
Actionable Strategy:
The evidence that would change our conclusion: a sustained breakthrough in berry pollination at commercial scale or a major retailer shifting from regional contracts to national single-source agreements. Either would materially alter the competitive landscape and growth trajectory.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.64% from 2020-2034 |
| Segmentation |
|
The US vertical farming market is valued at USD 1.58 billion in 2026, according to industry benchmarks. This reflects the market's recovery from the 2022–2024 consolidation phase, with a smaller set of better-capitalised operators holding stronger balance sheets.
The market is growing at a 10.64% CAGR over the 2026–2031 forecast period. This steady growth reflects the transition from venture-funded experimentation to a retailer-backed, supply-assurance model with more disciplined site selection.
Hydroponics dominates the growth mechanism segment with 56.8% share in 2025, while building-based farms lead the structure segment with 68.6% share. Leafy greens remain the largest crop type at 52.3% share of the market.
Bowery Farming, AeroFarms, Gotham Greens Holdings, Plenty Unlimited, and 80 Acres Farms are the major companies operating in the US vertical farming market. These players have secured retail partnerships and renewable power contracts that create competitive moats.
Growth is driven by retail demand for local, pesticide-free greens, food-mile reduction, water-efficient production under western drought pressure, and retailer demand for year-round supply resilience. Renewable power contracts and AI-assisted crop recipes are improving economics.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, ensuring that market estimates are grounded in direct industry validation. In-depth interviews were conducted with key stakeholders across the US vertical farming value chain, including controlled-environment agriculture (CEA) technology providers, hydroponic and aeroponic system manufacturers, produce growers and operators, retail procurement teams, and renewable energy contractors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, Commercial Operations Leads, and Retail Category Managers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement Directors | 35% |
| Heads of R&D & Technical Directors | 30% |
| Commercial Operations Leads | 25% |
| Retail Category Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| CEA Technology & Equipment Providers | 40% |
| Vertical Farming Growers & Operators | 35% |
| Retail & Foodservice Buyers | 15% |
| Renewable Energy & Infrastructure Contractors | 10% |
Our benchmarking leveraged official multilateral trade and standards databases, including UN Comtrade, WTO, US International Trade Commission (USITC), and Eurostat, alongside corporate annual filings (10-K, SEC filings, annual investor presentations). Patent databases were analysed for innovation trends in LED lighting, spectral control, and aeroponic systems. Recognised non-profit technical standards and industry associations, including the USDA Urban Agriculture and Innovative Production programme and ASTM International standards for controlled-environment agriculture, were referenced for regulatory and compliance validation.
We employ simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) data triangulation. This dual approach ensures that market sizing is validated from both macro-level demand signals and micro-level operational data, including facility capacity utilisation, crop yield per square metre, and retail offtake volumes.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |