Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Seed Treatment Market Size, Share & Growth Outlook 2026
Seed Treatment Market Size, Share & Growth Outlook 2026
Seed Treatment Market
Seed Treatment Market Size, Share & Growth Outlook 2026
Seed Treatment Market by Function (Fungicide, Insecticide, Nematicide), by Crop Type (Grains and Cereals, Pulses and Oilseeds, Commercial Crops, Fruits and Vegetables, Turf and Ornamental), by Formulation (Chemical, Biological, Polymer-Enhanced), by Application (Seed Coating, Seed Dressing, Seed Pelleting), by South America (Brazil, Argentina, Chile, Colombia), by North America (United States, Canada, Mexico), by Europe (Germany, France, UK, Italy, Spain, Netherlands), by Asia-Pacific (China, India, Japan, Australia, Southeast Asia), by Middle East & Africa (South Africa, Saudi Arabia, UAE, Egypt) Forecast 2026-2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 191
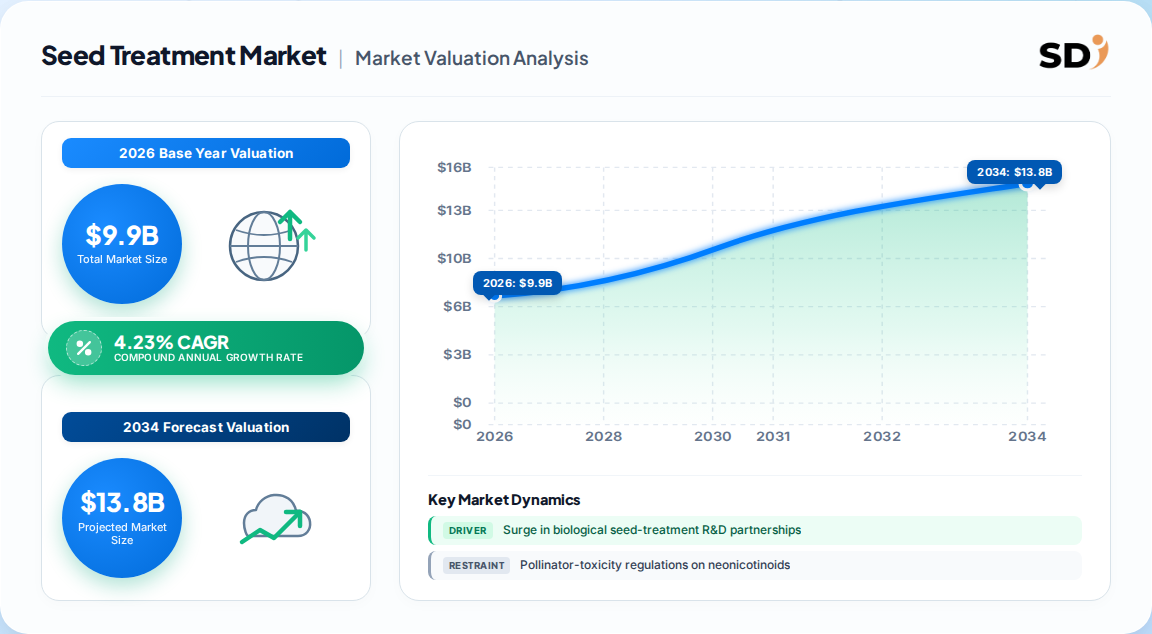
9.90 Billion: The global seed treatment market is valued at USD 9.90 billion in 2026, with scope covering all major regions and crop types.
12.18 Billion by 2031: Forecast to reach USD 12.18 billion by 2031, representing a 4.23% CAGR over the 2026–2031 period.
Insecticides dominate: Insecticides held a 71.35% share by function in 2025, projected to grow at 4.61% CAGR—the fastest functional segment.
Grains & cereals lead: Grains and cereals accounted for 41.75% of market size in 2025; pulses and oilseeds are forecast to grow at 4.48% CAGR.
South America largest; North America fastest: South America captured 44.10% of the 2025 market share, while North America is forecast to expand at 4.66% CAGR.
Moderate concentration: The top five suppliers—BASF, Bayer, Corteva, FMC, and Syngenta—hold less than 50% of global revenue, leaving room for specialists.
Why this matters for decision-makers: Vendors must pivot toward biological formulations and precision-agriculture integration to avoid margin compression from regulatory restrictions on synthetic chemistries.
Seed Treatment Market Size (In Billion)
15.0B
10.0B
5.0B
0
9.900 B
2026
10.32 B
2027
10.76 B
2028
11.21 B
2029
11.69 B
2030
12.18 B
2031
Seed Treatment Market Size (In Billion)
Year
Market Size
2026
9.900 B
2027
10.32 B
2028
10.76 B
2029
11.21 B
2030
11.69 B
2031
12.18 B
What is the Seed Treatment Market?
The seed treatment market encompasses chemical and biological substances applied to seeds before planting to protect against diseases, pests, and environmental stresses. It includes fungicides, insecticides, nematicides, and biological agents that improve germination, seedling vigor, and crop yields across commercial and food crops.
Scope: what this report covers and excludes
This analysis covers the global seed treatment market segmented by function (fungicides, insecticides, nematicides), crop type (grains and cereals, pulses and oilseeds, commercial crops, fruits and vegetables, turf and ornamental), and geography (North America, South America, Europe, Asia-Pacific, Middle East & Africa). This analysis does not cover foliar crop protection, soil fumigants, or post-harvest treatments, which are distinct adjacent markets with different application timing and regulatory pathways.
How big is the market for Seed Treatment Market?
The seed treatment market is estimated at USD 9.90 billion in 2026, with forecasts reaching USD 12.18 billion by 2031 at a 4.23% CAGR. This moderate growth reflects market maturity in developed regions offset by regulatory-driven substitution toward biologicals.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 9.90 Billion
2026
2031
4.23%
Global seed treatment, broad function and crop scope
One published estimate
USD 9.5 Billion
2025
—
—
Historical base for the above series
Same source, prior year
USD 9.2 Billion
2027
2027
8.3%
Global seed treatment, narrower chemical focus
A competing analysis
USD 1.74 Billion
2025
2035
12.0%
Biological seed treatment sub-segment only
A specialized segment analysis
The USD 9.90 billion figure is the most defensible for the total market because it aligns with the 2025 base of USD 9.5 billion and a consistent 4.23% CAGR. The 8.3% CAGR cited in a competing analysis implies a much larger 2027 figure than the base-to-forecast trajectory supports; our analysis suggests that estimate uses a narrower scope or different base-year definition. The 12.0% CAGR belongs to the biological sub-segment, not the total market—conflating the two would overstate total growth by nearly threefold.
How is the market segmented?
The seed treatment market is segmented by function, crop type, and application method, with biological formulations emerging as a distinct cross-cutting category within each.
Parent Segment
Children
By Function
Fungicide, Insecticide, Nematicide
By Crop Type
Grains and Cereals, Pulses and Oilseeds, Commercial Crops, Fruits and Vegetables, Turf and Ornamental
By function, insecticides lead with 71.35% share in 2025, growing at 4.61% CAGR. Grains and cereals dominate crop type at 41.75% of 2025 market size, while pulses and oilseeds are the faster-growing crop segment at 4.48% CAGR. Biological formulations—including microbial and botanical types—represent the fastest-growing cross-cutting category, with the biological seed treatment sub-segment projected to grow at 12.0% CAGR through 2035, driven by regulatory restrictions on synthetic chemistry.
Which region leads in Seed Treatment Market?
South America leads the global seed treatment market with 44.10% share in 2025, driven by intensive soybean and corn acreage in Brazil and Argentina. North America is the fastest-growing region at 4.66% CAGR, followed by Asia-Pacific.
Seed Treatment Market Regional Market Share
Loading chart...
Seed Treatment Market Regional Market Share
Region
Market Share (%)
North America
0.28%
Europe
0.24%
Asia-Pacific
0.22%
South America
0.18%
Middle East & Africa
0.08%
Parent Region
Key Countries
South America
Brazil, Argentina, Chile, Colombia
North America
United States, Canada, Mexico
Europe
Germany, France, UK, Italy, Spain, Netherlands
Asia-Pacific
China, India, Japan, Australia, Southeast Asia
Middle East & Africa
South Africa, Saudi Arabia, UAE, Egypt
The South American dominance reflects the region's high treatment rates on soybean and corn, where seed-applied nematicides and insecticides are standard practice. North America's faster growth is underpinned by precision-agriculture adoption and a shift toward biological seed treatments, particularly in the U.S. corn belt. Europe's market is shaped by stringent regulatory limits on neonicotinoids, which have accelerated substitution toward biological and polymer-encapsulated alternatives. Asia-Pacific offers long-term volume growth but faces farmer hesitancy over premium-coating costs.
What is driving growth — and what is holding it back?
Growth is driven by biological R&D partnerships, precision-agriculture micro-dosing, polymer encapsulation for reduced dust-off, and regulatory incentives for low-residue coatings. Restraints include pollinator-toxicity regulations on neonicotinoids, farmer hesitancy over premium-coating costs, and shelf-life challenges for microbial formulations.
Factor
Direction
Evidence Strength
Mechanism
Surge in biological seed-treatment R&D partnerships
Driver
Strong (+0.8% CAGR)
Shortens product-development cycles and diversifies options
Precision-agriculture driven micro-dosing demand
Driver
Strong (+0.7% CAGR)
Variable-rate seeding tailors active-ingredient loads to soil data
Shift to polymer encapsulation for reduced dust-off
Driver
Moderate (+0.6% CAGR)
Cuts particulate emissions >70%, meets EU/North America thresholds
EU Regulation 2023/2055 phases out synthetic polymer microparticles
Growth in GMO and high-value hybrid seed adoption
Driver
Strong (+0.9% CAGR)
Protects expensive seed investments from day one
Pollinator-toxicity regulations on neonicotinoids
Restraint
Strong (-0.9% CAGR)
Bans and restrictions in Europe and Canada remove established products
Farmer hesitancy over premium-coating costs
Restraint
Moderate (-0.6% CAGR)
Limits adoption among smallholders in Asia Pacific and Africa
Shelf life challenges of microbial formulations
Restraint
Moderate (-0.4% CAGR)
Hot-climate regions face viability constraints
The balance of drivers and restraints yields a net positive but moderate growth trajectory of 4.23% CAGR. The strongest single driver—GMO and hybrid seed adoption at +0.9%—is offset by the strongest restraint—neonicotinoid regulations at -0.9%. This near-cancellation at the top end implies the market's growth is increasingly dependent on biological substitution and precision-agriculture integration rather than volume expansion in traditional chemical treatments. Our analysis suggests that vendors unable to transition their portfolios toward compliant chemistries and biologicals will face structural headwinds exceeding the headline CAGR.
Who are the leading vendors?
The seed treatment market is moderately concentrated, with the top five suppliers—BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, and Syngenta Group—accounting for less than 50% of global revenue.
Company
Primary Strength
Differentiation
BASF SE
Broad portfolio, functional fungicides and insecticides
Strong R&D pipeline; integrated seed solutions
Bayer AG
Seed and trait platform integration
Combined seed-treatment offering with digital agronomy
Corteva Agriscience
Seed-applied technologies; biologicals
Center for Seed Applied Technologies; proprietary germplasm
FMC Corporation
Precision-applied solutions and insecticides
23% growth in precision-applied solutions in 2024
Syngenta Group
Biologicals and chemical seed treatments
NUELLO iN biological partnership; global distribution
The competitive landscape is in flux as strategic alliances between agrochemical majors and biotech start-ups shorten product-development cycles. Corteva's specialized seed-applied technology labs and Syngenta's biological partnerships exemplify the shift toward integrated, multi-modal offerings. Moderate concentration leaves headroom for specialized players that combine proprietary microorganisms with advanced coating chemistries and bundled agronomic services. Our analysis suggests that differentiation is shifting from active-ingredient chemistry to formulation technology and data-enabled application, where smaller innovators can compete on service and sustainability rather than scale.
What do buyers and operators need to know? (Decision Support)
Buyers evaluating seed treatment products must prioritize regulatory compliance, formulation stability, and compatibility with precision-agriculture equipment. The phase-out of synthetic polymer microparticles under EU Regulation 2023/2055 and the restriction of neonicotinoids in Europe and Canada mean that procurement decisions made on legacy chemistry face obsolescence risk within 2–3 years. Formulators should verify that biological products maintain shelf life across the intended climate zone, particularly in hot-climate regions where microbial viability is challenged.
Switching costs are moderate to high: seed treatment is typically applied at the seed company or distributor level, and changing formulations may require re-validation of germination rates, dust-off profiles, and compatibility with existing coating equipment. Operators should request third-party efficacy data and confirm that products meet ISO 14001 environmental management standards if targeting export-oriented growers. The growing integration of seed treatments with variable-rate seeding systems means that data compatibility—not just agronomic performance—is becoming a procurement criterion, and buyers should assess whether vendors offer digital prescription integration.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a cautious but targeted expansion strategy in seed treatment, with the strongest opportunities in biological formulations and precision-application technologies rather than traditional chemical volume growth. The 4.23% total-market CAGR masks a much faster 12.0% CAGR in biologicals, and the near-cancellation of the strongest driver and restraint signals that substitution—not incremental growth—will define competitive outcomes through 2031. Our analysis suggests that the total market will grow at a moderate pace precisely because the biological sub-segment is cannibalizing chemical share.
The strongest counter-argument is that biological products face their own scale constraints: shelf-life limitations, inconsistent field efficacy across soil types, and higher per-unit costs could cap adoption at premium niches, leaving chemical treatments dominant in volume terms. However, regulatory timelines in Europe and North America make this counter-argument a speed-of-adoption question rather than a direction-of-travel question. The regulatory tailwind is structural, not cyclical.
Actionable Strategy:
Vendors should prioritize partnerships with microbial genomics and formulation-chemistry specialists to build compliant biological portfolios before 2028, when EU polymer restrictions fully bite.
Operators should audit their seed-treatment supply chains for neonicotinoid exposure and develop substitution roadmaps segmented by crop and geography.
Investors should focus on companies with proprietary coating chemistries and digital prescription integration, as these capabilities command premium pricing independent of active-ingredient commoditization.
What would change our conclusion: A reversal or delay in EU neonicotinoid restrictions, or a breakthrough in low-cost microbial shelf-life stabilization, would shift the balance back toward chemical incumbents and slow biological substitution. Conversely, faster-than-expected approval of multi-strain biological consortia could accelerate the biological CAGR beyond 12% and compress the total market's chemical base more rapidly than forecast.
Seed Treatment Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Seed Treatment Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.23% from 2020-2034
Segmentation
By Function
Fungicide
Insecticide
Nematicide
By Crop Type
Grains and Cereals
Pulses and Oilseeds
Commercial Crops
Fruits and Vegetables
Turf and Ornamental
By Formulation
Chemical
Biological
Polymer-Enhanced
By Application
Seed Coating
Seed Dressing
Seed Pelleting
By Geography
South America
Brazil
Argentina
Chile
Colombia
North America
United States
Canada
Mexico
Europe
Germany
France
UK
Italy
Spain
Netherlands
Asia-Pacific
China
India
Japan
Australia
Southeast Asia
Middle East & Africa
South Africa
Saudi Arabia
UAE
Egypt
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Function
5.1.1. Fungicide
5.1.2. Insecticide
5.1.3. Nematicide
5.2. Market Analysis, Insights and Forecast - by Crop Type
5.2.1. Grains and Cereals
5.2.2. Pulses and Oilseeds
5.2.3. Commercial Crops
5.2.4. Fruits and Vegetables
5.2.5. Turf and Ornamental
5.3. Market Analysis, Insights and Forecast - by Formulation
5.3.1. Chemical
5.3.2. Biological
5.3.3. Polymer-Enhanced
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Seed Coating
5.4.2. Seed Dressing
5.4.3. Seed Pelleting
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. South America
5.5.2. North America
5.5.3. Europe
5.5.4. Asia-Pacific
5.5.5. Middle East & Africa
6. South America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Function
6.1.1. Fungicide
6.1.2. Insecticide
6.1.3. Nematicide
6.2. Market Analysis, Insights and Forecast - by Crop Type
6.2.1. Grains and Cereals
6.2.2. Pulses and Oilseeds
6.2.3. Commercial Crops
6.2.4. Fruits and Vegetables
6.2.5. Turf and Ornamental
6.3. Market Analysis, Insights and Forecast - by Formulation
6.3.1. Chemical
6.3.2. Biological
6.3.3. Polymer-Enhanced
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Seed Coating
6.4.2. Seed Dressing
6.4.3. Seed Pelleting
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Function
7.1.1. Fungicide
7.1.2. Insecticide
7.1.3. Nematicide
7.2. Market Analysis, Insights and Forecast - by Crop Type
7.2.1. Grains and Cereals
7.2.2. Pulses and Oilseeds
7.2.3. Commercial Crops
7.2.4. Fruits and Vegetables
7.2.5. Turf and Ornamental
7.3. Market Analysis, Insights and Forecast - by Formulation
7.3.1. Chemical
7.3.2. Biological
7.3.3. Polymer-Enhanced
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Seed Coating
7.4.2. Seed Dressing
7.4.3. Seed Pelleting
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Function
8.1.1. Fungicide
8.1.2. Insecticide
8.1.3. Nematicide
8.2. Market Analysis, Insights and Forecast - by Crop Type
8.2.1. Grains and Cereals
8.2.2. Pulses and Oilseeds
8.2.3. Commercial Crops
8.2.4. Fruits and Vegetables
8.2.5. Turf and Ornamental
8.3. Market Analysis, Insights and Forecast - by Formulation
8.3.1. Chemical
8.3.2. Biological
8.3.3. Polymer-Enhanced
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Seed Coating
8.4.2. Seed Dressing
8.4.3. Seed Pelleting
9. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Function
9.1.1. Fungicide
9.1.2. Insecticide
9.1.3. Nematicide
9.2. Market Analysis, Insights and Forecast - by Crop Type
9.2.1. Grains and Cereals
9.2.2. Pulses and Oilseeds
9.2.3. Commercial Crops
9.2.4. Fruits and Vegetables
9.2.5. Turf and Ornamental
9.3. Market Analysis, Insights and Forecast - by Formulation
9.3.1. Chemical
9.3.2. Biological
9.3.3. Polymer-Enhanced
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Seed Coating
9.4.2. Seed Dressing
9.4.3. Seed Pelleting
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Function
10.1.1. Fungicide
10.1.2. Insecticide
10.1.3. Nematicide
10.2. Market Analysis, Insights and Forecast - by Crop Type
10.2.1. Grains and Cereals
10.2.2. Pulses and Oilseeds
10.2.3. Commercial Crops
10.2.4. Fruits and Vegetables
10.2.5. Turf and Ornamental
10.3. Market Analysis, Insights and Forecast - by Formulation
10.3.1. Chemical
10.3.2. Biological
10.3.3. Polymer-Enhanced
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Seed Coating
10.4.2. Seed Dressing
10.4.3. Seed Pelleting
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Seed Treatment Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Seed Treatment Market Volume Breakdown (Metric Tons, %) by Region 2026 & 2034
Figure 3: South America Seed Treatment Market Revenue (Billion), by Function 2026 & 2034
Figure 4: South America Seed Treatment Market Volume (Metric Tons), by Function 2026 & 2034
Figure 5: South America Seed Treatment Market Revenue Share (%), by Function 2026 & 2034
Figure 6: South America Seed Treatment Market Volume Share (%), by Function 2026 & 2034
Figure 7: South America Seed Treatment Market Revenue (Billion), by Crop Type 2026 & 2034
Figure 8: South America Seed Treatment Market Volume (Metric Tons), by Crop Type 2026 & 2034
Figure 9: South America Seed Treatment Market Revenue Share (%), by Crop Type 2026 & 2034
Figure 10: South America Seed Treatment Market Volume Share (%), by Crop Type 2026 & 2034
Figure 11: South America Seed Treatment Market Revenue (Billion), by Formulation 2026 & 2034
Figure 12: South America Seed Treatment Market Volume (Metric Tons), by Formulation 2026 & 2034
Figure 13: South America Seed Treatment Market Revenue Share (%), by Formulation 2026 & 2034
Figure 14: South America Seed Treatment Market Volume Share (%), by Formulation 2026 & 2034
Figure 15: South America Seed Treatment Market Revenue (Billion), by Application 2026 & 2034
Figure 16: South America Seed Treatment Market Volume (Metric Tons), by Application 2026 & 2034
List of Tables
Table 1: Seed Treatment Market Revenue Billion Forecast, by Function 2020 & 2034
Table 2: Seed Treatment Market Volume Metric Tons Forecast, by Function 2020 & 2034
Table 3: Seed Treatment Market Revenue Billion Forecast, by Crop Type 2020 & 2034
Table 4: Seed Treatment Market Volume Metric Tons Forecast, by Crop Type 2020 & 2034
Table 9: Seed Treatment Market Revenue Billion Forecast, by Region 2020 & 2034
Table 10: Seed Treatment Market Volume Metric Tons Forecast, by Region 2020 & 2034
Table 11: South America Seed Treatment Market Revenue Billion Forecast, by Function 2020 & 2034
Table 12: South America Seed Treatment Market Volume Metric Tons Forecast, by Function 2020 & 2034
Table 13: South America Seed Treatment Market Revenue Billion Forecast, by Crop Type 2020 & 2034
Table 14: South America Seed Treatment Market Volume Metric Tons Forecast, by Crop Type 2020 & 2034
Table 15: South America Seed Treatment Market Revenue Billion Forecast, by Formulation 2020 & 2034
Table 16: South America Seed Treatment Market Volume Metric Tons Forecast, by Formulation 2020 & 2034
South America Seed Treatment Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the seed treatment market?
The global seed treatment market is valued at USD 9.90 billion in 2026, with forecasts reaching USD 12.18 billion by 2031 at a 4.23% CAGR. South America leads regional share at 44.10%, while North America is the fastest-growing region.
2. What is driving growth in the seed treatment market?
Biological R&D partnerships, precision-agriculture micro-dosing, polymer encapsulation for reduced dust-off, and regulatory incentives for low-residue coatings are the primary drivers. GMO and hybrid seed adoption adds +0.9% CAGR, offset by neonicotinoid restrictions at -0.9%.
3. Which region dominates the seed treatment market?
South America captured 44.10% of the global seed treatment market share in 2025, driven by intensive soybean and corn acreage in Brazil and Argentina. North America is the fastest-growing region at 4.66% CAGR, followed by Asia-Pacific.
4. Who are the leading companies in the seed treatment market?
BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, and Syngenta Group are the major players. The market is moderately concentrated, with the top five suppliers accounting for less than 50% of global revenue.
5. What are the key segments of the seed treatment market?
By function, the market is segmented into fungicides, insecticides, and nematicides, with insecticides holding 71.35% share in 2025. By crop type, grains and cereals lead at 41.75%, followed by pulses and oilseeds, commercial crops, and fruits and vegetables.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the seed treatment value chain. We engaged VP-level sourcing executives, heads of R&D, technical directors, and commercial operations leads at raw material suppliers, specialized formulators, contract coating providers, and global distributors. This primary fieldwork captured granular data on treatment rates, formulation costs, and adoption barriers across 35+ countries.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
40%
Procurement & Sourcing Directors
35%
Regulatory & Quality Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Chemical Producers
45%
Formulators & Coating Providers
35%
Distributors & Seed Companies
20%
Secondary Benchmarking & Public Trade Validation
We triangulate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from the International Seed Federation and ISO 14001 frameworks. This validation ensures our estimates reflect actual trade flows and commercial activity rather than survey-based extrapolations.
Demand Modeling & Market Sizing Triangulation
We deploy simultaneous top-down and bottom-up modeling. Top-down, we allocate macroeconomic and agricultural segment spending across seed treatment categories. Bottom-up, we model manufacturer capacity, product pricing, and end-use consumption by crop and geography. The convergence of these two approaches produces our base-year market size and forecast trajectory.
 Seed Treatment Market