Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Vertical Farming Lighting Market: 2026 Global Outlook
Vertical Farming Lighting Market
Vertical Farming Lighting Market: 2026 Global Outlook
Vertical Farming Lighting Market by Component (Hardware, Software, Services), by Lighting Type (LED Grow Lights, HID Lights, Fluorescent Lights, Others), by Farm Type (Building-based Vertical Farms, Container-based Vertical Farms), by Installation Type (New Installations, Retrofit Installations), by Crop Type (Fruits & Vegetables, Flowers & Ornamentals, Herbs & Microgreens, Nursery Crops, Others), by End-use (Commercial Growers, Research Institutions, Retail & Small-Scale Growers, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, India, Japan, South Korea, Australia), by Latin America (Brazil), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 244
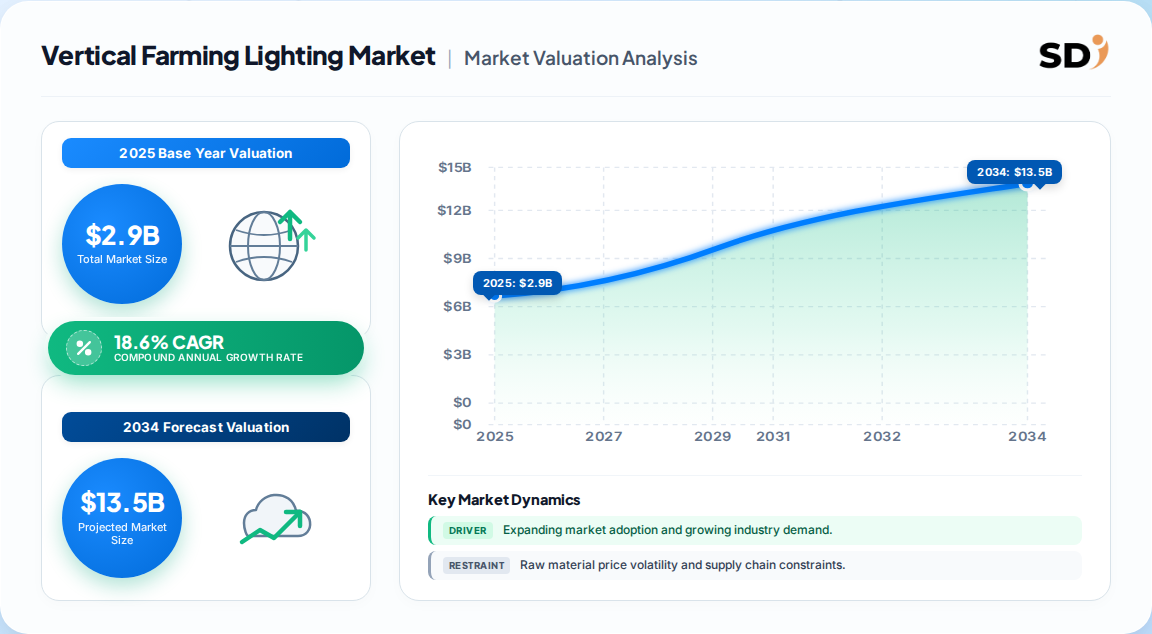
USD 2.9 billion was the global vertical farming lighting market size in 2025, with a 2026 estimate of USD 3.4 billion.
The market is projected to reach USD 11.2 billion by 2033, expanding at an 18.6% CAGR (2026–2033).
Hardware accounted for 68% of component revenue in 2025, with LED grow lights leading the lighting-type segment.
North America held the largest regional share at 32% in 2025; Asia Pacific is the fastest-growing region.
Building-based vertical farms, new installations, fruits & vegetables, and commercial growers led their respective segments.
Leading vendors include Signify, Fluence, Priva, Ridder Group, and Munters, though top-five concentration was only 6% in the broader vertical farming market.
Why this matters for decision-makers: Lighting vendors must pivot from hardware-only sales to spectrum-tunable, IoT-integrated service models to avoid margin compression as LED commoditization accelerates.
Vertical Farming Lighting Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
2.900 B
2025
3.400 B
2026
4.100 B
2027
4.800 B
2028
5.700 B
2029
6.800 B
2030
8.000 B
2031
Vertical Farming Lighting Market Size (In Billion)
Year
Market Size
2025
2.900 B
2026
3.400 B
2027
4.100 B
2028
4.800 B
2029
5.700 B
2030
6.800 B
2031
8.000 B
What is the Vertical Farming Lighting Market?
The vertical farming lighting market covers hardware, software, and services that deliver artificial light—primarily LED grow lights—to stacked indoor cultivation systems. These systems supply precise spectrum, intensity, and photoperiod control for crops grown without natural sunlight, enabling year-round, location-independent food production in controlled-environment agriculture.
Scope: what this report covers and excludes
This analysis covers the global vertical farming lighting market across components (hardware, software, services), lighting types, farm types, installation types, crop types, end-uses, and all major regions. It addresses commercial, research, and retail-scale controlled-environment operations. This analysis does not cover general greenhouse lighting, conventional field agriculture equipment, HVAC or climate-control subsystems, or broader vertical farming construction and automation markets except where directly relevant to lighting demand.
How big is the market for Vertical Farming Lighting Market?
The most defensible base figure is USD 2.9 billion for 2025, anchored to a consistent 18.6% CAGR trajectory that yields USD 11.2 billion by 2033. A competing broader vertical farming estimate (USD 7.4 billion in 2025, 14.5% CAGR to 2035) reflects all farm infrastructure—not lighting alone—so the two are not directly comparable.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 2.9 Billion
2025
2033
18.6%
Lighting hardware, software, services only
One published estimate
USD 7.4 Billion
2025
2035
14.5%
Full vertical farming infrastructure (lighting is a subset)
A competing analysis
USD 3.4 Billion
2026
2033
18.6%
Lighting-only, 2026 estimate
One published estimate
Our analysis suggests the 18.6% lighting-only CAGR is more defensible for buyer planning because it isolates the revenue pool vendors actually compete for. The broader 14.5% figure dilutes lighting demand with HVAC, automation, and construction spend, making it unsuitable for equipment procurement or vendor valuation.
How is the market segmented?
The market segments along six non-geographic axes: component, lighting type, farm type, installation type, crop type, and end-use. LED grow lights dominate lighting type, while hardware leads component revenue at 68%, reflecting the capital-intensive nature of fixture deployment.
Parent Segment
Children
Component
Hardware, Software, Services
Lighting Type
LED Grow Lights, HID Lights, Fluorescent Lights, Others
Commercial Growers, Research Institutions, Retail & Small-Scale Growers, Others
Which region leads in Vertical Farming Lighting Market?
North America led with 32% revenue share in 2025, driven by mature controlled-environment agriculture investment and strong government support. Asia Pacific is the fastest-growing region, propelled by urbanization, food-security policy, and rapid vertical farm construction in China, Japan, and South Korea.
This divergence implies that vendors should treat North America as a margin-preservation market and Asia Pacific as a volume-growth market. The two require different go-to-market models: service-led in mature markets, price-competitive hardware in fast-scaling ones.
What is driving growth — and what is holding it back?
Government support for controlled-environment agriculture and the shift toward energy-efficient LED lighting are the primary growth engines, while power-infrastructure dependence and high capital costs constrain adoption. The balance favors growth in markets where policy incentives offset capital intensity.
Factor
Direction
Evidence Strength
Mechanism
Government CEA support
Driver
High
Subsidies and grants fund lighting deployment
LED efficiency gains
Driver
High
Lower operating cost per photon delivered
IoT/AI smart lighting
Driver
Medium
Up to 25% operational efficiency improvement
Power infrastructure dependence
Restraint
High
Outages disrupt growth cycles and yields
High initial capital investment
Restraint
High
Delays project underwriting and build decisions
Renewable energy integration
Opportunity
Medium
Reduces operating-cost exposure long term
Our analysis suggests the driver-restraint balance is asymmetric by geography: policy support in Asia Pacific and the Middle East offsets capital constraints, while European operators face persistent energy-cost pressure that only renewable integration can relieve.
Who are the leading vendors?
The competitive landscape is fragmented, with the top five players—Signify, Fluence, Priva, Ridder Group, and Munters—holding only about 6% combined share in the broader vertical farming market. Differentiation rests on spectral tunability, efficacy (μmol/J), and integration with climate-control ecosystems.
Company
Primary Focus
Notable Strength
Signify
LED horticultural lighting
Brand scale and spectral research depth
Fluence
LED grow lights
High-efficacy fixtures for commercial farms
Priva
Climate & lighting control
Integrated automation platforms
Ridder Group
Greenhouse & indoor systems
Drive and control integration
Munters
Climate control
HVAC-lighting system synergy
This fragmentation implies that moats are built through software and service lock-in, not hardware alone. Vendors that bundle lighting control with climate and irrigation data capture disproportionate retention.
What do buyers and operators need to know?
Buyers should prioritize photon efficacy, spectral tunability, and warranty terms over headline fixture price, because lighting represents the dominant operating cost in vertical farms. Procurement risk concentrates in power reliability—operators in unstable-grid regions must budget for backup generation or renewable integration. Switching costs are moderate at the fixture level but high once lighting is integrated into a facility's control software, making interoperability and open protocols critical selection criteria. Regulatory compliance varies by jurisdiction, particularly around energy-efficiency standards and agricultural subsidies tied to specific technology classes. Multi-layer installations demand uniform coverage across stacked tiers, so fixture form factor and thermal management deserve equal weight to spectrum performance.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a service-led, software-differentiated strategy over commodity hardware competition. The 18.6% CAGR is real, but it will accrue disproportionately to vendors who convert lighting from a capex line item into an operating-efficiency subscription. The strongest counter-argument is that hardware prices are falling fast enough to commoditize the category before software monetization scales—a risk that is genuine in Asia Pacific's price-sensitive new-install segment.
Our analysis suggests the smart-lighting efficiency gain of up to 25% is the single most under-priced lever in the market. Operators who deploy sensor-driven spectrum control capture both yield and energy savings, yet most procurement decisions still evaluate fixtures on wattage and upfront cost alone. This gap represents the clearest vendor opportunity of the forecast period.
For vendors: Prioritize IoT-integrated, spectrum-tunable systems with open APIs to capture the retrofit and service-revenue upside.
For operators: Model total cost of ownership over seven years, not fixture price, and lock in power-reliability contingencies before build.
For investors: Favor exposure to Asia Pacific volume growth and North American service-led margins; discount pure-hardware plays.
The evidence that would change this conclusion is a step-change in LED efficacy that collapses fixture prices below service-attach thresholds, or a policy reversal in CEA subsidies across major markets.
Research Methodology
Primary Research & Industry Fieldwork
This study applied a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including LED component and semiconductor suppliers, specialized horticultural fixture producers, control-software and automation formulators, and global distributors serving controlled-environment agriculture. Decision-maker designations interviewed included VP-level sourcing executives, heads of horticultural R&D, technical directors, and commercial operations leads.
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on UN Comtrade and US ITC trade-flow data for lighting and semiconductor components, Eurostat industrial statistics, corporate 10-K and SEC filings from publicly listed lighting and automation firms, patent databases tracking LED spectrum and control innovations, and technical standards from recognized industry associations.
Demand Modeling & Market Sizing Triangulation
Top-down macroeconomic and segment-allocation modeling was run simultaneously with bottom-up manufacturer capacity, fixture pricing, and end-use consumption modeling to triangulate the base-year valuation and forecast trajectory.
1. How big is the vertical farming lighting market in 2026?
The global vertical farming lighting market is estimated at USD 3.4 billion in 2026, up from USD 2.9 billion in 2025. It is projected to reach USD 11.2 billion by 2033 at an 18.6% CAGR, driven by LED adoption and controlled-environment agriculture expansion.
2. Which region leads the vertical farming lighting market?
North America held the largest share at 32% of global revenue in 2025, supported by mature controlled-environment agriculture investment. Asia Pacific is the fastest-growing region, driven by urbanization, food-security policy, and rapid vertical farm construction.
3. What lighting type dominates vertical farming?
LED grow lights lead the lighting-type segment, benefiting from falling prices, high photon efficacy, and spectrum tunability. HID and fluorescent lights retain niche use but are being displaced as operators prioritize energy savings and precise crop-specific light recipes.
4. What is the biggest restraint on market growth?
Dependence on stable power infrastructure is the primary restraint, as artificial lighting is the sole energy source for crop growth. Outages disrupt growth cycles, and high initial capital investment further delays project underwriting, particularly in early-stage markets.
5. Who are the leading vendors in vertical farming lighting?
Leading vendors include Signify, Fluence, Priva, Ridder Group, and Munters. The top five collectively held only about 6% share of the broader vertical farming market in 2025, indicating a fragmented landscape where software and service integration drive differentiation.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applied a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including LED component and semiconductor suppliers, specialized horticultural fixture producers, control-software and automation formulators, and global distributors serving controlled-environment agriculture. Decision-maker designations interviewed included VP-level sourcing executives, heads of horticultural R&D, technical directors, and commercial operations leads.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement
35%
Heads of Horticultural R&D
30%
Technical Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
LED Component & Semiconductor Suppliers
35%
Horticultural Fixture Producers
40%
Control Software & Automation Firms
15%
Global Distributors
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on UN Comtrade and US ITC trade-flow data for lighting and semiconductor components, Eurostat industrial statistics, corporate 10-K and SEC filings from publicly listed lighting and automation firms, patent databases tracking LED spectrum and control innovations, and technical standards from recognized industry associations.
Demand Modeling & Market Sizing Triangulation
Top-down macroeconomic and segment-allocation modeling was run simultaneously with bottom-up manufacturer capacity, fixture pricing, and end-use consumption modeling to triangulate the base-year valuation and forecast trajectory.
 Vertical Farming Lighting Market