 Agricultural Testing Market
: Size, Share & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 250

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Agricultural Testing Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 7.900 B |
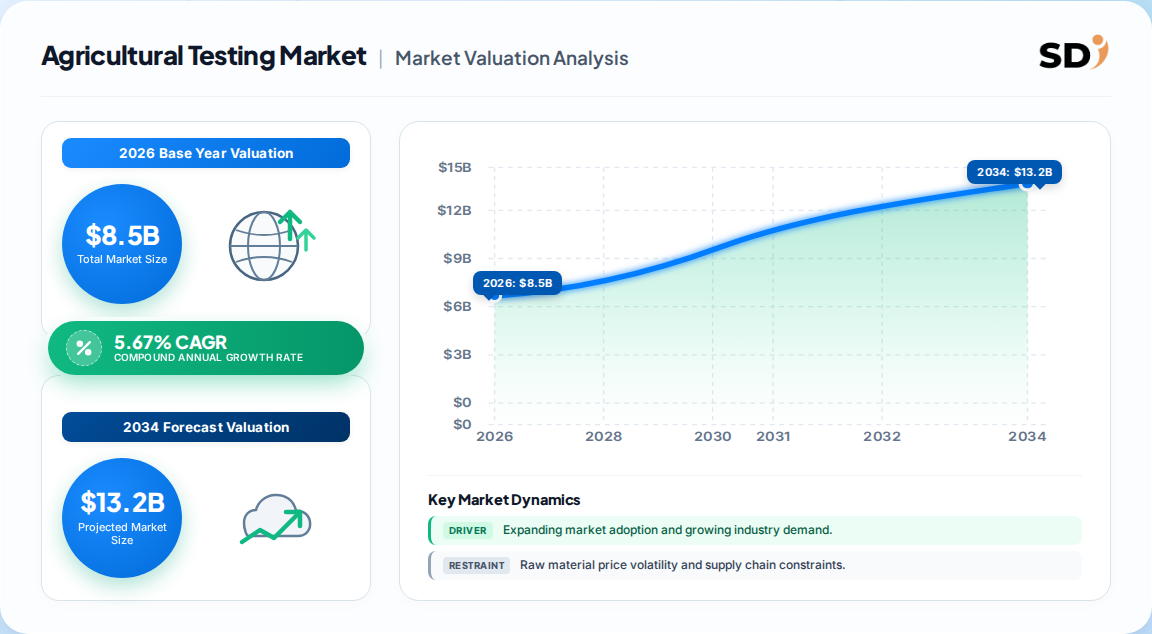
| 2026 | 8.500 B |
| 2027 | 8.980 B |
| 2028 | 9.490 B |
| 2029 | 10.03 B |
| 2030 | 10.60 B |
| 2031 | 11.20 B |

The agricultural testing market encompasses laboratory and on-site analytical services that assess soil, water, seed, plant tissue, manure, and bio-solids for nutrient content, contaminants, pathogens, and quality parameters. These services support food safety compliance, precision agriculture, organic certification, and environmental sustainability across the agricultural value chain.
This report covers agricultural testing services across soil, water, seed, bio-solids, manure, and other sample types, segmented by application (safety testing, quality assurance) and technology (conventional, rapid). It spans North America, Europe, Asia-Pacific, South America, and the Middle East & Africa. This analysis does not cover veterinary diagnostics, processed-food safety testing, pharmaceutical quality testing, or general environmental monitoring outside agricultural contexts.
Estimates vary due to differing scope definitions, base years, and segment inclusions. The table below compares published figures.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 8.5 Billion | 2026 | 2031 | 5.67% | Broad agricultural testing incl. soil, water, seed, bio-solids, manure; global | One published estimate |
| USD 6.7 Billion | 2026 | 2034 | 3.91% | Similar sample scope; staggered forecast horizon | A competing analysis |
| USD 7.73 Billion | 2025 | 2032 | 7.0% | Broader inclusion of rapid tech and precision ag applications | A third-party forecast |
| USD 6.7 Billion | 2026 | 2036 | 2.69% | Services-focused; excludes processed-food and veterinary | An alternate services benchmark |
The USD 8.5 billion (2026) figure is the most defensible for total-market sizing because it balances breadth of sample coverage with a mid-range CAGR trajectory. The higher 7% CAGR estimate likely overweights rapid-test adoption timelines, while the 2.69% services-only view understates equipment-integrated testing revenue.
The market is segmented by sample type, application, and technology.
| Parent Segment | Children |
|---|---|
| By Sample | Soil, Water, Seed, Bio-solids, Manure, Others |
| By Application | Safety Testing, Quality Assurance |
| By Technology | Conventional Testing, Rapid Testing |
Soil testing dominates as the foundational agronomic input, while rapid testing is the fastest-growing technology category. Quality assurance holds the larger application share, but safety testing is gaining momentum due to regulatory tightening.
North America leads with approximately 42% of global revenue in 2025, driven by stringent FDA and EPA regulations, high organic trade volumes, and advanced laboratory infrastructure. Asia-Pacific is the fastest-growing region at an estimated 8.8% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.42% |
| Europe | 0.24% |
| Asia-Pacific | 0.22% |
| South America | 0.07% |
| Middle East & Africa | 0.05% |
| Region | Share (2025) |
|---|---|
| North America | ~42% |
| Europe | ~24% |
| Asia-Pacific | ~22% |
| South America | ~7% |
| Middle East & Africa | ~5% |
Geography Tree:
Europe's share is reinforced by EU Regulation 2018/848 organic certification requirements and maximum residue level reductions for 47 pesticides. Asia-Pacific's growth is underpinned by China's dual-testing mandate and India's expanding seed-testing laboratory network.
Regulatory tightening, food-borne illness outbreaks, organic trade certification, and carbon-credit soil programs are the primary demand drivers, while capital intensity, skills shortages, and reagent cost volatility restrain expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Stringent food-safety regulations | Driver | High | FDA water-testing rules and EU MRL reductions create recurring testing volume |
| Food-borne illness outbreaks | Driver | High | Retailer mandates for same-day pathogen clearance drive rapid-test adoption |
| Organic trade certification | Driver | Medium | EU and US organic programs require residue testing at ppb sensitivity |
| On-site DNA/nanopore sequencing | Driver | Medium | Portable sequencers enable field diagnostics, reducing turnaround time |
| Carbon-credit soil programs | Driver | Medium | Multi-year soil health testing contracts create annuity-style revenue |
| High capital requirements | Restraint | High | Mass spectrometry upgrades demand significant lab investment |
| Skilled professional shortages | Restraint | Medium | Technician scarcity limits throughput expansion |
| Tariff-influenced reagent costs | Restraint | Medium | Input cost volatility pressures lab margins |
The balance of evidence suggests regulation-driven demand provides a stable floor even during commodity downturns, but margin expansion depends on labs' ability to transition to rapid, on-site, and digitally verified testing models.
The market is moderately concentrated, with five major networks dominating global revenue.
| Company | Headquarters | Strategic Focus |
|---|---|---|
| Eurofins Scientific SE | Luxembourg | Broadest agricultural testing portfolio; LC-MS/MS fleet |
| SGS SA | Switzerland | Global network; production-agriculture service integration |
| Intertek Group plc | UK | Compliance and certification-linked testing |
| PerkinElmer, Inc. | USA | Instrumentation and analytical solutions |
| Institut Mérieux (Mérieux NutriSciences) | France | Food safety and quality testing |
These players compete on accreditation breadth (ISO/IEC 17025), turnaround time, geographic coverage, and digital reporting capabilities. Smaller laboratories are increasingly delegating complex analyses to these networks, reinforcing consolidation. Differentiation is shifting toward bundled sampling-logistics-analytics offerings that embed switching costs.
Buyers should prioritize laboratories with ISO/IEC 17025 accreditation, demonstrated method equivalency, and validated rapid-testing capabilities. Procurement risks include reagent supply chain disruptions, turnaround time variability, and inconsistent reporting formats across regions.
Switching costs are rising as labs integrate blockchain-verified certificates and multi-year soil testing contracts. Regulatory compliance is non-negotiable: FDA, EU MRL, and China's dual-testing mandates require documented method validation. Operators should evaluate vendors on sample collection logistics, data interpretability, and ability to scale with certification requirements. The rise of on-site DNA sequencing and portable PCR kits means buyers must assess whether laboratory-based or field-deployable testing better fits their decision timelines.
The balance of evidence favors a consolidation-driven, technology-enabled growth trajectory for the agricultural testing market. The 5.67% CAGR consensus is credible, but the real story is the divergence between conventional and rapid testing growth rates—9.2% versus an estimated 3-4% for conventional methods. This implies that laboratories stuck in conventional workflows face structural margin erosion.
The strongest counter-argument is that rapid-test adoption remains uneven due to cold-chain and power-supply constraints in emerging markets, potentially slowing the 9.2% CAGR trajectory. However, regulatory mandates in developed markets and retailer-driven pathogen clearance requirements create a demand floor that outweighs this risk.
Actionable Strategy:
The evidence that would change our conclusion: a sustained reversal in FDA or EU regulatory tightening, or a dramatic drop in rapid-test reagent costs that commoditizes the technology advantage.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.67% from 2020-2034 |
| Segmentation |
|
The market is growing at approximately 5.67% CAGR from 2026 to 2031, with rapid testing technologies expanding faster at 9.2% CAGR.
The market is projected to reach USD 11.2 billion by 2031, up from USD 8.5 billion in 2026.
North America leads with approximately 42% of global revenue, while Asia-Pacific is the fastest-growing region at an estimated 8.8% CAGR.
Eurofins Scientific, SGS, Intertek, PerkinElmer, and Institut Mérieux (Mérieux NutriSciences) are the leading vendors, collectively holding significant market share.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, anchoring market sizing and forecasts in direct industry engagement. We conducted in-depth interviews with stakeholders across the agricultural testing value chain, including laboratory network operators, instrument and reagent suppliers, contract sampling service providers, accreditation bodies, and agricultural input companies. Decision-maker designations interviewed included VP-level Sourcing Leads, Heads of Laboratory Operations, Technical Directors, and Commercial Operations Managers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Laboratory Operations Directors | 35% |
| Quality & Regulatory Affairs Leads | 30% |
| Procurement & Sourcing Managers | 20% |
| Commercial & Business Development Heads | 15% |
| Company Type | Representation (%) |
|---|---|
| Laboratory Networks & Testing Service Providers | 40% |
| Instrumentation & Reagent Suppliers | 30% |
| Contract Sampling & Logistics Providers | 20% |
| Accreditation & Certification Bodies | 10% |
We triangulated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. These sources validated segment shares, regional trade flows, and competitive positioning.
Our simultaneous top-down and bottom-up data triangulation approach combines macroeconomic segment allocation with manufacturer capacity, product pricing, and end-use consumption modeling. This dual methodology ensures market sizing accuracy across base-year valuation and multi-year forecasts.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |