 Autonomous Farm Equipment Market
: 2026 Size, CAGR & Outlook
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 238

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Autonomous Farm Equipment Market
Atul Bhusare
Research Associate
| Year | Market Size |
|---|---|
| 2025 | 86.54 B |
| 2026 | 91.16 B |
| 2027 | 95.66 B |
| 2028 | 100.4 B |
| 2029 | 105.2 B |
| 2030 | 113.5 B |

The autonomous farm equipment market covers self-operating or supervised robotic machinery — tractors, harvesters, sprayers, planters and agricultural UAVs — that execute field operations with reduced or removed human control. Revenue is measured at manufacturer and system level for equipment, autonomy kits, and embedded guidance, sensing and telematics software.
This analysis covers on-farm autonomous and semi-autonomous machinery: wheeled tractors, combine and forage harvesters, self-propelled sprayers, planters, weeding and monitoring robots, and agricultural UAVs across field farming, horticulture, dairy, livestock and forestry. Autonomy is defined across SAE-aligned Levels 2–5, with supervised (Level 2–3) and unattended (Level 4–5) distinguished.
This analysis does not cover conventional non-autonomous machinery, standalone precision-agronomy software without equipment integration, farm management SaaS, irrigation infrastructure, used-equipment resale, or aftermarket parts and service revenue.
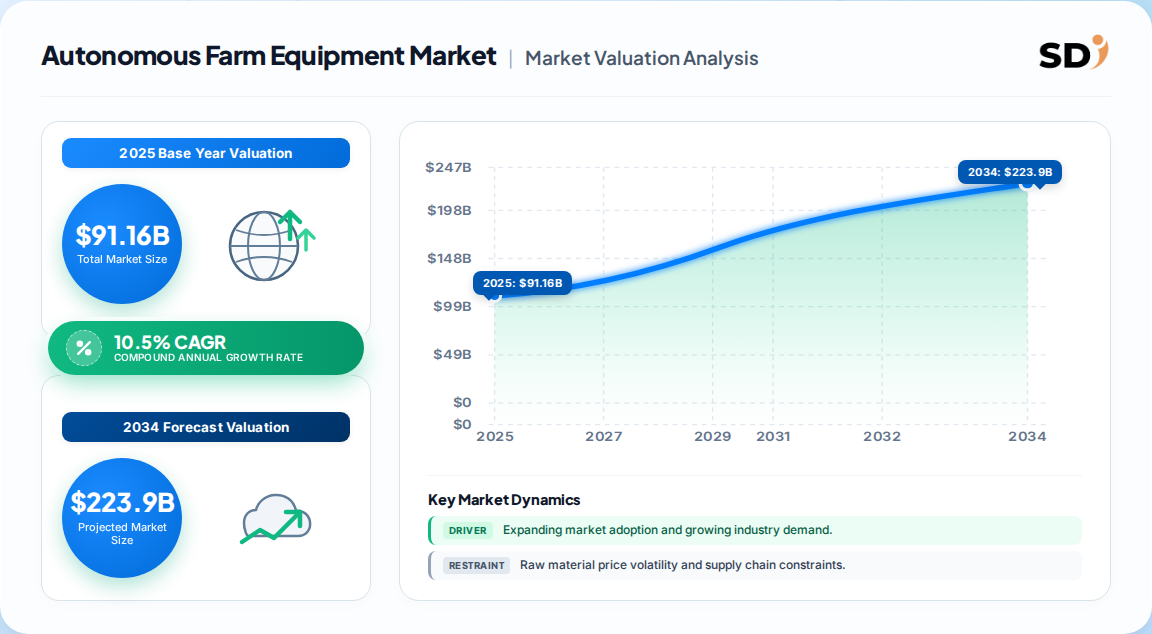
The market is most credibly sized at USD 91.2 billion for 2026, with a 2030 horizon near USD 113.5 billion. Published estimates diverge sharply — a USD 21–22 billion view and a USD 42 billion view exist — because firms define 'autonomous' against fundamentally different baselines.
| Estimate (2026) | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 91.2 Billion | 2025 | 2030 | 5.3–5.6% | Broad: all autonomy-assisted machinery incl. guidance and retrofits | One published estimate |
| USD 42.2 Billion | 2025 | 2035 | 12.2% | Narrow: purpose-built autonomy platforms and UAVs | Another published benchmark |
| USD 22.3 Billion | 2025 | 2033 | 10.5% | Tightest: dedicated autonomous equipment only | A competing analysis |
| USD 133 Billion (by 2030) | 2025 | 2030 | ~9% | Broadest: includes 44% share of total farm machinery | One trade analysis |
The 4.3x spread between the low and high 2026 figures is almost entirely definitional. The USD 91 billion figure counts every machine shipping with auto-steering, section control or supervised autonomy, which is now standard fitment on large tractors. The USD 22 billion figure isolates genuinely self-operating platforms.
Our analysis suggests the defensible mid-case for buyers is the narrower USD 90 billion-plus basket only when evaluating a total addressable fleet; procurement and competitive strategy should be built on the USD 40–45 billion purpose-built autonomy segment, where the 10–12% growth rate is concentrated. This divergence implies vendor revenue guidance is not directly comparable across disclosures.
Segmentation follows product, autonomy level, application and farm-size economics. Product and autonomy level are the two dimensions that most reliably predict price point and channel structure.
| Parent segment | Children |
|---|---|
| By Product | Tractors, Harvesters, UAVs, Planters, Sprayers, Weeding & Monitoring Robots |
| By Autonomy Level | Partially autonomous (supervised), Fully autonomous (unattended) |
| By Application | Field farming, Horticulture, Dairy & livestock, Forestry |
| By Farm Size | Large commercial, Mid-size, Smallholder / service-fleet |
| By Distribution | Direct OEM, Dealer network, Fleet & service operators |
Tractors reach an estimated USD 58 billion by 2030, harvesters USD 36 billion and UAVs USD 26 billion on the broad definition. Partially autonomous systems hold the majority share today because they carry no certification barrier and can be retrofitted onto existing fleets.
Asia Pacific leads on absolute revenue and growth rate, combining rapid mechanization in China, India and Southeast Asia with sovereign subsidy programmes that compress farmer access costs.
| Region | Market Share (%) |
|---|---|
| North America | 0.31% |
| Europe | 0.23% |
| Asia-Pacific | 0.33% |
| South America | 0.07% |
| Middle East & Africa | 0.06% |
The United States remains the single largest country market, forecast near USD 26 billion by 2030 on the broad definition, driven by large-acreage consolidation and farm-robotics investment. This implies that a global vendor needs dual-track commercial models: a high-ASP direct model in North America and a subsidy-assisted fleet-operator channel in Asia Pacific.
Growth is driven by structural labor scarcity and certification readiness, and restrained by capital cost and rural connectivity deficits. The net balance favors acceleration, but the pace is gated by infrastructure, not by technology.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Agricultural labor shortage | Driver | High | Extends operating hours in narrow planting/harvest windows |
| Government subsidies and smart-farm policy | Driver | High | Sovereign procurement converts into immediate fleet demand |
| BVLOS and SAE L3–4 certification progress | Driver | Medium | Reduces commercial uncertainty for institutional buyers |
| High upfront cost and TCO | Restraint | High | Only 27% of US farms use precision agriculture at all |
| Rural connectivity gaps | Restraint | Medium | Telemetry and remote supervision impaired on active farmland |
| Sensor reliability in variable field conditions | Restraint | Medium | Raises liability and insurance cost for unattended operation |
The FAO's projection that agriculture must produce 50% more food by 2050 on fixed arable land anchors the yield imperative. But low precision-agriculture penetration in advanced markets shows the cost barrier is binding well below the autonomy frontier — the addressable base is narrower than headline fleet counts suggest.
The top five vendors hold roughly 61% of revenue, with John Deere alone above 22%. Consolidation around dealer networks, autonomy stacks and agronomic data platforms defines the competitive moat.
| Vendor | Position | Differentiation |
|---|---|---|
| John Deere (Deere & Company) | Leader, ~22% share | Fully integrated autonomy stack, dealer density, agronomic platform |
| CNH Industrial | Top-tier challenger | Multi-brand portfolio, Raven autonomy acquisition, broad geography |
| AGCO Corporation | Top-tier challenger | Precision-ag portfolio, Fendt autonomy, retrofit pathway |
| Kubota Corporation | Top-tier challenger | Asia Pacific strength, compact and specialty segments |
| CLAAS KGaA mbH | Top-tier challenger | Harvester leadership and European channel depth |
Our analysis suggests the moat is shifting from iron to software: hardware price deflation will erode machine margin, and vendors monetizing supervision software, over-the-air updates and fleet orchestration will defend gross margin. Retrofit autonomy kits are the most credible attack vector against incumbent share.
Buyers should evaluate autonomy on total cost per hectare of completed fieldwork, not sticker price. The decisive variables are supervised-to-unattended labor ratio, uptime under connectivity loss, and the liability allocation written into certification terms.
Procurement risk concentrates in three areas. First, certification status: an SAE Level 3 system bought today may be stranded if Level 4 approvals arrive before its depreciation cycle ends. Second, data lock-in: telematics and agronomic records tied to one OEM platform create high switching costs. Third, connectivity dependency: machines relying on continuous remote supervision underperform where rural broadband lags urban coverage by wide margins.
Operators should demand contractual fallback modes — degraded but safe autonomous operation — and verify parts and service coverage before committing to fleet-scale procurement.
The balance of evidence favors a definition-normalized mid-case of roughly USD 91 billion in 2026 growing at near 10.5% to 2030, with genuine autonomy concentrated in a USD 40–45 billion purpose-built core. The strongest counter-argument is the high-CAGR, narrow-definition school, which contends the total is far smaller but compounds twice as fast; that view is defensible if fully unattended certification stalls and only supervised systems ship.
Our judgment: the growth rate is more reliable than the headline size. Every estimate agrees on double-digit or high-single-digit compounding, on Asia Pacific leadership, on tractor dominance, and on oligopoly concentration. Divergence is a measurement artifact, not a demand disagreement — which is precisely why buyers need the underlying segment model rather than the headline.
The real gating factor is second-order. Certification timing determines whether institutional buyers enter; connectivity determines whether unattended operation is insurable; and sensor-field reliability determines whether the labor savings promised actually materialize. Vendors that treat autonomy as a software-and-certification race, rather than an iron-selling race, will outperform.
Actionable strategy:
Evidence that would change our conclusion: material easing of farm labor supply, a sustained commodity price decline compressing farm capex, or delayed Level 3–4 certification past 2030 would push us toward the low-end, high-CAGR scenario.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.5% from 2020-2034 |
| Segmentation |
|
The market is estimated at USD 91.2 billion in 2026 on a broad definition that includes all autonomy-assisted machinery. Narrower definitions isolating purpose-built autonomous platforms place the figure nearer USD 22–42 billion, reflecting scope rather than demand disagreement.
Consensus forecasts cluster between 5.3% and 12.2%, with a defensible mid-case near 10.5% through 2030. The spread reflects definitional differences, not demand uncertainty — every published estimate confirms double-digit or high-single-digit compounding.
Asia Pacific leads on both revenue and growth rate, driven by rapid mechanization in China, India and Southeast Asia plus sovereign subsidy programmes. The United States remains the largest single country market, forecast near USD 26 billion by 2030.
John Deere leads with over 22% share, followed by CNH Industrial, AGCO, Kubota and CLAAS. Together the top five control roughly 61% of global revenue, sustaining a concentrated oligopoly with strong dealer and software moats.
High upfront cost and total cost of ownership remain the primary barriers, with only 27% of US farms using any precision agriculture. Rural connectivity deficits also impair remote supervision and safety monitoring across active farmland.
Partially autonomous, supervised systems dominate commercial volume today. Fully unattended Level 4–5 platforms are commercially limited, pending clearer SAE-aligned certification pathways in the EU and United States, expected to mature progressively toward 2030.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with OEM platform manufacturers, autonomy-kit and sensor suppliers, implement and attachment producers, and regional dealer and fleet-operator groups. Within these organisations we engaged VP-level and director-level decision-makers including Heads of Product Strategy, Chief Autonomy Engineers, Commercial Operations Leads, and Procurement and Sourcing Directors.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & Autonomy Strategy Leads | 40% |
| Procurement & Sourcing Directors | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| OEM Platform Manufacturers | 40% |
| Autonomy & Sensor Suppliers | 30% |
| Dealers & Fleet Operators | 30% |
Secondary validation draws on UN Comtrade and Eurostat trade flows for agricultural machinery, US ITC tariff and shipment data, corporate annual filings and investor presentations (10-K and equivalent), patent filings covering autonomous navigation and machine vision, and technical standards published by recognised industry bodies. No third-party market-research publisher data is used in modeling.
Market sizing triangulates a top-down allocation from macroeconomic agricultural capex and mechanization intensity against a bottom-up model built from manufacturer capacity, unit pricing and end-use consumption by farm size. The two views are reconciled by autonomy level and product class to isolate genuine autonomous value from guidance and retrofit fitment.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
