 Watermelon Seeds Market
 Size, Share & 2030 Outlook
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 231

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Watermelon Seeds Market
Atul Bhusare
Research Associate
| Year | Market Size |
|---|---|
| 2024 | 800.0 M |
| 2025 | 860.0 M |
| 2026 | 930.0 M |
| 2027 | 1.000 B |
| 2028 | 1.080 B |
| 2029 | 1.160 B |
| 2030 | 1.250 B |

The watermelon seeds market covers commercial production, treatment and distribution of Citrullus lanatus seed — open-pollinated and F1 hybrid, diploid and triploid, untreated and film-coated — sold to open-field and protected-cultivation growers, plus edible-seed processors. It spans proprietary breeding, seed multiplication, phytosanitary treatment and global trade under HS code 120770.
This analysis covers commercial planting seed (open-pollinated and F1 hybrid, diploid and triploid, untreated and pelleted/film-coated) sold to open-field and protected-cultivation growers globally, including breeding, multiplication, treatment and distribution. This analysis does not cover edible/roasted watermelon seed for human consumption, watermelon seed oil, fresh watermelon fruit trade, or generic vegetable-seed markets outside Citrullus lanatus.
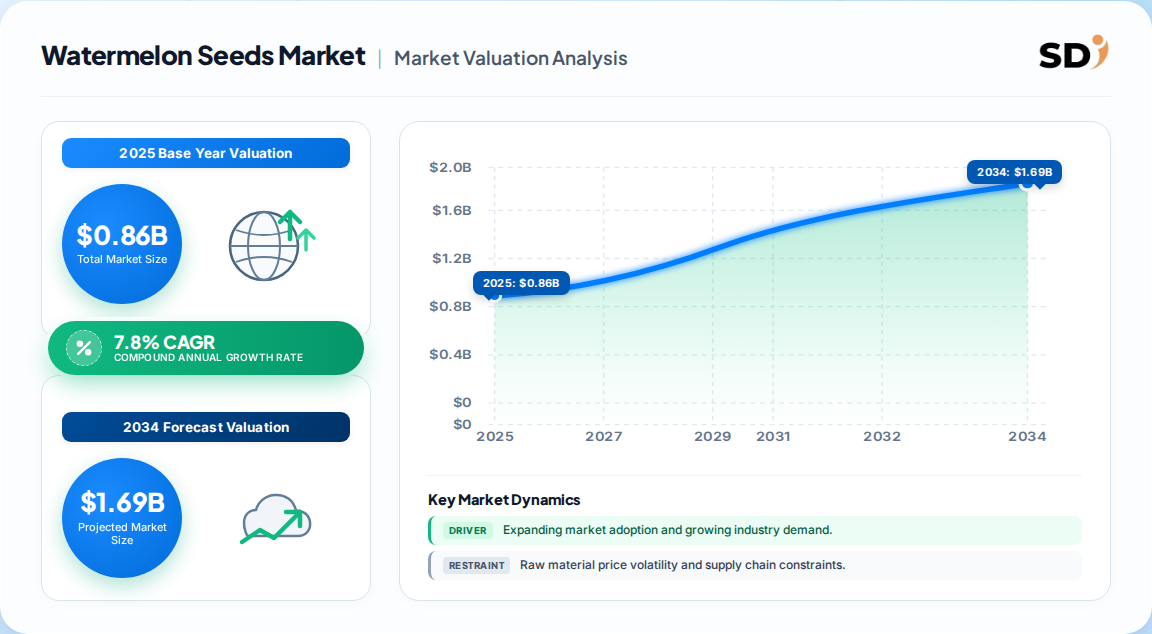
The most defensible reading is USD 0.86 billion in 2025 rising to USD 1.25 billion by 2030 at 7.8% CAGR — a planting-seed definition. Divergent estimates reflect a definitional split between planting seed and edible seed rather than genuine disagreement on growth.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 0.86 Bn | 2025 | 2030 (USD 1.25 Bn) | 7.8% | Commercial planting seed, treated and untreated | One published industry estimate |
| USD 711.0 Mn | 2024 | 2030 (USD 995.4 Mn) | 5.8% | Edible raw/roasted/dried seed, retail-led | A competing analysis |
| USD 768.4 Mn | 2025 | 2035 (USD 1,454.1 Mn) | 6.6% | Edible seed plus powder and oil forms | A third published estimate |
| USD 1.59 Bn | 2022 | 2030 (USD 3.08 Bn) | 7.17% | Broad watermelon seed, food and nutraceutical | A broader-scope study |
Our analysis suggests the planting-seed figure best reflects the genetics-and-treatment value chain that drives grower economics; edible-seed framing captures consumer snacking demand, which is a separate buyer set. Buyers should confirm which definition underpins any forecast before benchmarking procurement budgets.
Segmentation runs along seed genetics, treatment status, fruit-size class and end-user system — the axes that most directly determine price points and grower willingness to pay.
| Parent | Children |
|---|---|
| By Seed Type | Open-pollinated; Hybrid diploid; Hybrid triploid (seedless) |
| By Treatment | Untreated; Film-coated / pelleted |
| By Fruit-Size Class | Mini (<3 kg); Standard; Large |
| By End User | Open-field cultivation; Protected cultivation |
| By Distribution | Direct to grower; Indirect / dealer network |
Hybrid diploid dominates volume at ~58% share, yet triploid seed commands a 15–25% retail premium and is growing at 12.1% CAGR. Untreated seed still holds ~56% of value, but pelleted and film-coated seed is expanding at 10.2% CAGR as phytosanitary rules tighten — a shift that favors integrated breeders with in-house treatment lines.
Asia-Pacific leads with approximately 41% of global watermelon seed value in 2024, supported by large open-field acreage in China, India and Southeast Asia. Africa is the fastest-growing region at ~10.5% CAGR, while North America anchors premium seedless demand.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.41% |
| North America | 0.24% |
| Europe | 0.18% |
| South America | 0.09% |
| Middle East & Africa | 0.08% |
| Parent region | Sub-markets tracked |
|---|---|
| Asia-Pacific | China, India, Japan, South Korea, Southeast Asia |
| North America | USA, Canada, Mexico |
| Europe | Germany, France, Italy, Spain, Netherlands, UK |
| South America | Brazil, Argentina, Peru, Chile |
| Middle East & Africa | Egypt, South Africa, Turkey, Saudi Arabia, UAE |
Trade data reinforce the picture: in 2024 the largest exporters by value were the Netherlands (USD 81.8M), the United States (USD 65.8M) and Thailand (USD 25.6M), while India was the largest importer at USD 166.3M — a sign that Asia-Pacific demand is outpacing domestic multiplication capacity. This divergence implies continued upward pressure on imported seed pricing and a structural opening for regional multiplication partnerships.
The primary driver is the shift from farm-saved open-pollinated seed to F1 hybrids offering 20–30% yield gains and uniform maturity. Restraints center on hybrid seed cost — four to five times farm-saved seed — and price-sensitive smallholder economics.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Open-pollinated to F1 hybrid transition | Driver | Strong | +2.1% to CAGR; 20–30% yield uplift, uniform harvest |
| Triploid (seedless) adoption in premium retail | Driver | Strong | +1.8% to CAGR; 15–25% retail premium, 80%+ of US output |
| Climate-resilient, drought-tolerant germplasm | Driver | Moderate | +1.4% to CAGR; 30% water savings with grafting/fertigation |
| Marker-assisted and genomic selection | Driver | Moderate | +1.2% to CAGR; breeding cycles cut 30–40% |
| Hybrid seed price premium | Restraint | Strong | 4–5x farm-saved seed cost limits smallholder adoption |
| Availability of substitute seeds with similar nutrition | Restraint | Moderate | Caps edible-seed substitution and pricing power |
| Stricter phytosanitary and traceability rules | Restraint / driver | Moderate | Raises compliance cost but boosts treated-seed demand |
| Pollenizer row requirements for triploid seed | Restraint | Moderate | 20–33% of field to pollenizer rows raises grower complexity |
On balance, the drivers outweigh restraints, but the balance is uneven: yield economics favor hybrids strongly in commercial operations, while smallholder cost sensitivity keeps open-pollinated seed viable across parts of Africa and South Asia for longer than headline CAGRs imply.
The competitive field is moderately concentrated, with the top five vendors holding roughly half of global revenue. Differentiation rests on proprietary genetics, triploid parent lines and treatment capability rather than on price alone.
| Company | Primary strength | Strategic moat |
|---|---|---|
| Syngenta Group | Broad hybrid vegetable portfolio | Global germplasm library and distribution scale |
| Bayer AG | Vegetable seed R&D and traits | Genomic selection pipeline and channel reach |
| BASF SE | Seed solutions and treatment | Integrated seed-treatment and coating technology |
| UPL Limited | Hybrid seed and crop protection | Emerging-market dealer networks and bundling |
| Sakata Seed Corporation | Watermelon breeding specialization | Proprietary tetraploid lines and triploid expertise |
| East-West Seed | Tropical/Asian vegetable seed | Regional breeding for humid-tropical conditions |
Beyond the leaders, specialist breeders focused on mini watermelons or protected cultivation retain viable niches because triploid seed production is technically complex and proprietary tetraploid lines yield strong margins. Our analysis suggests the moat is shifting from brand to germplasm plus treatment IP, which raises the cost of competitive entry.
Seed selection is now a multi-criteria decision, not a price decision. Buyers should evaluate germination rate (leading triploid lines now reach 90–99% lab germination), disease resistance packages — notably Fusarium wilt races 2 and 3 and Green Mottle Mosaic Virus — and uniformity of maturity for harvest scheduling. Certification and phytosanitary documentation are non-negotiable for cross-border movement, and treated or pelleted seed increasingly reduces rejection risk at borders.
Procurement risk concentrates in supply concentration: a small number of breeders control triploid parent lines, so single-source exposure is a genuine operational hazard. Switching costs rise with pollenizer-ratio planning, because triploid adoption requires dedicating 20–33% of field area to pollenizer rows — a change that locks growers into a multi-year variety program. Regulatory compliance around traceability schemes and seed-quality certification in Africa and South Asia is tightening, favoring suppliers who can document chain of custody. Our analysis suggests buyers should secure multi-season supply agreements and validate germination and purity through independent testing before committing acreage.
The balance of evidence favors a planting-seed framing of this market, with the 7.8% CAGR figure as the planning baseline. The conflicting published estimates are largely definitional: edible-seed studies capture a consumer snacking demand curve, while planting-seed studies capture grower genetics economics. For capital allocation and procurement planning, the genetics view is the decision-relevant one — it maps to the buyers who actually purchase at scale.
The strongest counter-argument is that hybrid seed price premiums could compress faster than expected. If open-pollinated yields close the gap in low-input African and South Asian systems, or if government subsidy programs falter, the hybrid transition slows and headline CAGRs prove optimistic. Traders should also note extreme unit-price dispersion in trade data — Indian watermelon seed exports averaged USD 83.54/kg in May 2026, against multi-thousand-dollar per-kg figures in some specialty corridors — a signal that product grades and definitions vary widely and that price benchmarking must be grade-specific.
Actionable strategy:
What would change this conclusion: a sustained fall in hybrid-to-open-pollinated yield differentials below 10%, or a sharp reversal in subsidy and traceability programs across Africa and South Asia, would materially lower the growth trajectory and favor a more conservative baseline.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with proprietary breeders, commercial seed multipliers, seed-treatment and coating specialists, regional distributors and large-scale grower operations. Decision-makers interviewed include VP-level sourcing leads, heads of breeding and R&D, technical directors responsible for germination and phytosanitary compliance, and commercial operations leads managing dealer networks.
Estimates were benchmarked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) under HS code 120770, corporate annual filings and investor presentations, patent databases tracking triploid and genomic-selection IP, and technical standards published by international seed-quality and phytosanitary bodies.
Top-down macroeconomic and acreage-based allocation was run simultaneously with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Divergences between the two approaches were reconciled through segment-level elasticity assumptions and trade-flow validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |

| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.8% from 2020-2034 |
| Segmentation |
|
The commercial planting-seed market was valued at approximately USD 0.86 billion in 2025, based on estimates tracking hybrid and open-pollinated seed sales to growers. Edible-seed studies using a narrower retail definition report lower figures, so buyers should confirm the scope behind any benchmark.
The planting-seed market is forecast to grow at roughly 7.8% CAGR from 2025 to 2030, reaching about USD 1.25 billion. Growth is led by the shift to F1 hybrids, triploid seedless adoption and climate-resilient germplasm rather than acreage expansion alone.
Asia-Pacific accounts for roughly 41% of global value, supported by large open-field acreage in China, India and Southeast Asia. Africa is the fastest-growing region at about 10.5% CAGR, driven by certified-seed subsidies and traceability programs.
The market divides into open-pollinated, hybrid diploid and hybrid triploid (seedless) seed, each available untreated or film-coated/pelleted. Hybrid diploid holds about 58% share, while triploid seed is the fastest-growing type at roughly 12.1% CAGR.
Syngenta Group, Bayer AG, BASF SE, UPL Limited and Sakata Seed Corporation lead the field, collectively holding roughly half of global revenue. Sakata is particularly strong in triploid breeding, while BASF leads in integrated seed-treatment technology.
Seedless (triploid) watermelons sell at a 15–25% retail premium and account for over 80% of US production. Improved tetraploid parent lines have lifted lab germination to 90–99%, making triploid seed more reliable and commercially attractive for large growers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with proprietary breeders, commercial seed multipliers, seed-treatment and coating specialists, regional distributors and large-scale grower operations. Decision-makers interviewed include VP-level sourcing leads, heads of breeding and R&D, technical directors responsible for germination and phytosanitary compliance, and commercial operations leads managing dealer networks.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Breeding & R&D Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Technical & Phytosanitary Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Proprietary Breeders & Seed Multipliers | 40% |
| Seed Treatment & Coating Specialists | 25% |
| Regional Distributors & Dealers | 20% |
| Large-Scale Grower Operations | 15% |
Estimates were benchmarked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) under HS code 120770, corporate annual filings and investor presentations, patent databases tracking triploid and genomic-selection IP, and technical standards published by international seed-quality and phytosanitary bodies.
Top-down macroeconomic and acreage-based allocation was run simultaneously with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Divergences between the two approaches were reconciled through segment-level elasticity assumptions and trade-flow validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |