 Greenhouse Irrigation System Market
 Outlook 2025
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 216

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Greenhouse Irrigation System Market
Atul Bhusare
Research Associate

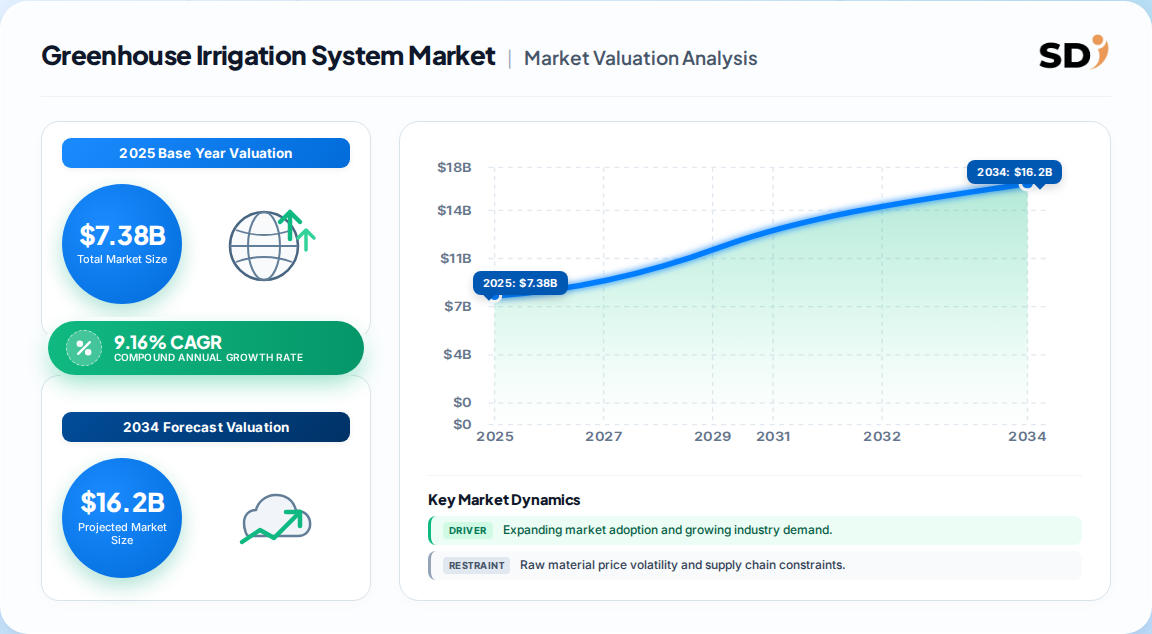
| Year | Market Size |
|---|---|
| 2024 | 6.760 B |
| 2025 | 7.380 B |
| 2026 | 8.060 B |
| 2027 | 8.800 B |
| 2028 | 9.600 B |
| 2029 | 10.48 B |
| 2030 | 11.44 B |

The greenhouse irrigation system market encompasses technologies and components—drip lines, sprinklers, subsurface systems, pumps, valves, filters, and controllers—designed to deliver water and nutrients efficiently within controlled-environment agriculture. It serves vegetable, fruit, flower, and herb growers seeking yield optimization and resource conservation.
This report covers irrigation types (drip, sprinkler, surface, subsurface), automation levels (fully automated, semi-automated, manual), crop types (vegetables, fruits, flowers, herbs), and key components (pipes, valves, pumps, filtration, controllers) across five major regions. This analysis does not cover open-field irrigation, greenhouse climate control systems, or hydroponic nutrient delivery systems as standalone markets.
Multiple estimates converge on a high-growth trajectory, but differences in base-year scope and definition create variance in reported figures. The table below compares available benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 6.76 Billion | 2024 | 2035 | 9.16% | Broad greenhouse irrigation systems incl. components | Published industry estimate |
| USD 7.38 Billion | 2025 | 2035 | 9.16% | Same scope, forward base | Derived from published estimate |
| ~10% CAGR | 2024 | 2029 | ~10% | Narrower greenhouse irrigation focus | Competing analysis |
Our analysis suggests the USD 6.76 Billion (2024) figure is the most defensible baseline because it aligns with component-level revenue aggregation across major vendors. The ~10% short-term CAGR in competing analysis likely reflects a narrower scope excluding retrofits and manual systems, implying the broader market may sustain high single-digit to low double-digit growth through 2035.
Segmentation reveals where value concentrates: drip irrigation and fully automated systems dominate, while fruits and vegetables drive demand volume.
| Parent Segment | Children |
|---|---|
| Irrigation Type | Drip, Sprinkler, Surface, Subsurface |
| Automation Level | Fully Automated, Semi-Automated, Manual |
| Crop Type | Vegetables, Fruits, Flowers, Herbs |
| Components | Pipes & Tubes, Valves, Pumps, Filtration Systems, Controllers |
Drip irrigation leads due to precise water delivery and fertigation compatibility. Sprinkler irrigation is the fastest-growing sub-segment, particularly in floriculture and nursery applications. Vegetables represent the largest crop segment, but fruits are growing fastest as high-value export horticulture expands.
North America leads in market share, but Asia-Pacific is the fastest-growing region, with Europe maintaining a strong second position driven by sustainability regulations.
| Region | Market Share (%) |
|---|---|
| North America | 0.28% |
| Europe | 0.24% |
| Asia-Pacific | 0.4% |
| South America | 0.04% |
| Middle East & Africa | 0.04% |
Our analysis indicates Asia-Pacific's growth is underpinned by government-backed protected agriculture initiatives and rising domestic demand for fresh produce. North America's leadership reflects advanced technology adoption and large-scale commercial greenhouse operations.
Demand is propelled by food security imperatives, government incentives, and technological integration, while high upfront costs and fragmented grower awareness restrain faster adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising food security demand | Driver | High | Population growth and urbanization drive protected cultivation |
| Government incentives | Driver | Medium | Subsidies and grants lower adoption barriers |
| IoT and automation advancements | Driver | High | Enables precision water management and yield optimization |
| Urban agriculture interest | Driver | Medium | Local food production trends increase greenhouse adoption |
| Sustainability regulations | Driver | Medium | Water-use efficiency mandates favor advanced irrigation |
| High initial investment | Restraint | High | Capital costs deter smallholder adoption |
| Fragmented grower knowledge | Restraint | Medium | Limited technical awareness slows technology uptake |
The balance of evidence favors strong demand-side momentum, but cost barriers mean adoption will be uneven across farm sizes. Vendors offering modular, scalable solutions may bridge the gap for mid-sized growers.
The competitive landscape is moderately consolidated, with established irrigation majors competing on technology integration, water efficiency, and global distribution.
| Company | Headquarters | Key Focus Areas |
|---|---|---|
| Netafim | Israel | Drip irrigation, precision fertigation |
| Rain Bird Corporation | USA | Sprinkler systems, controllers |
| Hunter Industries | USA | Irrigation components, smart controllers |
| Toro Company | USA | Micro-irrigation, landscape systems |
| Jain Irrigation Systems | India | Drip and sprinkler irrigation |
| Valmont Industries | USA | Pivot and precision irrigation |
| AquaSpy | USA | Soil moisture sensing |
| Irritec | Italy | Drip and micro-irrigation |
| Lindsay Corporation | USA | Mechanized irrigation |
Differentiation hinges on controller intelligence and integration capability. Netafim and Jain leverage agronomic expertise and emerging-market distribution, while US players emphasize automation and data analytics. Our analysis suggests competitive moats are strengthening around software and sensor ecosystems, raising barriers for component-only suppliers.
Procurement decisions should prioritize total cost of ownership over upfront price. Fully automated systems carry higher initial costs but reduce labor and water consumption, often achieving payback within three to five years for high-value crops. Buyers should evaluate controller interoperability and sensor compatibility to avoid vendor lock-in. Regulatory compliance with water-use standards is increasingly critical in Europe and parts of North America. Switching costs are moderate for component replacements but high for full system overhauls, making initial vendor selection strategically important. Buyers should also assess local service networks and spare-part availability, as downtime in controlled environments can cause rapid crop loss.
The balance of evidence favors a technology-led growth narrative: the market is expanding at a robust 9.16% CAGR, with automation and IoT integration as the primary value drivers. The strongest counter-argument is that high upfront costs and grower fragmentation could delay mass adoption, particularly in emerging markets. However, government incentives and food security imperatives are likely to offset these restraints, making the growth trajectory defensible.
Our analysis suggests vendors should prioritize interoperable, modular systems that allow growers to scale automation incrementally. Component-only suppliers face margin compression as value migrates toward software and analytics. The Asia-Pacific region presents the most attractive growth opportunity, but localized service and financing models will be critical to success.
Actionable Strategy:
What would change our conclusion: evidence of a sustained slowdown in government agricultural subsidies or a sharp rise in water costs that accelerates adoption faster than forecast.
Our analysis is grounded in a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including component manufacturers, system integrators, greenhouse operators, and distributors. Decision-makers interviewed included procurement directors, heads of agronomy, technical operations leads, and commercial strategy executives.
We triangulated findings against official trade databases (UN Comtrade, US ITC, Eurostat), corporate filings (10-K, annual investor presentations), patent databases, and standards from recognized industry associations. All secondary sources were validated for scope alignment and recency.
We applied simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling to derive market size and forecast. Growth rates were cross-validated against historical adoption curves and demand elasticity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025-2035 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.16% from 2020-2034 |
| Segmentation |
|
The market was valued at USD 6.76 Billion in 2024 and is projected to reach USD 17.74 Billion by 2035, growing at a 9.16% CAGR.
Asia-Pacific is the fastest-growing region, driven by protected agriculture expansion in China and India, while North America holds the largest share.
Drip irrigation is the largest segment due to its water efficiency and compatibility with precision fertigation in high-value crops.
Leading vendors include Netafim, Rain Bird, Hunter Industries, Toro Company, Jain Irrigation Systems, and Valmont Industries.
Food security demand, government incentives, IoT-enabled automation, and sustainability regulations are the primary growth drivers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is grounded in a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including component manufacturers, system integrators, greenhouse operators, and distributors. Decision-makers interviewed included procurement directors, heads of agronomy, technical operations leads, and commercial strategy executives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Directors | 35% |
| Heads of Agronomy | 30% |
| Technical Operations Leads | 20% |
| Commercial Strategy Executives | 15% |
| Company Type | Representation (%) |
|---|---|
| Component Manufacturers | 40% |
| System Integrators | 30% |
| Greenhouse Operators | 20% |
| Distributors | 10% |
We triangulated findings against official trade databases (UN Comtrade, US ITC, Eurostat), corporate filings (10-K, annual investor presentations), patent databases, and standards from recognized industry associations. All secondary sources were validated for scope alignment and recency.
We applied simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling to derive market size and forecast. Growth rates were cross-validated against historical adoption curves and demand elasticity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025-2035 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |