 Agricultural Adjuvants Market
: Size, Share & 2033 Outlook
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 251

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Agricultural Adjuvants Market
Atul Bhusare
Research Associate

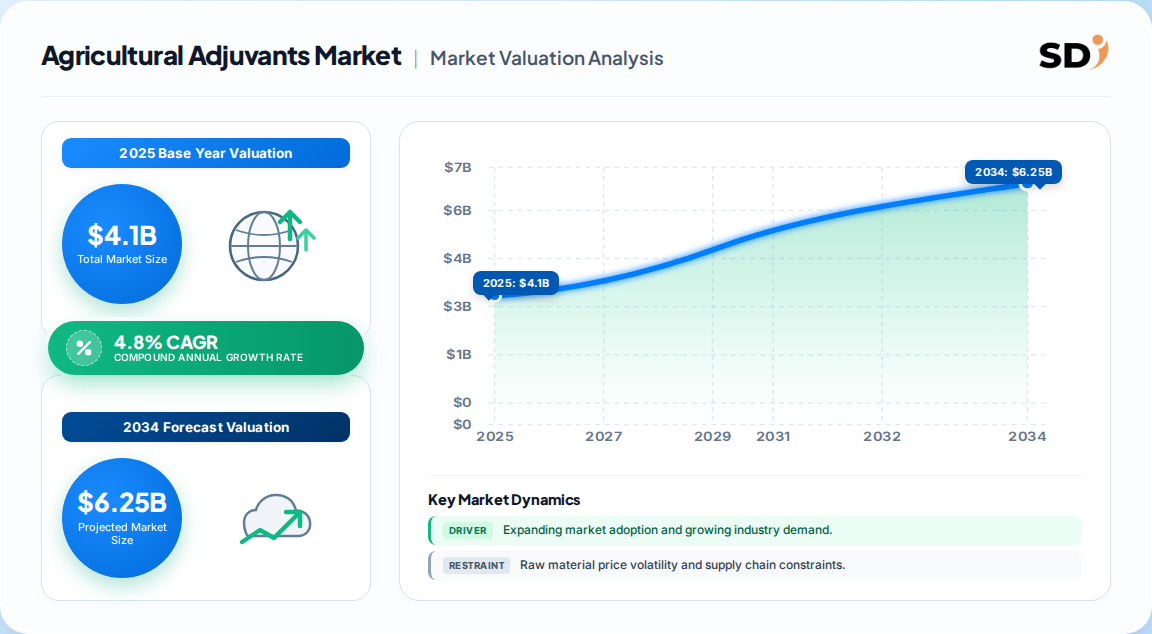
| Year | Market Size |
|---|---|
| 2025 | 4.100 B |
| 2026 | 4.300 B |
| 2027 | 4.510 B |
| 2028 | 4.720 B |
| 2029 | 4.950 B |
| 2030 | 5.190 B |
| 2031 | 5.440 B |

The agricultural adjuvants market covers additives blended into or tank-mixed with crop protection chemicals to improve mixing, spray coverage, adhesion, penetration, and drift control. It spans activator adjuvants (surfactants, oil carriers) and utility adjuvants (buffers, antifoams, drift agents) sold to formulators, distributors, and growers.
This analysis covers global agricultural adjuvants by product type, application, crop, chemical group, and region, with base-year valuation and multi-year forecasting through 2033. It examines vendor strategy, regulatory dynamics, and procurement economics across the value chain.
This analysis does not cover standalone crop protection chemical markets, fertilizer markets, seed treatment coatings, or spray equipment manufacturing, except where they directly shape adjuvant demand.
Estimates diverge sharply: 2025 valuations cluster near USD 4.1 billion, yet published CAGRs span 3.8% to 14.3%. The gap reflects differing definitions — whether tank-mix adjuvants, in-can surfactants, and drift control agents are all counted — rather than genuine demand disagreement.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 4.1 Billion | 2025 | 2033 | ~4.8% | Activator + utility adjuvants, global | One published estimate |
| USD 3.07 Billion | 2023 | 2032 | 14.3% | Broad adjuvant definition, incl. chemical groups | A competing analysis |
| USD 2.1 Billion | 2025 | 2033 | 3.8% | Narrower commercial adjuvant scope | A competing analysis |
| ~USD 4.3 Billion | 2026 | 2033 | ~4.8% | Mid-case, utility-inclusive | Analyst synthesis |
Our analysis suggests the ~4.8% mid-case is most defensible: it aligns with mature agrochemical volume growth, precision-spraying adoption, and regulatory drag on legacy surfactants. The 14.3% figure likely embeds a narrower 2023 base and aggressive bio-based substitution assumptions that the installed manufacturing base cannot support near term.
Segmentation follows four axes — product, application, crop, and chemical group — with product and crop driving the sharpest growth differentiation. Activator adjuvants and fruits & vegetables are outpacing the blended market.
| Parent Segment | Children |
|---|---|
| By Product | Activator Adjuvant (Surfactants, Oil Carriers), Utility Adjuvant (Buffers, Antifoams, Drift Control Agents) |
| By Application | Herbicides, Insecticides, Fungicides, Foliar Fertilizers |
| By Crop | Cereals & Grains, Oilseeds & Pulses, Fruits & Vegetables, Others |
| By Chemical Group | Alkoxylates, Non-Ionic Surfactants, Polyacrylamides, Others |
Alkoxylates alone generated over USD 1.4 billion in 2023, confirming that non-ionic surfactant chemistry remains the commercial backbone. Buyers should note that drift-control polyacrylamides, though small, are the fastest-adopted utility class in precision spraying programs.
Asia Pacific leads with 38.7% revenue share in 2025, underpinned by China's dominant agrochemical formulation base and intensive cereal and vegetable cultivation. North America follows on high per-hectare adjuvant intensity, with Europe constrained by tighter surfactant regulation.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.39% |
| North America | 0.27% |
| Europe | 0.2% |
| Latin America | 0.09% |
| Middle East & Africa | 0.06% |
Our analysis suggests regional growth is decoupling from volume: Asia Pacific grows on acreage and input intensity, while North America grows on formulation sophistication and drift-management mandates. That implies two distinct go-to-market playbooks rather than one global pricing strategy.
Growth is driven by yield pressure on shrinking arable land and the efficiency economics of precision spraying; it is restrained by registration burden and formulation-compatibility complexity. The net balance remains positive but increasingly regulation-shaped.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Declining arable land, rising food demand | Driver | High | Raises per-hectare input efficiency needs |
| Precision spraying adoption | Driver | High | Requires optimized adjuvant formulations |
| Bio-based, low-drift mandates | Driver | Medium | Shifts mix toward eco-friendly adjuvants |
| Strict registration and toxicity rules | Restraint | High | Lengthens approval, raises compliance cost |
| Low farmer awareness in emerging markets | Restraint | Medium | Slows adoption of specialty adjuvants |
| Raw material price volatility | Restraint | Medium | Compresses formulator margins |
The balance favors growth, but the mechanism is shifting from volume to value. For operators, this means pricing power accrues to suppliers who can document regulatory compliance and spray-efficiency gains, not to commodity surfactant sellers.
Leading vendors combine surfactant chemistry depth with global distribution reach, and concentration is moderate with a long tail of regional specialists. BASF, Solvay, and Dow anchor the field, with Clariant, Huntsman, and Brenntag significant in specific chemistries and channels.
| Company | Primary strength | Differentiation |
|---|---|---|
| BASF SE | Broad adjuvant and agrochemical portfolio | Integration with crop protection systems |
| Solvay SA | Surfactant chemistry | Formulation depth and technical support |
| Dow | Adjuvant and drift-control science | Precision-spraying compatibility |
| Clariant AG | Specialty surfactants | Eco-formulation focus |
| Huntsman Corporation | Performance chemicals | Alkoxylate and non-ionic capacity |
| Brenntag | Distribution | Channel reach across emerging markets |
Competitive moats rest on registration portfolios, formulation know-how, and distributor relationships rather than raw material access alone. Our analysis suggests consolidation will continue, with bio-based adjuvant specialists the most likely acquisition targets.
Selection criteria should prioritize documented compatibility with the buyer's agrochemical portfolio, registration status in target geographies, and demonstrated drift-reduction performance under field conditions. Compatibility failures are the leading source of rework and crop damage claims.
Procurement risk concentrates in single-source surfactant supply and in registrations that delay product launch by quarters. Switching costs are moderate for commodity surfactants but high for tank-mix systems validated in proprietary spray programs, because revalidation consumes agronomic trial cycles.
Regulatory compliance is non-negotiable: buyers should verify toxicity dossiers, residue profiles, and biobased content claims before qualification. Operators entering emerging markets should also budget for farmer education, since awareness gaps suppress adoption more than price does.
The balance of evidence favors a mid-single-digit growth baseline of roughly 4.8%, with Asia Pacific as the volume engine and North America as the value engine. The strongest counter-argument is the 14.3% forecast, which would require rapid substitution toward bio-based adjuvants at scale; we view that as a decade-long mix shift, not a near-term inflection.
The strategic implication is that adjuvant suppliers can no longer compete on price of chemistry alone. Differentiation now sits in regulatory dossiers, spray-efficiency documentation, and co-development with precision spraying platforms. Vendors who treat adjuvants as commodities will see margin compression as buyers consolidate spend.
Evidence that would change this conclusion: sustained double-digit volume growth in bio-based adjuvants across two consecutive seasons, or regulatory harmonization that compresses registration timelines — either would justify a higher baseline.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.8% from 2020-2034 |
| Segmentation |
|
The global agricultural adjuvants market was valued at USD 4.1 billion in 2025, with mid-case forecasts reaching roughly USD 6.0 billion by 2033. Published estimates vary widely due to differing scope definitions.
A defensible mid-case CAGR is approximately 4.8% from 2026 to 2033. Some analyses cite up to 14.3%, but those rely on narrower bases and aggressive bio-based substitution assumptions.
Asia Pacific held 38.7% revenue share in 2025, led by China's formulation base and intensive cereal and vegetable cultivation. North America follows on high per-hectare adjuvant intensity.
Fruits & vegetables is forecast to grow fastest at roughly 5.6% CAGR, driven by high-value crop economics and intensive spray programs. Cereals & grains remains the largest volume segment.
Strict regulatory standards on surfactant toxicity and residues lengthen registration and raise compliance costs. Low farmer awareness in emerging markets and raw material price volatility further constrain growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split, ensuring market sizing is anchored in direct industry validation rather than desk inference. In-depth interviews were conducted across the value chain, spanning specialty chemical and surfactant producers, adjuvant formulators and blenders, contract manufacturing organizations, and global agrochemical distributors. Decision-maker designations interviewed include VP-level Sourcing leads, Heads of Formulation R&D, Technical Directors responsible for spray application science, and Commercial Operations Leads managing regional channel strategy. Interview programs were structured to capture both capacity-side and demand-side perspectives, allowing cross-validation of volume and pricing assumptions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement & Sourcing Directors | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical & Surfactant Producers | 45% |
| Formulators & Blenders | 35% |
| Distributors & Traders | 20% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO), national trade statistics (US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent landscapes for surfactant and drift-control chemistry, and technical standards published by recognized industry associations. These sources anchor volume flows, pricing benchmarks, and regulatory timelines without reliance on any third-party market research publisher.
We run simultaneous Top-Down allocation from macroeconomic agrochemical expenditure and crop-acreage data, and Bottom-Up modeling from manufacturer capacity, formulation pricing, and end-use consumption per hectare. Divergences between the two models are reconciled through primary interview evidence, with residual gaps flagged for the analyst review layer.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |