 Generative AI In Agriculture Market
 Size, CAGR & 2035 Forecast
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 232

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Generative AI In Agriculture Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 270.0 M |
| 2026 | 337.0 M |
| 2027 | 419.0 M |
| 2028 | 521.0 M |
| 2029 | 647.0 M |
| 2030 | 803.0 M |
| 2031 | 998.0 M |

The Generative AI In Agriculture Market covers AI systems that synthesize novel outputs — field-specific prescriptions, simulated crop-growth scenarios, synthetic training data and natural-language agronomic advice — rather than merely classifying or predicting. It spans machine learning, computer vision, NLP and GAN-based platforms deployed across precision farming, robotics, livestock monitoring, drone analytics and labor management.
This report covers global generative AI software platforms, embedded models and related integration services sold into agricultural production, from 2025 to 2035. It segments by technology and application across five regions. This analysis does not cover conventional precision-agriculture hardware, farm-management ERP without generative capability, or general-purpose enterprise AI spend outside agriculture.
Published estimates disagree materially, which itself signals an early, rapidly re-basing market. The table below compares the most credible benchmarks on a like-for-like value basis.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 269.78 Million | 2025 | 2035 | 24.23% | Generative AI software and platforms, global | One published estimate |
| 337.28 Million | 2026 | 2035 | 24.23% | Same definition, forward base year | One published estimate |
| 227.40 Million | 2024 | 2034 | 28.10% | Generative AI in agriculture, global | A competing analysis |
| 225.80 Million | 2024 | 2035 | 28.63% | Generative AI tools and platforms, global | A competing analysis |
The 2024 base-year figures cluster tightly (225.8–227.4 Million), which builds confidence in the near-term sizing. The divergence is almost entirely in the terminal value: 2.36 Billion versus 3.60 Billion by 2035. Our analysis suggests the conservative 24.23% CAGR is more defensible because it implicitly prices in rural connectivity constraints and fragmented data standards that cap near-term deployment; the 28.63% path assumes frictionless integration that current infrastructure does not support. Buyers should base investment cases on the 24% trajectory and treat upside as optionality.
Segmentation follows two axes — technology layer and application domain — with the technology mix shifting fastest toward generative architectures.
| Parent segment | Children | 2024/2026 position |
|---|---|---|
| By Technology | Machine Learning, Computer Vision, Natural Language Processing, Generative Adversarial Networks | ML ~44% share; CV fastest-growing |
| By Application | Precision Farming, Agricultural Robotics, Livestock Monitoring, Drone Analytics, Labor Management, Smart Greenhouse | Precision farming ~43% share; robotics ~39% |
This structure matters because value is migrating: machine learning monetizes today, but NLP copilots and GANs for synthetic data are where new license revenue is forming. Vendors anchored only in classical ML risk commoditization as foundation models absorb baseline prediction.
North America leads with more than 40% of global revenue, underpinned by advanced rural digital infrastructure, dense agritech venture funding and mature farm-platform penetration. Asia-Pacific is the fastest-growing region, propelled by publicly funded digital-agriculture programs.
| Region | Market Share (%) |
|---|---|
| North America | 0.42% |
| Europe | 0.24% |
| Asia-Pacific | 0.23% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | Share |
|---|---|
| North America | 42% |
| Europe | 24% |
| Asia-Pacific | 23% |
| Latin America | 6% |
| Middle East & Africa | 5% |
The implication is structural: North America will set pricing and product norms through 2030, but volume growth shifts to Asia-Pacific as government subsidy channels (notably India's Digital Agriculture Mission) lower the cost of entry. Vendors should localize pricing and partner with public programs rather than chase only high-ARPU Western accounts.
Growth is demand-pull, not supply-push: food security, labor scarcity, climate volatility and sustainability mandates converge to make generative AI a strategic line item rather than an experiment.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising global food demand | Driver | High | Yield intensification via optimized input prescriptions |
| Agronomic labor scarcity | Driver | High | Copilots reduce dependence on scarce field expertise |
| Climate volatility | Driver | Medium-High | Scenario simulation enables pre-emptive planting and irrigation shifts |
| Sustainability compliance | Driver | Medium | Automated plot-level carbon and nutrient reporting |
| High upfront cost | Restraint | High | Hardware, integration and model maintenance deter smallholders |
| Fragmented data standards | Restraint | High | Raises integration cost and total cost of ownership |
| Rural connectivity gaps | Restraint | High | Constrains real-time cloud deployment |
| Data privacy and liability ambiguity | Restraint | Medium | Slows risk-averse enterprise rollouts |
The balance favors growth, but the binding constraint is economic accessibility, not technology. When zero-rated data access measurably lifts farmer engagement (as seen in East African advisory pilots), it confirms that the marginal adopter is blocked by connectivity cost and trust, not by model quality. That reframes go-to-market: distribution and connectivity partnerships may matter more than algorithmic differentiation.
The field is medium-concentration, split between diversified technology majors, agritech specialists and incumbent farm-platform owners — each with a different moat.
| Company | Archetype | Core strength | Moat |
|---|---|---|---|
| IBM | Technology major | Enterprise AI, weather and agronomy data | Cloud and research scale |
| Microsoft | Technology major | Cloud infrastructure, AI tooling | Azure distribution |
| aWhere | Agritech specialist | Agricultural intelligence data | Data depth |
| Granular | Farm-management platform | Farm records and analytics | Installed acreage |
| Prospera | Agritech specialist | Computer vision for crops | Proprietary field data |
| Bayer (Climate FieldView) | Incumbent platform | 275M+ subscribed acres | Distribution and field records |
| Syngenta (Cropwise) | Incumbent platform | Satellite + AI crop insights | Partnership and hectares monitored |
Our analysis suggests the durable moats sit with platform incumbents that already own farm records and distribution; stand-alone model vendors must add integration and agronomy delivery capacity or be relegated to component suppliers. The competitive fault line is data ownership, not model performance.
Selection should hinge on four criteria: integration with existing farm-management and equipment data, proven local agronomic accuracy across multiple seasons, total cost including connectivity and training, and clear liability and data-ownership terms. Procurement risk concentrates in vendor lock-in through proprietary data schemas and in models trained on non-local datasets that degrade in accuracy outside their origin geography.
Switching costs are rising as platforms accumulate field histories; buyers should negotiate data portability and export rights upfront. Regulatory exposure is real but uneven — carbon and nutrient reporting rules create compliance value, while AI liability frameworks remain unsettled. Operators should pilot on a single high-value use case (yield prescription or disease detection) before enterprise rollout, and require vendors to document validation against local conditions.
The balance of evidence favors the conservative growth path: a 24.23% CAGR to roughly 2.36 Billion by 2035 is the defensible planning base, with the 28.63% scenario representing upside contingent on connectivity investment and data standardization. The strongest counter-argument is that foundation-model cost deflation could accelerate adoption faster than infrastructure improves, pushing the market toward the aggressive path; we view this as plausible but not base case before 2030.
Strategically, value is consolidating around data and distribution rather than models. Incumbent platforms that already own farm records can layer generative features onto existing relationships at low marginal cost, while pure-play model vendors face commoditization as general-purpose models absorb baseline capability. Asia-Pacific's public-funding channels represent the most under-priced distribution route for the next five years.
Actionable strategy:
What would change our conclusion: evidence of rapid, low-cost rural connectivity expansion combined with enforceable data-interoperability standards would justify migrating to the aggressive forecast and repricing integration-heavy vendors upward.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 24.23% from 2020-2034 |
| Segmentation |
|
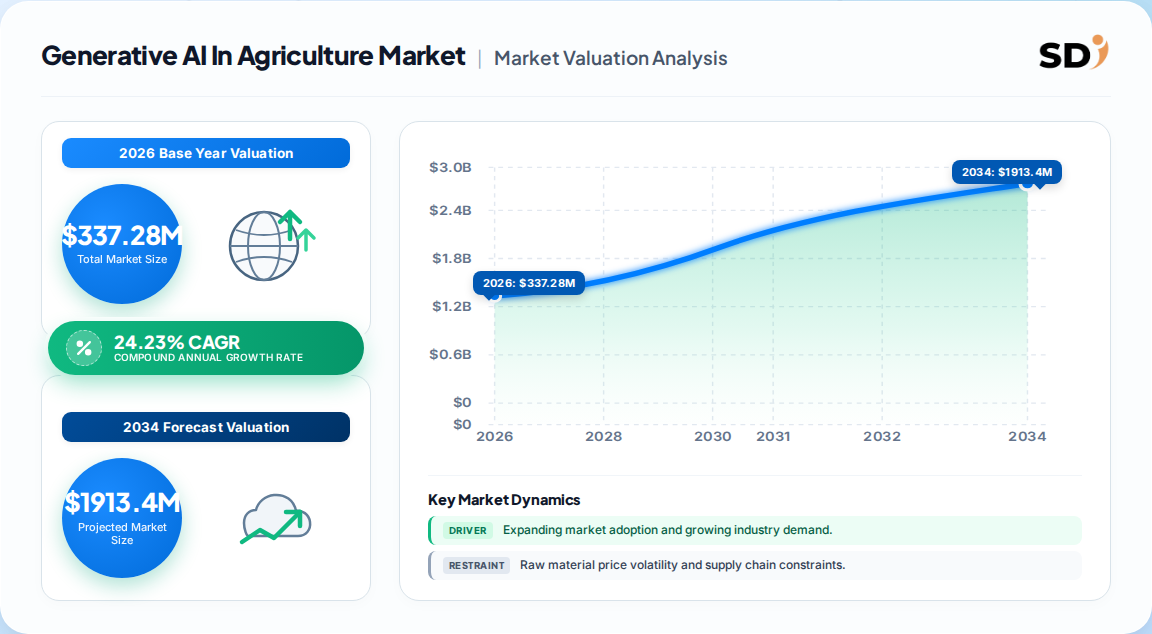
The market is valued at approximately 337.28 Million in 2026, building on 269.78 Million in 2025. Published estimates for the 2024 base year cluster near 226–227 Million, confirming the near-term sizing before compounding takes hold.
The most defensible CAGR is 24.23% through 2035, reaching roughly 2.36 Billion. More aggressive published models cite 28.63%, but that assumes frictionless integration and faster rural connectivity improvement than current infrastructure supports.
North America leads with more than 40% of global revenue, driven by rural digital infrastructure, agritech venture funding and mature farm-platform penetration. Asia-Pacific is the fastest-growing region, supported by publicly funded digital-agriculture programs.
Precision farming leads with roughly 43% of application revenue, followed by agricultural robotics and automation near 39%. Livestock monitoring, drone analytics, labor management and smart greenhouse control are secondary but fast-growing domains.
Leading players include IBM, Microsoft, aWhere, Granular, Prospera, Bayer's Climate FieldView and Syngenta's Cropwise. Platform incumbents with farm records and distribution hold the strongest moats; stand-alone model vendors must add integration capacity.
High upfront costs, fragmented agronomic data standards, rural connectivity gaps and unresolved data privacy and liability frameworks are the principal restraints. These disproportionately deter smallholders and slow enterprise rollouts in risk-averse jurisdictions.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the agricultural AI value chain, including agritech software developers, farm-equipment OEMs, satellite and drone imagery providers, and agricultural advisory and distribution firms. Decision-makers interviewed included Heads of Agronomy, VP-level Product and Platform Leads, Chief Technology Officers, and Commercial Operations Directors responsible for grower-facing deployment. Fieldwork focused on deployment economics, integration friction and realized yield outcomes.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of Agronomy & Product | 40% |
| CTOs & Technology Leads | 30% |
| Commercial Operations Directors | 30% |
| Company Type | Representation (%) |
|---|---|
| Agritech Software & Platform Developers | 40% |
| Farm Equipment & Robotics OEMs | 25% |
| Satellite & Drone Imagery Providers | 20% |
| Advisory & Distribution Firms | 15% |
Analysis was validated against official multilateral and standards databases, including UN Comtrade, WTO trade statistics, US ITC and Eurostat, alongside corporate annual filings (10-K and investor presentations), patent databases, and recognized industry associations and technical standards bodies. No third-party market-research publications were used as validation sources.
We applied simultaneous top-down and bottom-up triangulation. Top-down modeling allocated macroeconomic and agricultural-segment spend to generative AI use cases; bottom-up modeling built revenue from platform subscriptions, per-acre pricing and integration services. Divergence between the two was reconciled against public deployment disclosures.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |