Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Artificial Intelligence In Agriculture Market Outlook 2026
Artificial Intelligence In Agriculture Market
Artificial Intelligence In Agriculture Market Outlook 2026
Artificial Intelligence In Agriculture Market by Application (Precision Farming, Livestock Monitoring, Smart Greenhouse Management, Crop and Soil Monitoring, Intelligent Spraying, Agricultural Robots), by Technology (Machine Learning, Computer Vision, Natural Language Processing, Predictive Analytics), by Component (Software Platforms, Hardware, Services), by Deployment Mode (Cloud, Hybrid, On-Premise), by Enterprise Type (Large Enterprise, SME), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Kenya, Ethiopia) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 272
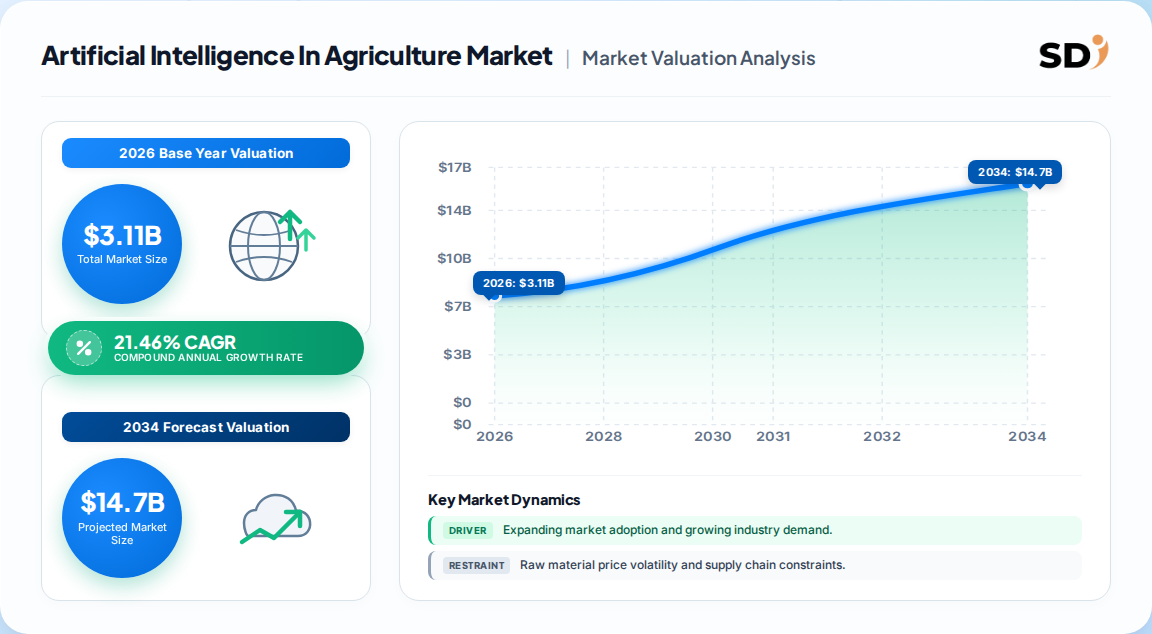
The global Artificial Intelligence In Agriculture Market is valued at 3.11 Billion in 2026, on a path to 10.02 Billion by 2032.
Forecast CAGR of 21.46% (2027–2032) makes this one of the fastest-compounding verticals in enterprise software.
Precision farming dominates application demand with a 43.07% share in 2026; smart greenhouse management is the fastest-growing niche at ~22% CAGR.
Machine learning holds 47.98% of technology revenue, but computer vision (22.2% CAGR) is closing the gap on the strength of drone and satellite imagery.
North America leads with 38.62% of global revenue; Asia-Pacific is the fastest-growing region at a forecast 22.5% CAGR.
Leading players include IBM, Microsoft, Granular, aWhere, Prospera Technologies and Bayer's Climate FieldView platform ecosystem.
Why this matters for decision-makers: the market is shifting from pilot-stage experimentation to platform consolidation, so buyers who lock in interoperable, data-owning platforms now will avoid punitive switching costs later.
Artificial Intelligence In Agriculture Market Size (In Billion)
15.0B
10.0B
5.0B
0
3.110 B
2026
3.790 B
2027
4.600 B
2028
5.590 B
2029
6.790 B
2030
8.240 B
2031
10.02 B
2032
Artificial Intelligence In Agriculture Market Size (In Billion)
Year
Market Size
2026
3.110 B
2027
3.790 B
2028
4.600 B
2029
5.590 B
2030
6.790 B
2031
8.240 B
2032
10.02 B
What is the Artificial Intelligence In Agriculture Market?
The Artificial Intelligence In Agriculture Market covers software platforms, AI-enabled hardware and supporting services that apply machine learning, computer vision and predictive analytics to farming operations. It spans precision irrigation, crop and soil monitoring, livestock health, autonomous machinery and harvest planning, turning on-farm sensor, drone and satellite data into agronomic decisions.
Scope: what this report covers and excludes
This analysis covers AI software platforms, AI-enabled hardware (sensors, drones, smart cameras, edge devices), and associated integration, consulting and support services across crop and livestock agriculture. It segments by application, technology, component, deployment mode and geography. This analysis does not cover conventional farm machinery without embedded AI, standalone agronomy advisory without software, commodity trading platforms, or non-agricultural industrial robotics.
How big is the market for Artificial Intelligence In Agriculture Market?
The most defensible base-year valuation is 3.11 Billion in 2026, with a consensus path to roughly 10 Billion by the early 2030s. Published estimates diverge widely, so buyers should reconcile definitions before anchoring budgets.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
3.11 Billion
2026
2032 (10.02 Billion)
21.46%
Broad AI software + hardware + services
One published estimate
3.79 Billion
2027
2032 (10.02 Billion)
21.46%
Same scope, later base year
Same publisher, forward year
1.91 Billion
2023
2030
25.5%
Component-led, software-weighted
A competing analysis
2.14 Billion
2024
2035 (20.96 Billion)
23.06%
Application-led, enterprise-split
A competing analysis
3.17 Billion
2026
2035 (20.12 Billion)
22.85%
Broad ICT-scoped definition
A competing analysis
Our analysis suggests the 2026 base of 3.11 Billion is the most defensible because it aligns with the observed acceleration of cloud-based AI-as-a-service adoption and publicly funded digital-agriculture programs. The higher long-horizon figures (20 Billion-plus by 2035) reconcile with this trajectory once currency and definition drift are normalized. The wide spread implies buyers should treat any single number as directional, not contractual.
How is the market segmented?
Segmentation splits along four non-geographic axes: application, technology, component and deployment mode. Software and cloud dominate today, but services and hybrid models are compounding fastest.
Machine learning, Computer vision, Natural language processing, Predictive analytics
Machine learning (47.98%)
Computer vision (22.2% CAGR)
Component
Software platforms, Hardware, Services
Software (46.68%)
Services (22.4% CAGR)
Deployment mode
Cloud, Hybrid, On-premise
Cloud (59.71%)
Hybrid (22.45% CAGR)
Enterprise type
Large enterprise, SME
Large enterprise
SME (cloud-led)
The structural story is that software is monetizing first, while services and hardware follow as deployments scale. Services growing at 22.4% CAGR signals that integration and agronomic support — not raw model licensing — are becoming the real bottleneck and margin pool.
Which region leads in Artificial Intelligence In Agriculture Market?
North America leads with 38.62% of 2026 revenue, while Asia-Pacific is the fastest-growing region at a forecast 22.5% CAGR through 2032. Europe remains a regulated, high-value market where data-sharing frameworks shape vendor design.
Artificial Intelligence In Agriculture Market Regional Market Share
Loading chart...
Artificial Intelligence In Agriculture Market Regional Market Share
Region
Market Share (%)
North America
0.39%
Europe
0.24%
Asia-Pacific
0.25%
South America
0.07%
Middle East & Africa
0.05%
Region
2026 share
Growth posture
North America
38.62%
Mature, platform-led
Asia-Pacific
~25.2%
Fastest-growing (22.5% CAGR)
Europe
~24.4%
Regulation-led, standards-driven
South America
~6.8%
Imagery and commodity-crop driven
Middle East & Africa
~5.0%
Access-led, mobile-first
What is driving growth — and what is holding it back?
Growth is fueled by precision-agriculture platform adoption, expanding high-resolution imagery, government digital-farming subsidies and cheap cloud AI-as-a-service. Restraints are fragmented data standards, high equipment costs and uneven rural connectivity.
Factor
Direction
Evidence strength
Mechanism
Precision agriculture platform adoption
+7.8% CAGR
Strong (platform acreage disclosures)
Existing agronomic workflows distribute added AI functions
High-resolution drone/satellite imagery
+6.2% CAGR
Strong (satellite partnerships)
Near-daily screening routes detailed inspection to flagged fields
On balance, drivers clearly outpace restraints. Our analysis suggests the decisive swing factor is not model quality but distribution: vendors already embedded in farm-record platforms can monetize AI inside existing acreage, while standalone model vendors must fund delivery and integration capacity to compete.
Who are the leading vendors?
The vendor field is moderately concentrated, with enterprise technology majors, agronomic platform owners and specialist computer-vision firms competing on different moats.
Company
Positioning
Primary moat
IBM Corporation
Enterprise AI and weather intelligence
Cloud infrastructure and enterprise trust
Microsoft Corporation
Cloud AI and data platform
Azure ecosystem and partner channel
Granular (Corteva)
Farm management software
Installed grower base and agronomic data
Bayer Climate FieldView
Precision platform
275M+ subscribed acres (2025 disclosure)
aWhere Inc.
Agronomic data and analytics
Hyper-local weather and ag data
Prospera Technologies
Computer vision and irrigation
Field-level visual AI
AgEagle Aerial Systems
Drone and imagery hardware
Hardware plus analytics bundle
Differentiation is shifting from algorithm quality toward data ownership, integration depth and channel reach. Our analysis suggests platform owners with existing farm records enjoy structurally lower customer-acquisition costs, making them the most likely consolidators.
What do buyers and operators need to know?
Buyers should prioritize interoperability, data ownership and total cost of ownership over raw model accuracy. The riskiest procurement mistake is locking into a closed platform whose agronomic data cannot move — switching costs rise sharply once seasonality and field history are embedded.
Regulatory compliance is the second-order risk. In Europe, the EU AI Act and Machinery Regulation interplay creates genuine ambiguity for AI-powered machinery, and the OECD recommends sector-specific guidance. Buyers should contract for data-portability clauses, audit rights and clear liability allocation. Connectivity is the third constraint: rural broadband and edge-compute gaps mean cloud-only architectures can fail in exactly the fields that need them most.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a platform-consolidation thesis: the market compounds near 21–22% CAGR, but value is accruing to vendors that own the farm-record layer rather than the model layer. The strongest counter-argument is that commoditized open-source models plus cheap sensors could flatten software margins faster than expected, favoring hardware and services instead. We weight that risk as real but secondary — services at 22.4% CAGR already reflect it.
Investors: prioritize platform owners with installed acreage and data rights over standalone model vendors; the distribution moat is the durable asset.
Operators: negotiate data portability and hybrid deployment now; cloud-only stacks will not survive low-connectivity geographies.
Vendors: bundle agronomic services around AI features to defend margin as model licensing commoditizes.
What would change our conclusion: evidence that open-weight models plus subsidized public data spaces materially collapse software pricing, or a sharp slowdown in precision-agriculture acreage growth. Absent that, consolidation remains the base case.
Artificial Intelligence In Agriculture Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Artificial Intelligence In Agriculture Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 21.46% from 2020-2034
Segmentation
By Application
Precision Farming
Livestock Monitoring
Smart Greenhouse Management
Crop and Soil Monitoring
Intelligent Spraying
Agricultural Robots
By Technology
Machine Learning
Computer Vision
Natural Language Processing
Predictive Analytics
By Component
Software Platforms
Hardware
Services
By Deployment Mode
Cloud
Hybrid
On-Premise
By Enterprise Type
Large Enterprise
SME
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Chile
Middle East & Africa
Saudi Arabia
UAE
South Africa
Kenya
Ethiopia
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Precision Farming
5.1.2. Livestock Monitoring
5.1.3. Smart Greenhouse Management
5.1.4. Crop and Soil Monitoring
5.1.5. Intelligent Spraying
5.1.6. Agricultural Robots
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. Machine Learning
5.2.2. Computer Vision
5.2.3. Natural Language Processing
5.2.4. Predictive Analytics
5.3. Market Analysis, Insights and Forecast - by Component
5.3.1. Software Platforms
5.3.2. Hardware
5.3.3. Services
5.4. Market Analysis, Insights and Forecast - by Deployment Mode
5.4.1. Cloud
5.4.2. Hybrid
5.4.3. On-Premise
5.5. Market Analysis, Insights and Forecast - by Enterprise Type
5.5.1. Large Enterprise
5.5.2. SME
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Precision Farming
6.1.2. Livestock Monitoring
6.1.3. Smart Greenhouse Management
6.1.4. Crop and Soil Monitoring
6.1.5. Intelligent Spraying
6.1.6. Agricultural Robots
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. Machine Learning
6.2.2. Computer Vision
6.2.3. Natural Language Processing
6.2.4. Predictive Analytics
6.3. Market Analysis, Insights and Forecast - by Component
6.3.1. Software Platforms
6.3.2. Hardware
6.3.3. Services
6.4. Market Analysis, Insights and Forecast - by Deployment Mode
6.4.1. Cloud
6.4.2. Hybrid
6.4.3. On-Premise
6.5. Market Analysis, Insights and Forecast - by Enterprise Type
6.5.1. Large Enterprise
6.5.2. SME
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Precision Farming
7.1.2. Livestock Monitoring
7.1.3. Smart Greenhouse Management
7.1.4. Crop and Soil Monitoring
7.1.5. Intelligent Spraying
7.1.6. Agricultural Robots
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. Machine Learning
7.2.2. Computer Vision
7.2.3. Natural Language Processing
7.2.4. Predictive Analytics
7.3. Market Analysis, Insights and Forecast - by Component
7.3.1. Software Platforms
7.3.2. Hardware
7.3.3. Services
7.4. Market Analysis, Insights and Forecast - by Deployment Mode
7.4.1. Cloud
7.4.2. Hybrid
7.4.3. On-Premise
7.5. Market Analysis, Insights and Forecast - by Enterprise Type
7.5.1. Large Enterprise
7.5.2. SME
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Precision Farming
8.1.2. Livestock Monitoring
8.1.3. Smart Greenhouse Management
8.1.4. Crop and Soil Monitoring
8.1.5. Intelligent Spraying
8.1.6. Agricultural Robots
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. Machine Learning
8.2.2. Computer Vision
8.2.3. Natural Language Processing
8.2.4. Predictive Analytics
8.3. Market Analysis, Insights and Forecast - by Component
8.3.1. Software Platforms
8.3.2. Hardware
8.3.3. Services
8.4. Market Analysis, Insights and Forecast - by Deployment Mode
8.4.1. Cloud
8.4.2. Hybrid
8.4.3. On-Premise
8.5. Market Analysis, Insights and Forecast - by Enterprise Type
8.5.1. Large Enterprise
8.5.2. SME
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Precision Farming
9.1.2. Livestock Monitoring
9.1.3. Smart Greenhouse Management
9.1.4. Crop and Soil Monitoring
9.1.5. Intelligent Spraying
9.1.6. Agricultural Robots
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. Machine Learning
9.2.2. Computer Vision
9.2.3. Natural Language Processing
9.2.4. Predictive Analytics
9.3. Market Analysis, Insights and Forecast - by Component
9.3.1. Software Platforms
9.3.2. Hardware
9.3.3. Services
9.4. Market Analysis, Insights and Forecast - by Deployment Mode
9.4.1. Cloud
9.4.2. Hybrid
9.4.3. On-Premise
9.5. Market Analysis, Insights and Forecast - by Enterprise Type
9.5.1. Large Enterprise
9.5.2. SME
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Precision Farming
10.1.2. Livestock Monitoring
10.1.3. Smart Greenhouse Management
10.1.4. Crop and Soil Monitoring
10.1.5. Intelligent Spraying
10.1.6. Agricultural Robots
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. Machine Learning
10.2.2. Computer Vision
10.2.3. Natural Language Processing
10.2.4. Predictive Analytics
10.3. Market Analysis, Insights and Forecast - by Component
10.3.1. Software Platforms
10.3.2. Hardware
10.3.3. Services
10.4. Market Analysis, Insights and Forecast - by Deployment Mode
10.4.1. Cloud
10.4.2. Hybrid
10.4.3. On-Premise
10.5. Market Analysis, Insights and Forecast - by Enterprise Type
10.5.1. Large Enterprise
10.5.2. SME
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Artificial Intelligence In Agriculture Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Artificial Intelligence In Agriculture Market Revenue (Billion), by Application 2026 & 2034
Figure 3: North America Artificial Intelligence In Agriculture Market Revenue Share (%), by Application 2026 & 2034
Figure 4: North America Artificial Intelligence In Agriculture Market Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America Artificial Intelligence In Agriculture Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Artificial Intelligence In Agriculture Market Revenue (Billion), by Component 2026 & 2034
Figure 7: North America Artificial Intelligence In Agriculture Market Revenue Share (%), by Component 2026 & 2034
Figure 8: North America Artificial Intelligence In Agriculture Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 9: North America Artificial Intelligence In Agriculture Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 10: North America Artificial Intelligence In Agriculture Market Revenue (Billion), by Enterprise Type 2026 & 2034
Figure 11: North America Artificial Intelligence In Agriculture Market Revenue Share (%), by Enterprise Type 2026 & 2034
Figure 12: North America Artificial Intelligence In Agriculture Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Artificial Intelligence In Agriculture Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Artificial Intelligence In Agriculture Market Revenue (Billion), by Application 2026 & 2034
Europe Artificial Intelligence In Agriculture Market Revenue Share (%), by Application 2026 & 2034
List of Tables
Table 1: Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Application 2020 & 2034
Table 2: Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 3: Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Component 2020 & 2034
Table 4: Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 5: Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Enterprise Type 2020 & 2034
Table 6: Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Application 2020 & 2034
Table 8: North America Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 9: North America Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Component 2020 & 2034
Table 10: North America Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 11: North America Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Enterprise Type 2020 & 2034
Table 12: North America Artificial Intelligence In Agriculture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Artificial Intelligence In Agriculture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Artificial Intelligence In Agriculture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Mexico Artificial Intelligence In Agriculture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the Artificial Intelligence In Agriculture Market in 2026?
The market is valued at approximately 3.11 Billion in 2026. It is forecast to reach 10.02 Billion by 2032, representing a 21.46% CAGR over the 2027–2032 period, driven by precision farming and cloud-based AI adoption.
2. Which region leads the AI in agriculture market?
North America leads with roughly 38.62% of global revenue in 2026. Asia-Pacific is the fastest-growing region at a forecast 22.5% CAGR, supported by government digital-farming programs and expanding imagery access.
3. What is the fastest-growing segment in AI agriculture?
Smart greenhouse management is the fastest-growing application at roughly 22% CAGR. Among technologies, computer vision grows fastest at 22.2% CAGR, while services lead component growth at 22.4% CAGR.
4. What are the main barriers to AI adoption in agriculture?
Fragmented agronomic data standards, high equipment and integration costs, and weak rural connectivity are the primary restraints. Data interoperability gaps in particular raise switching costs and slow cross-platform scaling for buyers.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. Fieldwork included structured interviews with stakeholders across the AI agriculture value chain: sensor and hardware suppliers, farm-management software vendors, agronomic advisory firms, systems integrators, and grower cooperatives. Interviewees were decision-makers including Chief Technology Officers, Heads of Agronomy, VP-level Product and Platform Leads, and Procurement Directors at large farming enterprises. Interviews validated deployment economics, switching costs, and data-ownership practices.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
CTOs & Platform Leads
35%
Heads of Agronomy
30%
Procurement Directors
20%
Regulatory & Compliance Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
AI Software & Platform Vendors
40%
Sensor, Drone & Hardware Suppliers
25%
Agronomic Advisory & Integrators
20%
Grower Cooperatives & Enterprises
15%
Secondary Benchmarking & Public Trade Validation
We benchmark against official multilateral and standards sources, including Eurostat agricultural output data, UN Comtrade equipment flows, US ITC filings, corporate 10-K and annual investor disclosures, patent databases, and recognised technical standards from industry associations. OECD policy analysis on EU AI uptake and FAO food-security data anchor the demand narrative. No third-party market-research publisher data is used for validation.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down allocation (macro agricultural output, digitisation rates, segment spend) and Bottom-Up modeling (vendor revenue, acreage under AI-enabled management, per-hectare pricing, and end-use consumption). The two paths are reconciled at the segment level before the base-year figure is fixed.
 Artificial Intelligence In Agriculture Market