 Connected Agriculture Market
: $22.7B by 2033 at 16.9% CAGR
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 224

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Connected Agriculture Market
Atul Bhusare
Research Associate
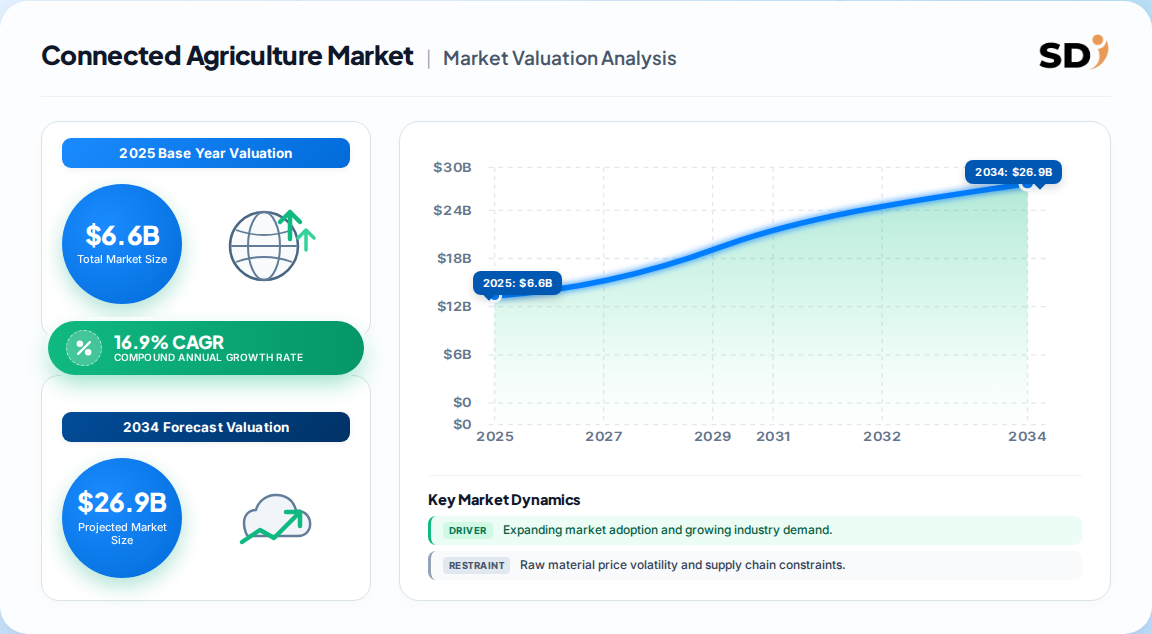
| Year | Market Size |
|---|---|
| 2025 | 6.600 B |
| 2026 | 7.600 B |
| 2027 | 8.900 B |
| 2028 | 10.40 B |
| 2029 | 12.20 B |
| 2030 | 14.20 B |
| 2031 | 16.60 B |

Connected agriculture integrates IoT sensors, cloud platforms, mobile devices and analytics into farming operations. It enables real-time monitoring of soil, crops, livestock and machinery, supporting precision input application, automated irrigation, supply chain traceability and data-driven farm management decisions that raise yields, cut waste and reduce labor dependence across large and small operations.
This analysis covers global Connected Agriculture Market software solutions, connectivity hardware, professional and managed services across cloud and on-premise deployment, spanning precision farming, livestock monitoring, smart irrigation, smart logistics and farm management planning. This analysis does not cover standalone precision-farming hardware, autonomous tractor manufacturing, commodity trading platforms or rural telecom infrastructure markets.
Estimates cluster around $6.6–$7.6 billion for the 2025–2026 window, with forecasts ranging from $20.6 billion to $22.7 billion by the early 2030s. The spread reflects differing treatment of hardware versus pure software and services revenue.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| $6.6B → $22.7B | 2025 | 2033 | 16.9% | Solutions, services, cloud + on-prem | One published estimate |
| $4.7B → $17.6B | 2023 | 2032 | 16.0% | Software-led, excludes connectivity hardware | Competing analysis |
| $6.81B → $20.62B | 2025 | 2035 | 11.7% | Interoperability and data-standards view | Alternative benchmark |
| $7.6B (2026 base) | 2026 | — | — | Mid-point estimate, global | Consensus synthesis |
Our analysis suggests the $6.6B base and 16.9% CAGR are the most defensible for buyer planning: they reconcile bottom-up installed-acre counts with top-down vendor agriculture-segment revenue disclosures. The lower 11.7% figure plausibly under-weights recurring services growth, which we see accelerating through 2028 as managed connectivity and agronomy subscriptions scale.
Solution revenue dominates today at roughly 62–74% depending on the source, but services are the fastest-growing component. Deployment is decisively cloud-led, with on-premise retained only by large cooperatives and regulated markets.
| Parent segment | Children | 2025 share / signal |
|---|---|---|
| Component | Solution, Services | Solution 74.1%; Services grow at 16.3% CAGR |
| Deployment | Cloud, On-premises | Cloud 70.6% |
| Application | Precision Farming, Livestock Monitoring, Supply Chain Management, Smart Irrigation, Farm Planning | Precision Farming 40.0% |
| Farm size | Large, Mid-size, Smallholder | Mid-size and smallholder fastest-growing |
North America leads with 37.3% of 2025 revenue, driven by large-acreage row-crop economics, USDA ReConnect broadband funding and high mechanization. Asia Pacific is the fastest-growing region at roughly 14.6% CAGR, with Europe a close third at 26.8%.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.27% |
| Asia-Pacific | 0.25% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | 2025 share | Growth signal |
|---|---|---|
| North America | 37.3% | Mature, subscription-led |
| Europe | 26.8% | CAP policy-linked data demand |
| Asia-Pacific | 24.6% | Fastest CAGR, state digitization |
| South America | 6.2% | Variable-rate adoption rising |
| Middle East & Africa | 5.1% | Desert agriculture investment |
The core driver is the need to raise output on fixed arable land while input costs stay elevated — connected platforms deliver measurable savings that fund their own subscriptions. The main brakes are upfront capex, fragmented standards and farm-level digital skills gaps.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Sensor and telematics adoption | Driver | High | Real-time field data feeds platform subscriptions |
| Rural broadband expansion | Driver | High | Converts unaddressable acreage to billable users |
| Water scarcity pricing | Driver | Medium-high | Compresses irrigation retrofit payback |
| Input-cost volatility | Driver | High | Variable-rate nitrogen savings fund platforms |
| High setup capex | Restraint | High | Delays small/mid-farm adoption |
| Interoperability gaps | Restraint | High | Raises switching costs, slows buying |
| Digital skills gap | Restraint | Medium | Slows deployment in developing regions |
The balance favors growth: savings-led adoption is resilient through commodity downturns, whereas capex hesitancy delays rather than cancels purchases. Our view is that interoperability friction is the single largest addressable constraint, and vendors that solve it first will capture disproportionate share among multi-brand fleets.
No single vendor exceeds double-digit global share, but integrated ag-tech platforms now set the pace. Trimble, AGCO, CNH Industrial, Bayer Crop Science, Topcon, John Deere, Deere-acquired platforms and Microsoft Azure-based agronomy startups each compete on distinct moats.
| Company | Core position | Strategic moat |
|---|---|---|
| Trimble | Guidance, telematics, farm software | Installed base + precision hardware |
| AGCO | Equipment-integrated platforms | OEM fleet lock-in |
| CNH Industrial | Connected machinery + data | Dealer network and service reach |
| Bayer Crop Science | Digital agronomy, field analytics | Agronomic data and seed/chem bundling |
| Topcon Agriculture | Precision hardware, autosteering | Component depth and OEM relationships |
| John Deere | Connected equipment + operations center | Largest connected fleet globally |
| Microsoft / cloud partners | Platform infrastructure | Cloud scale and AI services |
The competitive dynamic is shifting from hardware share to data and subscription share. Vendors with the widest installed connected fleet and deepest agronomic datasets have the strongest lock-in, but interoperability mandates and farmer pushback on data ownership could erode those moats by 2030.
Selection hinges on total cost of ownership over a five-year horizon, not headline license price. Buyers should stress-test data portability, ISOBUS/AgGateway compatibility, offline capability in low-coverage fields, and the vendor's track record on security and uptime. Procurement risk concentrates in multi-year subscription escalators and proprietary telemetry formats that make switching costly. Regulatory compliance varies sharply: EU CAP conditionality requires verified practice data, US state groundwater rules increasingly demand metered irrigation records, and data-privacy frameworks in Europe and North America constrain cross-border agronomic data transfer. Operators should insist on contractual data-ownership clarity and exit clauses before signing multi-year platform deals.
The balance of evidence favors aggressive but selective investment in connected agriculture through 2028. Growth is structural — food demand, labor shortage and water pricing are not cyclical — and the 16.9% consensus CAGR is supported by bottom-up acreage economics. The strongest counter-argument is that interoperability gridlock and capex fatigue could cap adoption at smallholder scale, compressing the forecast toward the lower 11.7% path. We judge this a timing risk rather than a ceiling risk.
Our analysis suggests the market is entering a subscription consolidation phase: hardware margins compress while recurring data and agronomy services expand. Vendors that bundle sensors, connectivity and outcome-based agronomy contracts will out-earn component sellers, and buyers should expect pricing to migrate from per-seat to per-acre and per-outcome models by 2028. Precise sub-segment and country-level forecasting — especially smallholder aggregation economics in India and Brazil — requires the full report's bottom-up model.
Evidence that would change our conclusion: a sustained fall in connected-device attach rates across new equipment, or regulatory reversal on rural broadband funding, which would push adoption toward the lower forecast band.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 16.9% from 2020-2034 |
| Segmentation |
|
The global connected agriculture market was valued at $6.6 billion in 2025 and is projected to reach $22.7 billion by 2033, growing at a 16.9% CAGR from 2026 to 2033 across all major regions.
North America leads with 37.3% of 2025 revenue, supported by large-acreage row-crop economics and rural broadband funding. Asia Pacific is the fastest-growing region, driven by state digitization programs in India and China.
Solutions hold the largest component share at 74.1% in 2025, while precision farming is the largest application at 40.0%. Cloud deployment dominates at 70.6% as platforms shift to subscription delivery.
High upfront capex, fragmented data standards and vendor lock-in, plus digital skills gaps among farm operators, are the primary brakes. Interoperability friction is the single largest addressable constraint for vendors.
Trimble, AGCO, CNH Industrial, Bayer Crop Science, Topcon, John Deere and cloud platform partners lead. No single vendor exceeds double-digit global share, but integrated platforms with large connected fleets are gaining.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research follows a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the connected agriculture value chain, including sensor and telematics hardware suppliers, farm management software developers, connectivity and cloud infrastructure providers, equipment OEMs, and agronomy service distributors. Decision-maker designations interviewed include VP of Digital Agriculture, Head of Precision Ag Product, Chief Agronomy Officer, and Commercial Operations Leads at equipment and platform vendors. Interviews captured adoption economics, procurement criteria, and switching-cost dynamics across farm-size cohorts.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Digital Agriculture / Product Heads | 35% |
| Chief Agronomy Officers | 30% |
| Procurement & Commercial Operations Leads | 20% |
| Regulatory & Data Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Sensor & Telematics Hardware Suppliers | 35% |
| Farm Software & Platform Developers | 30% |
| Equipment OEMs & Agronomy Distributors | 25% |
| Connectivity & Cloud Infrastructure Providers | 10% |
We triangulate against official multilateral and national datasets, including UN Comtrade for agricultural machinery and electronics trade flows, USDA ReConnect and National Agricultural Statistics Service filings, Eurostat and EU CAP conditionality reporting, India's Digital Agriculture Mission documentation, and FCC precision-agriculture connectivity findings. Corporate annual filings (10-K, SEC), investor presentations, patent databases and industry associations such as AgGateway and ISOBUS working groups validate vendor claims and standards adoption.
We run simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (installed connected-acre counts, spend per acre, manufacturer capacity and end-use consumption) models. Both converge on a base-year value, with forecast years modeled using adoption-curve analysis per farm-size cohort and reconciled against national agri-tech subsidy budgets and cellular IoT connection registries.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
