Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Agricultural Surfactants Market: Size, Trends & Outlook 2025
Agricultural Surfactants Market
Agricultural Surfactants Market: Size, Trends & Outlook 2025
Agricultural Surfactants Market by Product Type (Non-ionic, Anionic, Cationic, Amphoteric), by Substrate (Synthetic, Bio-based), by Application (Herbicides, Fungicides, Insecticides), by Form (Liquid, Powder/Granular), by Function (Wetting Agents, Penetrants, Adjuvants), by Crop Type (Cereals & Grains, Fruits & Vegetables, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 194
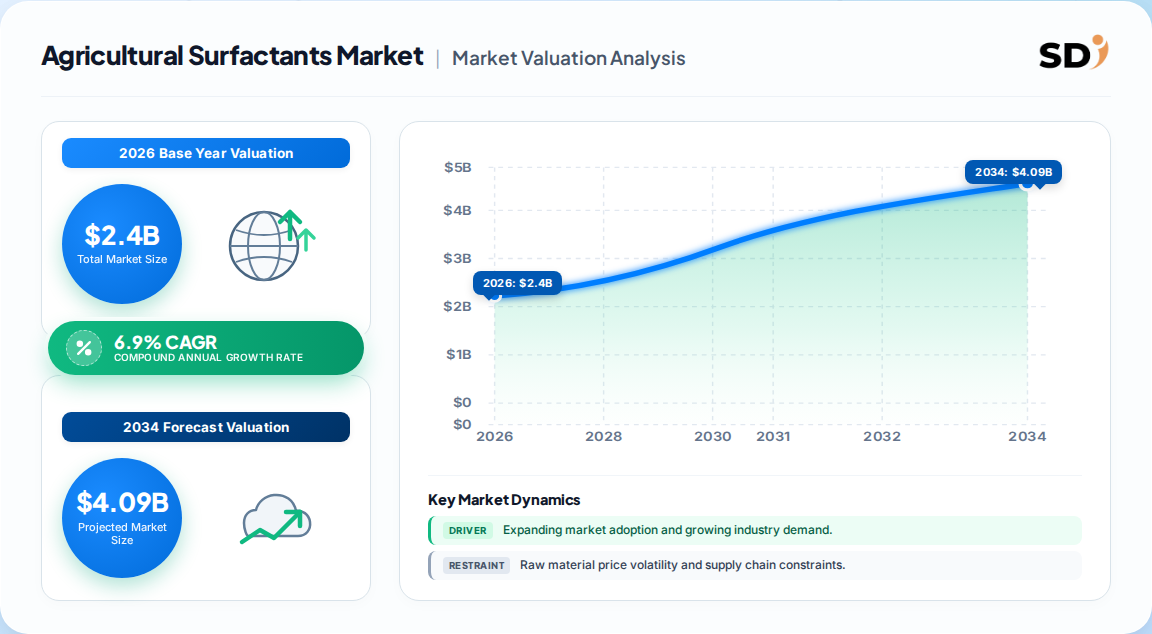
The global Agricultural Surfactants Market is valued at 2.40 Billion in 2026, scaling to 3.35 Billion by 2031.
Forecast CAGR of 6.9% (2026–2031) outpaces broader agrochemical growth, signaling rising adjuvant intensity per hectare.
Non-ionic surfactants dominate with 41% share; bio-based substrates are the fastest-growing segment at 18.1% CAGR.
Herbicides remain the largest application (46% of 2025 consumption), while fungicide adjuvants expand at 12.4% CAGR.
North America leads with 37% revenue share; Asia-Pacific is the fastest-growing region at 11.5% CAGR.
Key players include BASF, Corteva, Nouryon, Solvay, and Marubeni, competing on formulation innovation and sustainability.
Why this matters for decision-makers: Vendors must pivot to bio-based and nano-emulsion platforms within 24 months to avoid margin compression from regulatory and retailer-driven sustainability mandates.
Agricultural Surfactants Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.260 B
2025
2.400 B
2026
2.570 B
2027
2.740 B
2028
2.930 B
2029
3.130 B
2030
3.350 B
2031
Agricultural Surfactants Market Size (In Billion)
Year
Market Size
2025
2.260 B
2026
2.400 B
2027
2.570 B
2028
2.740 B
2029
2.930 B
2030
3.130 B
2031
3.350 B
What is the Agricultural Surfactants Market?
Agricultural surfactants are adjuvant chemicals that improve the spreading, wetting, penetration, and adhesion of crop protection products on plant surfaces. They enhance the efficacy of herbicides, fungicides, and insecticides, enabling lower active-ingredient doses and reducing environmental waste.
Scope: what this report covers and excludes
This report covers the global Agricultural Surfactants Market, segmented by product type (non-ionic, anionic, cationic, amphoteric), substrate (synthetic, bio-based), application (herbicides, fungicides, insecticides), form (liquid, powder/granular), function (wetting agents, penetrants, adjuvants), and crop type (cereals & grains, fruits & vegetables, others). It includes regional and country-level analysis. This analysis does not cover fertilizer adjuvants, standalone pesticide active ingredients, or non-agricultural surfactant applications.
How big is the market for Agricultural Surfactants Market?
One published estimate places the global Agricultural Surfactants Market at 2.40 Billion in 2026, with a projected 3.35 Billion by 2031 at a 6.9% CAGR. A competing analysis values the market at 1.6 Billion in 2026, reaching 2.3 Billion by 2033 at 5.1%. The divergence reflects differing scope definitions—particularly the inclusion of bio-based substrates and ultra-high-concentration formulations. Our analysis suggests the more aggressive forecast is defensible given accelerating adoption of precision-spray technologies and regulatory-driven replacement of petroleum-based surfactants.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
2.40 Billion
2026
2031
6.9%
Broad scope incl. bio-based and specialty adjuvants
Core surfactants, excluding some specialty functions
Published estimate C
The most defensible figure for strategic planning is the 2.40 Billion base, as it captures the rapid shift toward high-performance, bio-based adjuvants that are reshaping product portfolios.
How is the market segmented?
The Agricultural Surfactants Market is segmented by product type, substrate, application, form, function, and crop type. Non-ionic surfactants lead with 41% share, while bio-based substrates are the fastest-growing at 18.1% CAGR. Liquid formulations dominate with 68% share, and wetting agents account for 55% of functional demand.
Parent Segment
Children
Product Type
Non-ionic, Anionic, Cationic, Amphoteric
Substrate
Synthetic, Bio-based
Application
Herbicides, Fungicides, Insecticides
Form
Liquid, Powder/Granular
Function
Wetting Agents, Penetrants, Adjuvants
Crop Type
Cereals & Grains, Fruits & Vegetables, Others
Which region leads in Agricultural Surfactants Market?
North America leads the global Agricultural Surfactants Market with 37% revenue share in 2025, driven by advanced farming practices and high herbicide adoption. Asia-Pacific is the fastest-growing region at 11.5% CAGR, fueled by modernization and rising agrochemical use. Europe follows with 22% share, while South America and Middle East & Africa represent smaller but emerging markets.
What is driving growth — and what is holding it back?
Rising demand for agrochemicals to boost crop yields is the primary driver, contributing +2.1% to CAGR, followed by precision-farming adoption (+1.8%) and sustainability focus (+1.5%). However, high production costs for bio-based raw materials (-1.4%) and stringent regulations (-1.2%) restrain growth. The net balance favors expansion, but margin pressure is acute in Europe and North America.
Factor
Direction
Evidence Strength
Mechanism
Rising agrochemical demand
Driver
High
Multiple spray passes and resistance management increase surfactant loads
Palm-derived fatty alcohols and ethylene oxide shortages
Who are the leading vendors?
The market is moderately concentrated, with BASF, Corteva, Nouryon, Solvay, and Marubeni leading through formulation innovation, sustainability credentials, and global distribution. Differentiation hinges on bio-based product lines and nano-emulsion technologies that reduce active-ingredient doses. Smaller players compete on cost and regional agility.
What do buyers and operators need to know? (Decision Support)
Buyers must prioritize surfactants that deliver proven efficacy with regulatory compliance. Key selection criteria include biodegradability, aquatic toxicity profiles, and compatibility with precision-spray equipment. Procurement risks include feedstock price volatility and supply chain disruptions for specialty ethoxylates. Switching costs are moderate due to formulation re-optimization, but regulatory approvals can extend timelines. Operators should demand full lifecycle data and third-party certifications (e.g., EPA Safer Choice, EU Ecolabel) to mitigate compliance risk.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish outlook for the Agricultural Surfactants Market, with the 6.9% CAGR scenario more likely than the conservative 5.1% estimate. The strongest counter-argument is that high bio-based raw material costs could slow adoption, but regulatory mandates and retailer ESG policies are likely to override cost concerns. Our analysis suggests the market will increasingly reward suppliers who can deliver cost-competitive bio-based surfactants at scale.
Actionable Strategy:
Invest in bio-based feedstock partnerships to secure supply and reduce cost premiums, targeting 18.1% CAGR segment.
Develop nano-emulsion platforms that lower active-ingredient doses by up to 40%, appealing to precision-farming adopters.
Prioritize regulatory certifications (REACH, EPA Safer Choice) to unlock premium pricing in Europe and North America.
What would change our conclusion: A sustained drop in bio-based raw material costs or a breakthrough in fermentation-derived substrates could accelerate growth beyond 8% CAGR, while a severe regulatory clampdown on all synthetic surfactants could push the market toward the lower forecast.
1. What is the current size of the Agricultural Surfactants Market?
The global Agricultural Surfactants Market is valued at 2.40 Billion in 2026, with projections to reach 3.35 Billion by 2031.
2. Which region dominates the Agricultural Surfactants Market?
North America holds the largest share at 37% in 2025, driven by advanced farming and high herbicide use.
3. What is the fastest-growing segment?
Bio-based surfactants are the fastest-growing substrate segment, expanding at an 18.1% CAGR through 2031.
4. Who are the key players in the Agricultural Surfactants Market?
Leading companies include BASF, Corteva, Nouryon, Solvay, and Marubeni, competing on sustainability and formulation innovation.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with key stakeholders across the value chain, including raw material suppliers, specialized producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. This fieldwork ensures granular insights into formulation trends, procurement strategies, and regulatory challenges.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
40%
Procurement Directors
35%
Quality & Regulatory Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Chemical Producers
45%
Formulators & Blenders
35%
Distributors & Traders
20%
Secondary Benchmarking & Public Trade Validation
We benchmark against official multilateral trade databases including UN Comtrade, WTO, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards such as ISO and ASTM. These sources validate demand patterns, trade flows, and technology adoption rates.
Demand Modeling & Market Sizing Triangulation
Our simultaneous top-down (macroeconomic & industry segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption modeling) triangulation ensures robust market sizing. We cross-validate regional consumption with trade data and production capacities to derive accurate forecasts.
 Agricultural Surfactants Market