 Regenerative Agriculture Market
 Size, Trends & 2031 Outlook
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 247

Atul Bhusare
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Regenerative Agriculture Market
Atul Bhusare
Research Associate

| Year | Market Size |
|---|---|
| 2026 | 10.53 B |
| 2027 | 12.05 B |
| 2028 | 13.79 B |
| 2029 | 15.79 B |
| 2030 | 18.07 B |
| 2031 | 20.69 B |

The regenerative agriculture market comprises farming practices — cover cropping, reduced tillage, agroforestry, managed grazing — plus the enabling inputs, digital platforms, agronomy services and carbon/MRV infrastructure that restore soil health and biodiversity while sustaining yields. It is defined by measurable outcomes, not by input category or organic certification.
This analysis covers global regenerative farming practices, biological and cover-crop inputs, soil and carbon measurement technologies, transition advisory services, and regenerative-linked finance and incentive programs across crop and livestock systems.
This analysis does not cover conventional agrochemical markets, generic organic certification schemes, broad farm-management software without a soil-health use case, or consumer food brands that deploy "regenerative" primarily as marketing positioning.
Estimates diverge sharply because researchers draw the market boundary differently — some count only on-farm practices, others bundle inputs, software, MRV and carbon revenue.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 10.53 Bn → 20.69 Bn | 2026 | 2031 | 14.46% | Practices, inputs, biologicals, digital, carbon services | One published estimate |
| USD 16.8 Bn → 49.1 Bn | 2026 | 2033 | 16.6% | Component solutions/services plus agroforestry and end users | A competing analysis |
| USD 9.83 Bn → 37.44 Bn | 2025 | 2035 | 14.30% | Solutions, services, agroforestry, aquaculture, finance | An alternate published forecast |
| USD 7.16 Bn → 31.61 Bn | 2024 | 2035 | 14.45% | Practice types plus application-based biodiversity scope | A narrower-scope forecast |
Our analysis suggests the mid-range 2026 base of roughly USD 10.5 billion is the most defensible starting point: it sits between the narrow practice-only view and the broad solutions-plus-services view, and its 14–15% growth band is corroborated by three of four published forecasts. The higher 16.6% trajectory implies faster monetization of carbon and services revenue than current corporate contract volumes visibly support.
Segmentation splits along four operational axes — practice, application, input type and farm size — each with a distinct buyer and monetization logic.
| Parent segment | Children | 2025 share / growth signal |
|---|---|---|
| By Practice | Soil health management, agroforestry, no-till & pasture cropping, managed grazing, agri-PV, aquaculture, biochar | Soil health 26.02%; agri-PV fastest at 20.85% CAGR |
| By Application | Crop production, livestock grazing, carbon sequestration, biodiversity, operation management | Crop production 45.88%; carbon sequestration fastest at 17.86% |
| By Input Type | Biologicals, seeds & cover crops, sensors & IoT, soil amendments | Biologicals 39.36%; sensors/IoT fastest at 17.42% |
| By Farm Size | Small-scale, mid-scale, large-scale | Small-scale 51.85%; fastest at 16.21% |
The small-scale dominance is the segment insight most buyers miss: it implies distribution and advisory economics matter more than large-enterprise sales motion.
North America leads with 36.58% of 2025 value, anchored by USDA climate-smart funding and corporate acreage mandates; Africa is the fastest-growing region at 14.86% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.24% |
| Asia-Pacific | 0.21% |
| Latin America | 0.09% |
| Middle East & Africa | 0.09% |
| Region | 2025 share |
|---|---|
| North America | 36.58% |
| Europe | 24.0% |
| Asia Pacific | 21.0% |
| Latin America | 9.0% |
| Middle East & Africa | 9.4% |
Europe's position is policy-anchored: the EU JRC estimates soil degradation costs exceed €50 billion annually and over 60% of EU soils are unhealthy, making regenerative practice a competitiveness lever, not just an environmental one.
Corporate procurement mandates and outcome-based public incentives are the strongest near-term demand levers; transition cost and verification gaps remain the binding constraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Corporate net-zero and sourcing pledges | Driver | High | Acreage mandates (PepsiCo 7M acres; Mars 1M acres by 2030) create contractual pull |
| Government soil-health incentives | Driver | High | USDA USD 3.1 Bn Climate-Smart Commodities; 25% of EU CAP direct payments into eco-schemes |
| Consumer premium demand | Driver | Medium | 63% of surveyed food firms cite regenerative in sustainability roadmaps |
| Climate mitigation and adaptation | Driver | Medium | ~1.29 t CO2e/ha annual reduction verified across 550,000+ hectares |
| High transition costs | Restraint | High | New equipment, training and multi-year yield risk deter smallholders |
| Certification and MRV fragmentation | Restraint | High | Absent standardized verification, premium and carbon value stays uncertain |
Our analysis suggests the driver/restraint balance favors growth but is more fragile than headline CAGRs imply: two of the top three drivers are corporate and policy commitments that can be repriced or defunded within a single budget cycle.
No single vendor holds dominant share — concentration is medium, with food majors, input suppliers and digital/MRV platforms competing on different layers of the value chain.
| Company | Primary positioning | Strategic moat |
|---|---|---|
| Nestlé SA | Corporate sourcing commitment (CHF 1.2 Bn) | Procurement scale and supplier contract leverage |
| PepsiCo | 7M-acre mandate backed by USD 216 M | Direct grower incentive programs |
| Mars | Aggregator partnerships, 1M acres by 2030 | Supply-chain intermediaries and verification |
| Indigo Ag | Soil-carbon monitoring at scale | Large verified hectare dataset and MRV infrastructure |
| Agreena | Carbon fintech and transition finance | Bank partnerships and green-finance access |
| Danone, General Mills, Unilever | Downstream regenerative sourcing | Brand pull and long-term offtake |
Differentiation is shifting from product efficacy to verified evidence. Our analysis suggests vendors that own the measurement layer — not just the input — will capture disproportionate margin as corporate buyers standardize on outcome-based contracts.
Selection should start with verification credibility, not input performance. Buyers procuring regenerative programs should demand audit-ready MRV trails, because premium pricing and carbon revenue both collapse if outcomes cannot be independently confirmed.
Procurement risk concentrates in transition economics. Small-scale farms hold 51.85% of demand but carry the thinnest balance sheets, so suppliers offering financing, agronomy support or shared-risk contracts face lower churn than pure input vendors.
Regulatory compliance is tightening rather than stabilizing. The EU Nature Restoration Law's 20% restoration obligation by 2030 and the EU Carbon Removals and Carbon Farming Regulation create both certification requirements and a potential €6 billion annual carbon revenue pool — operators without documentation infrastructure will be locked out of these channels.
Switching costs are asymmetric: once a grower's carbon project is registered under a specific methodology, changing providers risks forfeiting accumulated credit history. This creates sticky, annuity-like relationships for first movers and a genuine land-grab dynamic in the advisory layer.
The balance of evidence favors a mid-teens growth trajectory anchored near 14.5% CAGR, with the strongest value migration toward measurement, verification and transition services rather than conventional input volume. The most credible counter-argument is that corporate acreage pledges are aspirational marketing with weak enforcement, which would compress carbon and services revenue well below forecast. We weight this risk as material but not dominant, because public incentive programs are independently funded.
Our analysis suggests the decisive second-order effect is margin compression in undifferentiated inputs. As biologicals reach 39.36% share and sensors grow at 17.42% CAGR, buyers will commoditize the input layer while paying premiums for provable outcomes — squeezing vendors who sell products without attached data.
Evidence that would change this conclusion: sustained rollback of EU or US incentive funding, or verified data showing corporate regenerative acreage mandates are quietly abandoned, would justify downgrading the forecast toward the lower end of the published range.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.46% from 2020-2034 |
| Segmentation |
|
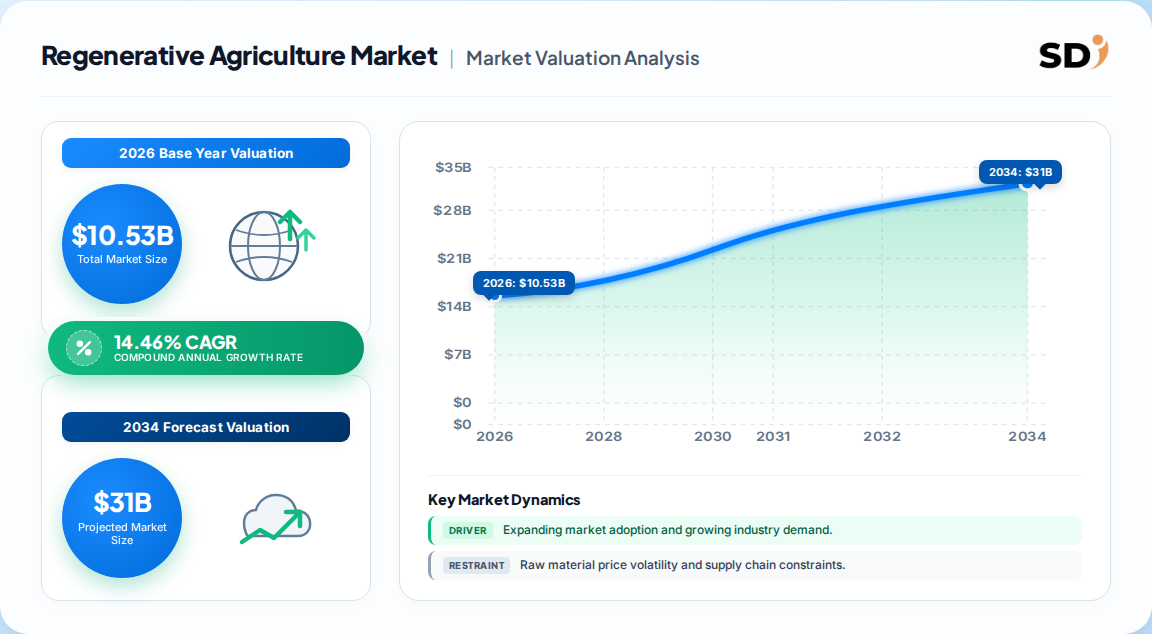
The market was valued at USD 10.53 billion in 2026 and is forecast to reach USD 20.69 billion by 2031, growing at a 14.46% CAGR driven by soil health, corporate sourcing mandates and public incentives.
Carbon sequestration services are the fastest-growing application at 17.86% CAGR, while agri-PV integration leads practices at 20.85% CAGR and sensors/IoT expand at 17.42%.
North America holds 36.58% of value, supported by USDA climate-smart funding and corporate acreage programs. Africa is the fastest-growing region at 14.86% CAGR.
High transition costs, multi-year yield risk for smallholders, and fragmented certification and MRV standards limit adoption. Over 60% of EU soils are degraded, raising the cost of inaction.
Leading players include Nestlé, PepsiCo, Mars, Danone, General Mills, Unilever, Indigo Ag and Agreena. Concentration is medium, with competition shifting toward verification and MRV capability.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured interviews were conducted across the value chain with biological input producers, cover-crop seed suppliers, digital MRV and soil-sensing providers, farm advisory and transition-service firms, and corporate procurement teams at food and beverage majors. Decision-maker designations interviewed included VP-level Sourcing, Heads of Sustainability and Regenerative Sourcing, Technical Agronomy Directors, and Commercial Operations Leads managing grower programs. Fieldwork captured program economics, acreage conversion rates and verification cost structures.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Sustainability Leads | 40% |
| Technical Agronomy Directors | 30% |
| Commercial Operations Leads | 30% |
| Company Type | Representation (%) |
|---|---|
| Biological Input & Seed Producers | 35% |
| Digital MRV & Soil-Sensing Providers | 30% |
| Farm Advisory & Transition Services | 20% |
| Corporate Buyers & Aggregators | 15% |
Secondary validation drew on UN Comtrade and Eurostat agricultural trade flows, USDA conservation program disclosures, European Commission Joint Research Centre soil and carbon-farming publications, corporate 10-K and annual investor filings, patent databases for soil-sensing and MRV technologies, and recognized standards bodies including FAO technical guidance and ISO agricultural data frameworks.
Top-down allocation used macroeconomic agricultural output and sustainability-program budgets by region and segment. Bottom-up modeling used grower acreage, per-hectare practice spend, input pricing and service contract values. Both approaches were reconciled to produce a single base-year value and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up acreage and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Trade flow analysis and regional program spend | High |
| Competitive Landscape | Leading market players | Annual reports, program filings and capacity mapping | High |