Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Liquid Crystal Polymers Market by Product Type (Thermotropic LCP, Lyotropic LCP), by Polymer Architecture (Main Chain LCP, Side Chain LCP), by Form (LCP Resins and Compounds, LCP Films, LCP Fibers), by Application (Electrical Connectors, Fiber Optics, Automotive Lamps, Catheter Reinforcement, Surgical Instruments, Composites and Coatings), by End Use (Semiconductors and Electronics, Automotive, Healthcare, Consumer Goods, Aerospace, Industrial Machinery), by Asia Pacific (China, Japan, South Korea, India, Rest of Asia Pacific), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Rest of Europe), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 279
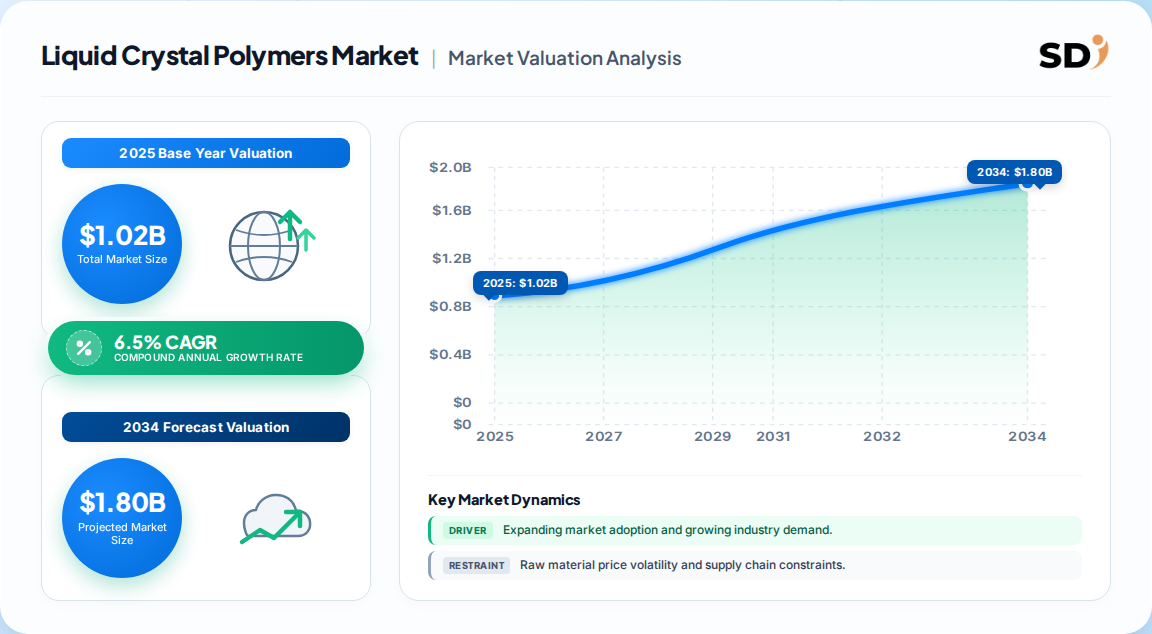
The global Liquid Crystal Polymers Market is sized at roughly 1.02 Billion in 2025, the base year used throughout this overview, with Asia-Pacific holding about 62% of value.
Forecast growth runs at a blended 6.5% CAGR, landing near 1.49 Billion by 2030, which implies roughly half a billion dollars of incremental annual demand in five years.
Semiconductors and electronics remain the dominant end-use block, absorbing an estimated 78% of LCP volume, concentrated in connectors, RF substrates and antenna modules.
Asia-Pacific leads on both capacity and consumption, with China, Japan and South Korea accounting for the bulk of compounding and film supply.
Leading vendors include Celanese, Polyplastics, Toray Industries, Sumitomo Chemical, Kuraray, Solvay and RTP Company, with concentration assessed as medium.
Why this matters for decision-makers: Published forecasts for this market diverge by more than 3x on 2030 value, so buyers must anchor qualification and sourcing decisions to demonstrated grade-level capability rather than to headline growth rates.
Liquid Crystal Polymers Market Size (In Million)
1.5B
1.0B
500.0M
0
960.0 M
2024
1.020 B
2025
1.090 B
2026
1.160 B
2027
1.230 B
2028
1.310 B
2029
1.490 B
2030
Liquid Crystal Polymers Market Size (In Million)
Year
Market Size
2024
960.0 M
2025
1.020 B
2026
1.090 B
2027
1.160 B
2028
1.230 B
2029
1.310 B
2030
1.490 B
What is the Liquid Crystal Polymers Market?
The liquid crystal polymers market covers high-performance thermoplastic resins, films and fibers whose rigid rod-like molecular chains self-align in the melt or in solution. This ordered structure delivers low dielectric loss, tight dimensional stability, high-temperature tolerance and low moisture uptake in thin-wall components.
Scope: what this report covers and excludes
This overview covers LCP in thermotropic and lyotropic forms, across compounds and resins, films and fibers, segmented by end-use industry and region. Value figures are stated at manufacturer level in US dollars.
This analysis does not cover adjacent high-performance polymer families such as polyetheretherketone, polyimide, polysulfone or polyamide-imide, nor does it cover general-purpose engineering resins, LCP monomer chemistry economics or capex-level plant engineering.
How big is the market for Liquid Crystal Polymers Market?
Published valuations for this market diverge sharply because analysts define LCP boundaries differently. Some count only neat resin and compound sales; others fold in films, laminates, fibers and value-added component assemblies, which inflates the headline materially.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
957.5 Million to 1.3 Billion
2023
2028
6.1%
LCP forms, applications and end uses, value and tons
One published estimate
0.91 Billion to 1.46 Billion
2025
2031
8.31%
Thermotropic and lyotropic resin, end-user industries
A competing analysis
2.0 Billion to 3.12 Billion
2025
2030
9.4%
Broad LCP product and application taxonomy
A competing analysis
1.8 Billion to 5.1 Billion
2024
2033
12.9%
Application-led, includes downstream component value
A competing analysis
The most defensible anchor is the 6.1% path from roughly 0.96 Billion, because it reconciles value with declared tonnage and avoids double-counting downstream assemblies. Our analysis suggests the 12.9% figure embeds system-level value capture rather than polymer revenue, and therefore overstates supplier-addressable demand. We use a blended 6.5% CAGR as the central case.
Year
Value
2024
0.96 Billion
2025
1.02 Billion
2026
1.09 Billion
2027
1.16 Billion
2028
1.23 Billion
2029
1.31 Billion
2030
1.49 Billion
Figures from 2026 onward are derived from the stated base value and blended CAGR.
How is the market segmented?
Segmentation follows four axes: product chemistry, physical form, application and end-use industry. Chemistry matters most commercially, because thermotropic grades dominate mouldable parts while lyotropic grades serve fiber and composite niches.
Semiconductors and electronics, automotive, healthcare, consumer goods, aerospace, industrial machinery
Thermotropic grades hold roughly 95% of volume because they run on standard injection-moulding lines and survive reflow profiles above 280 degrees Celsius. Our analysis suggests the fastest incremental value sits in film and laminate formats rather than in neat resin, since film pricing carries a 30 to 40% premium and faces fewer commodity substitutes.
Which region leads in Liquid Crystal Polymers Market?
Asia-Pacific leads with roughly 62% of global value, reflecting concentrated polymerization capacity in Japan and China plus the densest electronics assembly base. North America is the fastest-growing region on EV power electronics and aerospace demand.
China, Japan, South Korea, India, Rest of Asia-Pacific
North America
United States, Canada, Mexico
Europe
Germany, United Kingdom, France, Italy, Rest of Europe
Latin America
Brazil, Mexico, Argentina
Middle East & Africa
Saudi Arabia, UAE, South Africa
Region
Share
Asia-Pacific
62%
North America
17%
Europe
14%
Middle East & Africa
4%
South America
3%
This concentration implies supply risk: a single Japanese or Chinese plant outage can tighten specialty film availability for the entire global connector chain. Buyers without dual-region qualification carry real exposure.
What is driving growth — and what is holding it back?
Growth is pulled by miniaturisation and radio-frequency integration, electrified vehicle power electronics, flexible high-frequency circuits and medical sensor films. It is restrained by premium pricing, anisotropic processing complexity and slow automotive qualification cycles.
Factor
Direction
Evidence strength
Mechanism
Miniaturised surface-mount and 5G RF modules
Up
Strong
Dielectric constant near 3.0 and low dissipation favour LCP substrates above 10 GHz
Metal replacement in EV power electronics
Up
Strong
Retains most tensile strength at 240 degrees, cuts part mass up to 50%
Flexible circuits and foldable displays
Up
Moderate
Survives over 200,000 bends at 1 mm radius
Implantable and wearable sensor films
Up
Moderate
Moisture uptake below 0.02% with acceptable biocompatibility
Premium price versus commodity resins
Down
Strong
30 to 40% material premium slows cost-sensitive conversion
Processing complexity and anisotropy
Down
Moderate
Requires tight mould control and specialist design knowledge
Long automotive qualification cycles
Down
Strong
24 to 36 month validation gates delay volume ramp
The balance of evidence favours demand: the technology shifts are structural and mutually reinforcing, whereas restraints are cost and know-how barriers that erode as volumes scale. Our analysis suggests the binding constraint through 2030 is qualified film capacity, not resin availability.
Who are the leading vendors?
Competition is moderately concentrated around Japanese and Western specialty chemical producers, with differentiation shifting from capacity to formulation know-how in low-dielectric and bio-based grades.
Company
Primary strength
Positioning
Celanese
Broad LCP compound portfolio across electronics and automotive
Scale leader with global compounding
Polyplastics
RF-grade and antenna-in-package series
Technology leader in high-frequency grades
Toray Industries
Film and fiber integration
Vertically integrated materials science
Sumitomo Chemical
Electronics-grade resin supply
Strong Asia-Pacific footprint
Kuraray
Specialty polymer and fiber capability
Niche high-performance positions
Solvay
High-performance polymer portfolio
Diversified premium player
RTP Company
Custom compound formulation
Formulation agility for niche applications
Moats rest on qualified grade libraries, tooling lock-in after automotive validation and copper-clad film yields, where a handful of suppliers control most laminate revenue. Our analysis suggests new entrants can compete in commodity compounds but not in sub-50-micron film.
What do buyers and operators need to know?
Selection criteria should centre on dielectric performance at target frequency, dimensional stability after reflow, tensile retention at operating temperature and documented biocompatibility where relevant. Request grade-specific data rather than family-level claims, because formulation differences within one supplier are commercially decisive.
Procurement risk concentrates in single-source specialty film and in qualification switching costs: once a grade clears automotive validation, re-tooling and re-testing can consume six to nine months. Contracts should therefore secure capacity allocations rather than price alone.
Regulatory exposure is rising. Updated chemical review requirements and circularity rules in major jurisdictions extend testing timelines for novel grades, and suppliers investing early in traceability and recycled or bio-based feedstocks convert compliance into speed-to-market advantage.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours a structurally growing but supply-constrained market, not a commodity expansion story. Demand drivers are technically grounded in measurable dielectric and thermal properties, while the divergent headline forecasts reflect scope inflation rather than genuine disagreement about polymer volumes. Buyers should treat the 6 to 8% band as the planning range and disregard double-digit projections unless they include downstream assemblies.
The strongest counter-argument is that substitution risk is understated: polyimide incumbency, improved laminates and cost-driven hybrid designs could cap LCP penetration in price-sensitive electronics. That risk is real in consumer segments but weak in RF front-ends and high-temperature power electronics, where property thresholds are not negotiable.
Investors should weight exposure toward film and laminate capability and RF-grade compounds rather than neat resin capacity.
Operators should dual-qualify at least two regional film sources to de-risk supply concentration in Asia-Pacific.
Procurement leads should negotiate capacity-reservation clauses and lock grades before automotive validation cycles begin.
Evidence that would change this conclusion: sustained price parity with incumbent resins, a credible high-frequency substitute reaching volume production, or a multi-year slowdown in 5G and EV power electronics build-out.
While this overview establishes the demand architecture and competitive structure, precise grade-level revenue, tonnage and country forecasting requires the full report's segment models and vendor share work.
Table 9: Liquid Crystal Polymers Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 10: Liquid Crystal Polymers Market Volume Tons Forecast, by End Use 2020 & 2034
Table 11: Liquid Crystal Polymers Market Revenue Billion Forecast, by Region 2020 & 2034
Table 12: Liquid Crystal Polymers Market Volume Tons Forecast, by Region 2020 & 2034
Table 13: Asia Pacific Liquid Crystal Polymers Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 14: Asia Pacific Liquid Crystal Polymers Market Volume Tons Forecast, by Product Type 2020 & 2034
Table 15: Asia Pacific Liquid Crystal Polymers Market Revenue Billion Forecast, by Polymer Architecture 2020 & 2034
Table 16: Asia Pacific Liquid Crystal Polymers Market Volume Tons Forecast, by Polymer Architecture 2020 & 2034
Frequently Asked Questions
1. How big is the liquid crystal polymers market?
The market is estimated at roughly 1.02 Billion in 2025 and is forecast to reach about 1.49 Billion by 2030. Estimates vary widely because some analyses include downstream films and component assemblies rather than polymer revenue alone.
2. What is the growth rate of the liquid crystal polymers market?
A blended CAGR of about 6.5% is the most defensible planning figure. Published forecasts range from 6.1% to 12.9%, with the higher figures typically reflecting broader scope definitions that count system-level value rather than resin sales.
3. Which region dominates liquid crystal polymer demand?
Asia-Pacific leads with roughly 62% of global value, driven by concentrated polymerization capacity in China, Japan and South Korea plus the world's densest electronics assembly base. North America is the fastest-growing region on EV and aerospace demand.
4. What are liquid crystal polymers used for?
They are used mainly in electrical connectors, 5G radio-frequency substrates, antenna modules, flexible circuits, automotive lamp and inverter components, and medical device reinforcement. Their low dielectric loss and dimensional stability under reflow temperatures make them the material of record in miniaturised electronics.
5. Who are the leading liquid crystal polymer suppliers?
Key suppliers include Celanese, Polyplastics, Toray Industries, Sumitomo Chemical, Kuraray, Solvay and RTP Company. Competition is moderately concentrated, with differentiation shifting toward low-dielectric grades, thin films and bio-based formulations.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study follows a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain with raw material and monomer suppliers, specialised LCP producers, contract compounders and film converters, and global distributors serving electronics and automotive accounts. Respondents were designated decision-makers including Vice Presidents of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring that volume estimates were cross-checked against both technical feasibility and commercial reality.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
32%
R&D & Technical Directors
38%
Commercial Operations Leads
18%
Regulatory & Quality Managers
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Monomer Suppliers
30%
Specialised LCP Producers
35%
Compounders & Film Converters
22%
Global Distributors
13%
Secondary Benchmarking & Public Trade Validation
Desk research drew on UN Comtrade and national customs classifications for polymer trade flows, WTO tariff schedules, US International Trade Commission filings, Eurostat industrial statistics, corporate 10-K and annual investor disclosures, patent databases for LCP composition and film processing, and recognised technical standards bodies including ISO and ASTM committees governing thermal, dielectric and biocompatibility testing.
Demand Modeling & Market Sizing Triangulation
Market sizing applied simultaneous top-down and bottom-up triangulation. The top-down path allocated macroeconomic electronics, automotive and medical output to LCP intensity by application. The bottom-up path modelled producer capacity, realised grade pricing and end-use consumption by region, reconciling value and tonnage before forecasting.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Value in USD for base year
Bottom-up production and revenue triangulation
High
Forecast Horizon
Multi-year compound projection
Historical CAGR, regression and demand elasticity
High
Regional Distribution
Regional share breakdown
Cross-border trade flow and regional consumption analysis
High
Competitive Landscape
Leading market players
Annual reports, capacity mapping and commercial filings
High
Sources Referenced
UN Comtrade database for polymer and plastic product trade flows
ISO and ASTM standards for thermal, dielectric and medical polymer testing
US International Trade Commission and Eurostat industrial statistics
Corporate annual reports and investor disclosures from listed LCP producers
Figure 16:
Figure 17: Asia Pacific Liquid Crystal Polymers Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Asia Pacific Liquid Crystal Polymers Market Volume Share (%), by Application 2026 & 2034
Figure 19: Asia Pacific Liquid Crystal Polymers Market Revenue (Billion), by End Use 2026 & 2034
Figure 20: Asia Pacific Liquid Crystal Polymers Market Volume (Tons), by End Use 2026 & 2034
Figure 21: Asia Pacific Liquid Crystal Polymers Market Revenue Share (%), by End Use 2026 & 2034
Figure 22: Asia Pacific Liquid Crystal Polymers Market Volume Share (%), by End Use 2026 & 2034
Figure 23: Asia Pacific Liquid Crystal Polymers Market Revenue (Billion), by Country 2026 & 2034
Figure 24: Asia Pacific Liquid Crystal Polymers Market Volume (Tons), by Country 2026 & 2034
Figure 25: Asia Pacific Liquid Crystal Polymers Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Liquid Crystal Polymers Market Volume Share (%), by Country 2026 & 2034
Figure 27: North America Liquid Crystal Polymers Market Revenue (Billion), by Product Type 2026 & 2034
Figure 28: North America Liquid Crystal Polymers Market Volume (Tons), by Product Type 2026 & 2034
Figure 29: North America Liquid Crystal Polymers Market Revenue Share (%), by Product Type 2026 & 2034
Figure 30: North America Liquid Crystal Polymers Market Volume Share (%), by Product Type 2026 & 2034
Figure 31: North America Liquid Crystal Polymers Market Revenue (Billion), by Polymer Architecture 2026 & 2034
Figure 32: North America Liquid Crystal Polymers Market Volume (Tons), by Polymer Architecture 2026 & 2034
Figure 33: North America Liquid Crystal Polymers Market Revenue Share (%), by Polymer Architecture 2026 & 2034
Figure 34: North America Liquid Crystal Polymers Market Volume Share (%), by Polymer Architecture 2026 & 2034
Figure 35: North America Liquid Crystal Polymers Market Revenue (Billion), by Form 2026 & 2034
Figure 36: North America Liquid Crystal Polymers Market Volume (Tons), by Form 2026 & 2034
Figure 37: North America Liquid Crystal Polymers Market Revenue Share (%), by Form 2026 & 2034
Figure 38: North America Liquid Crystal Polymers Market Volume Share (%), by Form 2026 & 2034
Figure 39: North America Liquid Crystal Polymers Market Revenue (Billion), by Application 2026 & 2034
Figure 40: North America Liquid Crystal Polymers Market Volume (Tons), by Application 2026 & 2034
Figure 41: North America Liquid Crystal Polymers Market Revenue Share (%), by Application 2026 & 2034
Figure 42: North America Liquid Crystal Polymers Market Volume Share (%), by Application 2026 & 2034
Figure 43: North America Liquid Crystal Polymers Market Revenue (Billion), by End Use 2026 & 2034
Figure 44: North America Liquid Crystal Polymers Market Volume (Tons), by End Use 2026 & 2034
Figure 45: North America Liquid Crystal Polymers Market Revenue Share (%), by End Use 2026 & 2034
Figure 46: North America Liquid Crystal Polymers Market Volume Share (%), by End Use 2026 & 2034
Figure 47: North America Liquid Crystal Polymers Market Revenue (Billion), by Country 2026 & 2034
Figure 48: North America Liquid Crystal Polymers Market Volume (Tons), by Country 2026 & 2034
Figure 49: North America Liquid Crystal Polymers Market Revenue Share (%), by Country 2026 & 2034
Figure 50: North America Liquid Crystal Polymers Market Volume Share (%), by Country 2026 & 2034
Figure 51: Europe Liquid Crystal Polymers Market Revenue (Billion), by Product Type 2026 & 2034
Figure 52: Europe Liquid Crystal Polymers Market Volume (Tons), by Product Type 2026 & 2034
Figure 53: Europe Liquid Crystal Polymers Market Revenue Share (%), by Product Type 2026 & 2034
Figure 54: Europe Liquid Crystal Polymers Market Volume Share (%), by Product Type 2026 & 2034
Figure 55: Europe Liquid Crystal Polymers Market Revenue (Billion), by Polymer Architecture 2026 & 2034
Figure 56: Europe Liquid Crystal Polymers Market Volume (Tons), by Polymer Architecture 2026 & 2034
Figure 57: Europe Liquid Crystal Polymers Market Revenue Share (%), by Polymer Architecture 2026 & 2034
Figure 58: Europe Liquid Crystal Polymers Market Volume Share (%), by Polymer Architecture 2026 & 2034
Figure 59: Europe Liquid Crystal Polymers Market Revenue (Billion), by Form 2026 & 2034
Figure 60: Europe Liquid Crystal Polymers Market Volume (Tons), by Form 2026 & 2034
Figure 61: Europe Liquid Crystal Polymers Market Revenue Share (%), by Form 2026 & 2034
Figure 62: Europe Liquid Crystal Polymers Market Volume Share (%), by Form 2026 & 2034
Figure 63: Europe Liquid Crystal Polymers Market Revenue (Billion), by Application 2026 & 2034
Figure 64: Europe Liquid Crystal Polymers Market Volume (Tons), by Application 2026 & 2034
Figure 65: Europe Liquid Crystal Polymers Market Revenue Share (%), by Application 2026 & 2034
Figure 66: Europe Liquid Crystal Polymers Market Volume Share (%), by Application 2026 & 2034
Figure 67: Europe Liquid Crystal Polymers Market Revenue (Billion), by End Use 2026 & 2034
Figure 68: Europe Liquid Crystal Polymers Market Volume (Tons), by End Use 2026 & 2034
Figure 69: Europe Liquid Crystal Polymers Market Revenue Share (%), by End Use 2026 & 2034
Figure 70: Europe Liquid Crystal Polymers Market Volume Share (%), by End Use 2026 & 2034
Figure 71: Europe Liquid Crystal Polymers Market Revenue (Billion), by Country 2026 & 2034
Figure 72: Europe Liquid Crystal Polymers Market Volume (Tons), by Country 2026 & 2034
Figure 73: Europe Liquid Crystal Polymers Market Revenue Share (%), by Country 2026 & 2034
Figure 74: Europe Liquid Crystal Polymers Market Volume Share (%), by Country 2026 & 2034
Figure 75: Latin America Liquid Crystal Polymers Market Revenue (Billion), by Product Type 2026 & 2034
Figure 76: Latin America Liquid Crystal Polymers Market Volume (Tons), by Product Type 2026 & 2034
Figure 77: Latin America Liquid Crystal Polymers Market Revenue Share (%), by Product Type 2026 & 2034
Figure 78: Latin America Liquid Crystal Polymers Market Volume Share (%), by Product Type 2026 & 2034
Figure 79: Latin America Liquid Crystal Polymers Market Revenue (Billion), by Polymer Architecture 2026 & 2034
Figure 80: Latin America Liquid Crystal Polymers Market Volume (Tons), by Polymer Architecture 2026 & 2034
Figure 81: Latin America Liquid Crystal Polymers Market Revenue Share (%), by Polymer Architecture 2026 & 2034
Figure 82: Latin America Liquid Crystal Polymers Market Volume Share (%), by Polymer Architecture 2026 & 2034
Figure 83: Latin America Liquid Crystal Polymers Market Revenue (Billion), by Form 2026 & 2034
Figure 84: Latin America Liquid Crystal Polymers Market Volume (Tons), by Form 2026 & 2034
Figure 85: Latin America Liquid Crystal Polymers Market Revenue Share (%), by Form 2026 & 2034
Figure 86: Latin America Liquid Crystal Polymers Market Volume Share (%), by Form 2026 & 2034
Figure 87: Latin America Liquid Crystal Polymers Market Revenue (Billion), by Application 2026 & 2034
Figure 88: Latin America Liquid Crystal Polymers Market Volume (Tons), by Application 2026 & 2034
Figure 89: Latin America Liquid Crystal Polymers Market Revenue Share (%), by Application 2026 & 2034
Figure 90: Latin America Liquid Crystal Polymers Market Volume Share (%), by Application 2026 & 2034
Figure 91: Latin America Liquid Crystal Polymers Market Revenue (Billion), by End Use 2026 & 2034
Figure 92: Latin America Liquid Crystal Polymers Market Volume (Tons), by End Use 2026 & 2034
Figure 93: Latin America Liquid Crystal Polymers Market Revenue Share (%), by End Use 2026 & 2034
Figure 94: Latin America Liquid Crystal Polymers Market Volume Share (%), by End Use 2026 & 2034
Figure 95: Latin America Liquid Crystal Polymers Market Revenue (Billion), by Country 2026 & 2034
Figure 96: Latin America Liquid Crystal Polymers Market Volume (Tons), by Country 2026 & 2034
Figure 97: Latin America Liquid Crystal Polymers Market Revenue Share (%), by Country 2026 & 2034
Figure 98: Latin America Liquid Crystal Polymers Market Volume Share (%), by Country 2026 & 2034
Figure 99: Middle East & Africa Liquid Crystal Polymers Market Revenue (Billion), by Product Type 2026 & 2034
Figure 100: Middle East & Africa Liquid Crystal Polymers Market Volume (Tons), by Product Type 2026 & 2034
Figure 101: Middle East & Africa Liquid Crystal Polymers Market Revenue Share (%), by Product Type 2026 & 2034
Figure 102: Middle East & Africa Liquid Crystal Polymers Market Volume Share (%), by Product Type 2026 & 2034
Figure 103: Middle East & Africa Liquid Crystal Polymers Market Revenue (Billion), by Polymer Architecture 2026 & 2034
Figure 104: Middle East & Africa Liquid Crystal Polymers Market Volume (Tons), by Polymer Architecture 2026 & 2034
Figure 105: Middle East & Africa Liquid Crystal Polymers Market Revenue Share (%), by Polymer Architecture 2026 & 2034
Figure 106: Middle East & Africa Liquid Crystal Polymers Market Volume Share (%), by Polymer Architecture 2026 & 2034
Figure 107: Middle East & Africa Liquid Crystal Polymers Market Revenue (Billion), by Form 2026 & 2034
Figure 108: Middle East & Africa Liquid Crystal Polymers Market Volume (Tons), by Form 2026 & 2034
Figure 109: Middle East & Africa Liquid Crystal Polymers Market Revenue Share (%), by Form 2026 & 2034
Figure 110: Middle East & Africa Liquid Crystal Polymers Market Volume Share (%), by Form 2026 & 2034
Figure 111: Middle East & Africa Liquid Crystal Polymers Market Revenue (Billion), by Application 2026 & 2034
Figure 112: Middle East & Africa Liquid Crystal Polymers Market Volume (Tons), by Application 2026 & 2034
Figure 113: Middle East & Africa Liquid Crystal Polymers Market Revenue Share (%), by Application 2026 & 2034
Figure 114: Middle East & Africa Liquid Crystal Polymers Market Volume Share (%), by Application 2026 & 2034
Figure 115: Middle East & Africa Liquid Crystal Polymers Market Revenue (Billion), by End Use 2026 & 2034
Figure 116: Middle East & Africa Liquid Crystal Polymers Market Volume (Tons), by End Use 2026 & 2034
Figure 117: Middle East & Africa Liquid Crystal Polymers Market Revenue Share (%), by End Use 2026 & 2034
Figure 118: Middle East & Africa Liquid Crystal Polymers Market Volume Share (%), by End Use 2026 & 2034
Figure 119: Middle East & Africa Liquid Crystal Polymers Market Revenue (Billion), by Country 2026 & 2034
Figure 120: Middle East & Africa Liquid Crystal Polymers Market Volume (Tons), by Country 2026 & 2034
Figure 121: Middle East & Africa Liquid Crystal Polymers Market Revenue Share (%), by Country 2026 & 2034
Figure 122: Middle East & Africa Liquid Crystal Polymers Market Volume Share (%), by Country 2026 & 2034
Table 17: Asia Pacific Liquid Crystal Polymers Market Revenue Billion Forecast, by Form 2020 & 2034
Table 18: Asia Pacific Liquid Crystal Polymers Market Volume Tons Forecast, by Form 2020 & 2034
Table 19: Asia Pacific Liquid Crystal Polymers Market Revenue Billion Forecast, by Application 2020 & 2034
Table 20: Asia Pacific Liquid Crystal Polymers Market Volume Tons Forecast, by Application 2020 & 2034
Table 21: Asia Pacific Liquid Crystal Polymers Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 22: Asia Pacific Liquid Crystal Polymers Market Volume Tons Forecast, by End Use 2020 & 2034
Table 23: Asia Pacific Liquid Crystal Polymers Market Revenue Billion Forecast, by Country 2020 & 2034
Table 24: Asia Pacific Liquid Crystal Polymers Market Volume Tons Forecast, by Country 2020 & 2034
Table 25: China Liquid Crystal Polymers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: China Liquid Crystal Polymers Market Volume (Tons) Forecast, by Application 2020 & 2034
Table 27: Japan Liquid Crystal Polymers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Japan Liquid Crystal Polymers Market Volume (Tons) Forecast, by Application 2020 & 2034
Table 29: South Korea Liquid Crystal Polymers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: South Korea Liquid Crystal Polymers Market Volume (Tons) Forecast, by Application 2020 & 2034
Table 31: India Liquid Crystal Polymers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: India Liquid Crystal Polymers Market Volume (Tons) Forecast, by Application 2020 & 2034
Table 33: Rest of Asia Pacific Liquid Crystal Polymers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Rest of Asia Pacific Liquid Crystal Polymers Market Volume (Tons) Forecast, by Application 2020 & 2034
Table 35: North America Liquid Crystal Polymers Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 36: North America Liquid Crystal Polymers Market Volume Tons Forecast, by Product Type 2020 & 2034
Table 37: North America Liquid Crystal Polymers Market Revenue Billion Forecast, by Polymer Architecture 2020 & 2034
Table 38: North America Liquid Crystal Polymers Market Volume Tons Forecast, by Polymer Architecture 2020 & 2034
Table 39: North America Liquid Crystal Polymers Market Revenue Billion Forecast, by Form 2020 & 2034
Table 40: North America Liquid Crystal Polymers Market Volume Tons Forecast, by Form 2020 & 2034
Table 41: North America Liquid Crystal Polymers Market Revenue Billion Forecast, by Application 2020 & 2034
Table 42: North America Liquid Crystal Polymers Market Volume Tons Forecast, by Application 2020 & 2034
Table 43: North America Liquid Crystal Polymers Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 44: North America Liquid Crystal Polymers Market Volume Tons Forecast, by End Use 2020 & 2034
Table 45: North America Liquid Crystal Polymers Market Revenue Billion Forecast, by Country 2020 & 2034
Table 46: North America Liquid Crystal Polymers Market Volume Tons Forecast, by Country 2020 & 2034
Table 47: USA Liquid Crystal Polymers Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 48: USA Liquid Crystal Polymers Market Volume (Tons) Forecast, by Application 2020 & 2034
 Liquid Crystal Polymers Market