 Distributed Fiber Optic Sensor Sensing Dfos Market
Distributed Fiber Optic Sensor (DFOS) Market Outlook 2025
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 184

Khageshwar Rongkali

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Distributed Fiber Optic Sensor Sensing Dfos Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 1.600 B |
| 2026 | 1.800 B |
| 2027 | 2.000 B |
| 2028 | 2.300 B |
| 2029 | 2.600 B |
| 2030 | 3.000 B |
| 2031 | 3.300 B |

Distributed fiber optic sensing (DFOS) uses an optical fiber as a continuous sensor, converting Rayleigh, Brillouin, or Raman backscatter into spatially resolved temperature, strain, pressure, and acoustic data along tens of kilometers. Revenue scope includes interrogators, sensing cable, analytics software, and bundled installation and commissioning services.
This report covers global DFOS interrogator hardware, system-supplied sensing cable, embedded analytics software, and bundled installation and commissioning across oil and gas, power and utility, safety and security, industrial, and civil engineering verticals. It sizes revenue at the system level, not component level. This analysis does not cover point-based fiber Bragg grating (FBG) sensor networks, standalone fiber optic communication cable, or general-purpose SCADA and DCS platforms except where bundled into a DFOS deployment.
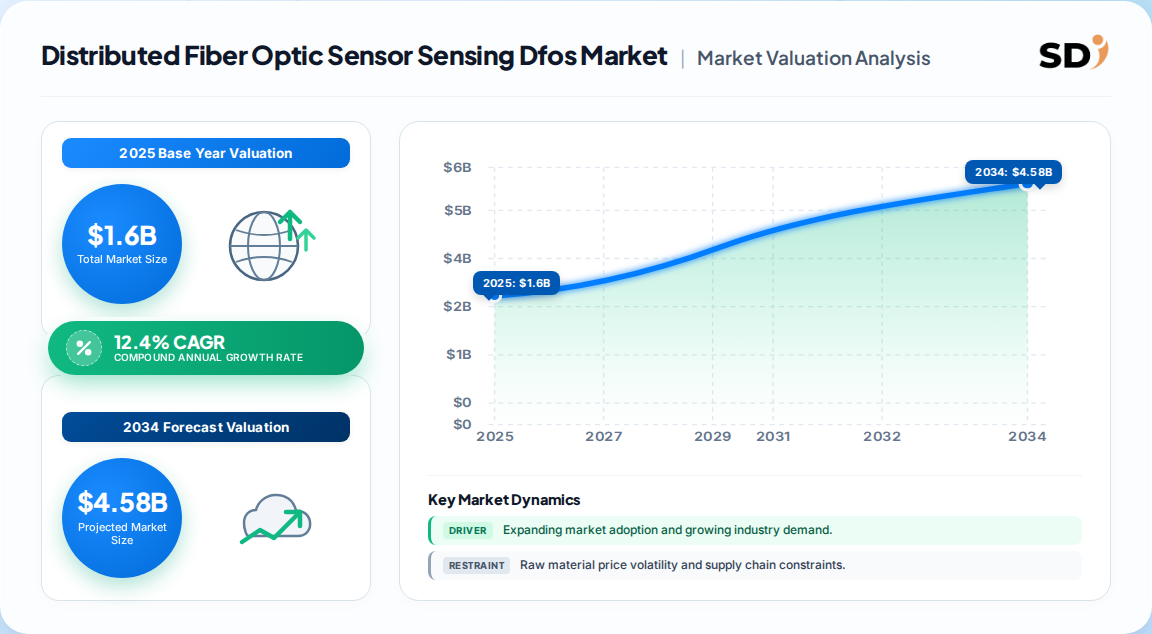
The most defensible base-year figure is USD 1.6 billion in 2025, with a 12.4% CAGR to 2035 — a view corroborated by converging forecasts in the 10–12% range.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.6B → USD 5.3B | 2025 | 2035 | 12.4% | DFOS interrogators, cable, software, installation | One published estimate |
| USD 3.99B by 2033 | 2025 | 2033 | 11.9% | DFOS hardware and systems, all verticals | A competing analysis |
| USD 120M → USD 280M | 2025 | 2034 | 10.07% | Narrow DFOS fiber-type segmentation | A narrower-scope estimate |
| USD 3.01B by 2030 | 2025 | 2030 | ~13.5% | DFOS with bundled services (analyst view) | Industry interview synthesis |
The USD 120 million figure is an outlier because it appears to count only fiber-type sub-segments rather than full system revenue. Our analysis suggests the USD 1.6 billion base and 12.4% CAGR are the most defensible: they align with the ~15,000 km of crude oil and NGL pipelines under construction globally as of March 2025, which alone implies sustained interrogator and cable procurement. The divergence between the USD 5.3 billion (2035) and USD 3.99 billion (2033) forecasts implies definitional differences in whether installation services are capitalized — a gap buyers should probe in any vendor business case.
DFOS segments split along four axes — function, scattering technology, application, and end-use vertical — with temperature sensing and Raman scattering dominating current revenue.
| Parent | Children |
|---|---|
| By Function | Acoustic/Vibration Sensing, Temperature Sensing, Other |
| By Technology | Rayleigh Effect, Brillouin Scattering, Raman Effect, Interferometric, Bragg Grating |
| By Application | Geophysical Event Monitoring, Network Disturbance Monitoring, Rail Infrastructure Monitoring, Urban Monitoring, Subsea Infrastructure Monitoring, Others |
| By Vertical | Oil and Gas, Power and Utility, Safety and Security, Industrial, Civil Engineering |
Temperature sensing held over 45% of 2025 revenue, and Raman-effect systems led technology share on their strength in long-range thermal profiling. This implies that any vendor without a credible DTS-plus-DAS bundle is competing for less than half the addressable spend. Distributed strain sensing (DSS) is the slowest-growing technology at 9.6% CAGR, squeezed by lower-cost FBG and conventional strain gauges in low-density civil monitoring.
North America leads with roughly 30–31% of global DFOS revenue in 2025, but Asia Pacific is the fastest-growing region and is on track to contest that lead before 2035.
| Region | Market Share (%) |
|---|---|
| North America | 0.31% |
| Europe | 0.24% |
| Asia-Pacific | 0.33% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
| Region | 2025 share |
|---|---|
| North America | 31% |
| Asia-Pacific | 33% |
| Europe | 24% |
| Latin America | 6% |
| Middle East & Africa | 6% |
The share table reveals a key nuance: Asia Pacific's combined share already rivals North America's, driven by the ~15,000 km pipeline buildout referenced in global construction data. Our analysis suggests the more consequential regional signal is not the leader but the procurement model — European grid operators increasingly specify thermal monitoring and intrusion detection together, favoring vendors with integration and commissioning depth over pure hardware sellers.
Growth is driven by pipeline expansion, grid modernization, and AI-enabled signal classification, offset by capital constraints at smaller operators and specialized installation bottlenecks.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Pipeline infrastructure expansion | Driver | High | ~15,000 km crude/NGL pipelines under construction (Mar 2025) sustains DTS/DAS procurement |
| Power and utility grid modernization | Driver | High | 14.4% CAGR; HVDC, underground cable, offshore wind export monitoring |
| AI-enhanced signal classification | Driver | Medium | Meter-level event localization reduces reliance on specialist technicians |
| Limited public safety funding | Restraint | Medium | U.S. federal grants of $200M annually cover only a fraction of network costs |
| Substitution in mature DSS | Restraint | Medium | DSS CAGR of 9.6% lags market; FBG and strain gauges compete on upfront cost |
| Installation expertise scarcity | Restraint | High | Controlled-bend radii, splicing crews extend timelines in emerging markets |
The balance of evidence favors the drivers. AI convergence is the most underappreciated factor: it shifts value from raw sensing data to actionable event detection, broadening the buyer base to security and infrastructure operators without in-house optical-sensing teams. Conversely, installation bottlenecks are the most binding constraint — they cap near-term growth precisely in the fastest-expanding regions, which implies integrator relationships, not hardware specs, will determine who wins Asia Pacific volume.
Baker Hughes leads with over 8.1% share, and the top five vendors collectively hold 33.1% — a moderately concentrated market where energy-technology incumbents and specialized sensing firms compete.
| Company | Approx. position | Differentiation |
|---|---|---|
| Baker Hughes | Market leader, 8.1% share | Integrated oilfield services plus DFOS; bundling across asset lifecycle |
| Halliburton | Top five | Upstream and midstream service integration; strong pipeline monitoring |
| Yokogawa Electric | Top five | Industrial automation and control-system integration; power and utility strength |
| Schlumberger (SLB) | Top five | Reservoir and wellbore monitoring; digital platform tie-in |
| Luna Innovations | Top five | Specialized optical sensing and analytics; R&D depth |
| AP Sensing, Silixa, Omnisens | Challengers | Pure-play DTS/DAS specialists; strong in power cable and security niches |
Competitive moats are shifting from sensing performance to integration and analytics. Energy incumbents win on multi-year service contracts and existing operator relationships, while pure-plays win on specialized applications like power cable thermal rating. This divergence implies consolidation pressure: a pure-play without an analytics platform is a natural acquisition target for automation or energy majors seeking DFOS capability.
Buyers should prioritize total cost of ownership over interrogator price, because cable installation and commissioning typically dominate lifecycle cost. Procurement risk concentrates in three areas: installation expertise, where scarcity of qualified splicing crews extends timelines; integration with existing integrity-management and SCADA systems; and analytics maturity, since raw backscatter data without event classification creates operational burden rather than reducing it.
Switching costs are meaningful once fiber is embedded in a pipeline, cable trench, or rail corridor — the sensing medium is effectively permanent, making the interrogator and software layer the only replaceable components. Operators should therefore negotiate data portability and open interfaces up front. Regulatory compliance varies by vertical: pipeline integrity management rules, grid reliability standards, and perimeter-security specifications each impose distinct documentation and certification requirements that a single vendor rarely covers globally.
The balance of evidence favors a 12%+ growth trajectory, but with margin migrating from hardware to analytics and services. The strongest counter-argument is that high initial capital outlay will cap adoption among small municipal utilities and independent pipeline owners, particularly in Latin America and parts of Asia Pacific. That restraint is real but second-order: the fastest-growing verticals — power and utility at 14.4% CAGR and safety and security — are dominated by large, contract-driven buyers for whom DFOS is a reliability investment, not a discretionary spend.
Our judgment is that the market will consolidate around vendors who can deliver interrogator, cable, analytics, and commissioning as a single accountable package. The 33.1% top-five concentration leaves ample room for specialists, but only where they own a defensible application niche or an analytics platform. Buyers should expect multi-year commercial structures to become the norm, which shifts risk from capex to contract terms — a critical negotiation point.
Actionable Strategy:
What would change our conclusion: a sustained decline in pipeline and grid capex in Asia Pacific, or evidence that FBG-based point sensing closes the cost gap in high-density monitoring — neither is visible in current data.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.4% from 2020-2034 |
| Segmentation |
|
The global DFOS market exceeded USD 1.6 billion in 2025 and is projected at USD 1.8 billion in 2026. It is expected to reach USD 5.3 billion by 2035 at a 12.4% CAGR, according to one published estimate.
Power and utility is the fastest-growing end-use vertical, expanding at a 14.4% CAGR from 2026 to 2035. Grid modernization, HVDC links, and offshore wind export monitoring drive structured, multi-year procurement programs for thermal and intrusion monitoring.
Baker Hughes leads with over 8.1% market share in 2025. The top five — Baker Hughes, Halliburton, Yokogawa Electric, Schlumberger, and Luna Innovations — collectively hold 33.1% of global revenue.
North America holds the largest share at roughly 30–31% of global revenue, supported by oil and gas, telecom, and energy infrastructure investment. Asia Pacific is the fastest-growing region, driven by pipeline and grid buildout in China and India.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the DFOS value chain, including optical fiber and cable suppliers, interrogator and system manufacturers, specialized integrators, and global distributors. Decision-maker designations interviewed include VP-level sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads across oil and gas, power and utility, and security end-markets. Interview programs were run across North America, Europe, and Asia Pacific to capture regional procurement behavior.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 30% |
| Company Type | Representation (%) |
|---|---|
| Fiber & Cable Suppliers | 30% |
| Interrogator & System Manufacturers | 40% |
| Integrators & Commissioning Firms | 20% |
| Distributors & Service Providers | 10% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized technical standards bodies and industry associations. Pipeline construction statistics, grid investment data, and security procurement records are cross-referenced to validate demand signals at the segment and regional level.
We run simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption) modeling. The two views are reconciled to produce base-year valuation and multi-year compound projections, with demand elasticity applied to end-use verticals.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |