 Asia Pacific Recycled Plastic Market
 Outlook 2025
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 249

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Asia Pacific Recycled Plastic Market
Khageshwar Rongkali
Senior Analyst

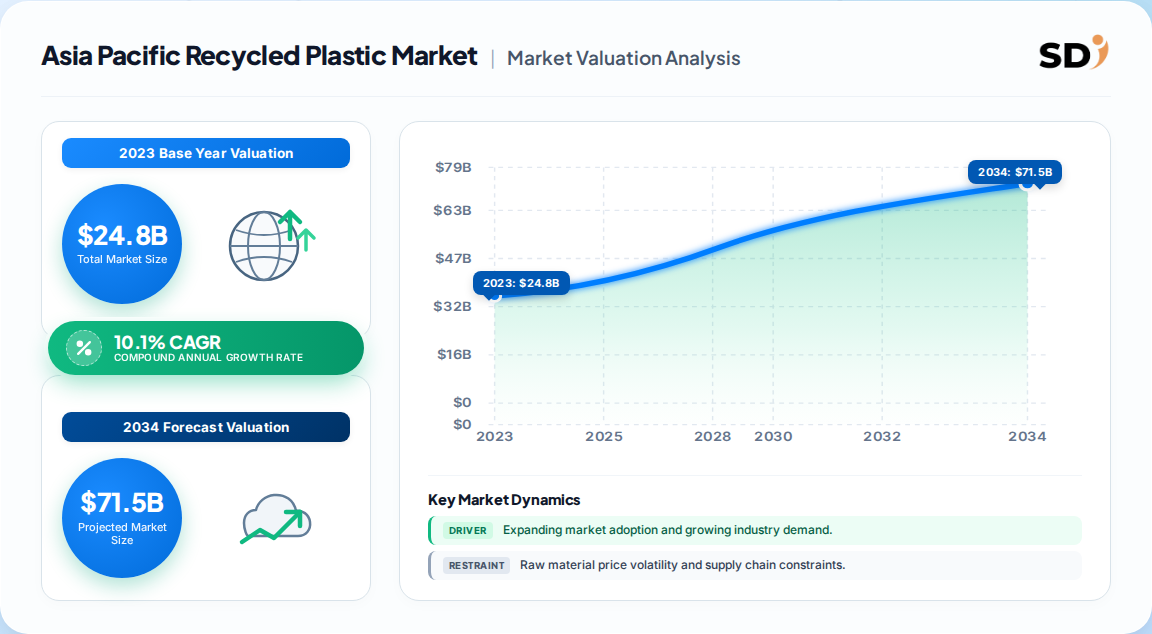
| Year | Market Size |
|---|---|
| 2023 | 24.80 B |
| 2024 | 27.30 B |
| 2025 | 30.06 B |
| 2026 | 33.10 B |
| 2027 | 36.44 B |
| 2028 | 40.12 B |
| 2029 | 44.17 B |

The Asia Pacific recycled plastic market covers the collection, processing, and sale of post-consumer and post-industrial plastics—principally PET, PE, PP, PVC, and PS—reprocessed into flakes, pellets, and finished inputs for packaging, textiles, automotive, construction, and electronics across the region.
This analysis covers mechanical and chemical recycling of post-consumer and post-industrial plastic waste across Asia Pacific, segmented by source (bottles, films, foam, pipes, sheets), polymer type, application, and country. It quantifies value and volume for recycled resin and flake output.
This analysis does not cover virgin polymer production, bio-based plastics, plastic waste trading as a standalone commodity, or downstream converter manufacturing economics.
Published estimates diverge materially because analysts define the market boundary differently—some count only recycled resin value, others include collection and processing services. The table below reconciles the leading figures.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 24.80 Billion | 2023 | 2030 | 10.1% | Recycled plastics resin & flake value, APAC | One published estimate |
| 10.25 Billion | 2024 | 2035 | 7.2% | Plastic recycling (materials + services) | A competing analysis |
| ~31 million tonnes | 2022 | 2030 | 6.03% | Volume of plastics recycled, APAC | A competing analysis |
Our analysis suggests the 24.80 Billion / 10.1% figure is the most defensible for value-based procurement and investment decisions: it aligns with observable rPET and rPP contract pricing and the region's packaging-led demand mix. The lower 10.25 Billion estimate likely reflects a narrower scope that excludes certain industrial scrap streams.
Segmentation matters because margin and regulation differ sharply by polymer and end-use. Food-grade PET carries certification costs; PP and PE serve more fragmented industrial buyers.
| Parent Segment | Children |
|---|---|
| By Source | Plastic Bottles, Plastic Films, Polymer Foam, Pipes, Wires & Cables, Sheets |
| By Type | PET, PE, PP, PVC, PS, Others |
| By Application | Packaging, Building & Construction, Textiles, Automotive, Electrical & Electronics, Others |
China leads decisively, consuming roughly 65% of regional recycled plastics in 2022, followed by India, Japan, South Korea, and Southeast Asia. Leadership reflects both waste generation scale and established processing infrastructure.
China's dominance is structural—it combines the region's largest packaging conversion base with mature collection networks. India is the fastest-growing secondary node, supported by 'Make in India' policy and rising e-commerce packaging waste.
Growth is driven by regulation, brand ESG commitments, and technology; it is restrained by feedstock quality variability and capital intensity. The balance favors expansion through 2030.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Extended producer responsibility (EPR) mandates | Driver | High | Forces brand owners to fund collection and recycled content |
| Brand rPET/rPP targets | Driver | High | Contracts underwrite recycling capacity |
| AI sorting & chemical recycling | Driver | Medium | Improves purity, unlocks hard-to-recycle streams |
| Urbanization & e-commerce waste | Driver | High | Expands feedstock availability |
| Opaque feedstock pricing | Restraint | Medium | Raises procurement risk and margin volatility |
| High capex for advanced plants | Restraint | High | Delays capacity build-out |
| Fragmented informal collection | Restraint | Medium | Limits consistent food-grade supply |
The competitive field spans integrated PET majors, global waste-management groups, and regional specialists. Differentiation rests on food-grade certification, feedstock access, and vertical integration.
| Company | Primary Strength | Regional Position |
|---|---|---|
| Indorama Ventures | Integrated rPET | Pan-APAC leader |
| Veolia | Collection & processing | Multi-country |
| Far Eastern New Century | rPET fiber & resin | Taiwan/China |
| ALPLA | Food-grade rPET | India/SE Asia |
| Intco Environmental | PS/foam recycling | China |
| Banyan Nation | India rPET | India |
Competitive moats center on long-term offtake agreements with global FMCG brands and control of collection logistics. Regional specialists compete on cost and local feedstock relationships rather than scale.
Procurement teams should prioritize suppliers holding food-grade certifications (e.g., EuCertPlast, FDA-compliant rPET) and demonstrated feedstock traceability. Switching costs are moderate but rise sharply for food-contact applications, where requalification can take months.
Regulatory compliance is mission-critical: EPR rules, recycled-content mandates, and import restrictions on plastic waste vary by country and are tightening. Buyers should model dual-sourcing across China and India to mitigate policy and logistics risk, and negotiate indexed pricing tied to virgin resin benchmarks.
The balance of evidence favors a structurally tight food-grade rPET market through 2030, with demand outrunning certified supply. Brands that lock multi-year offtake now will capture cost stability; spot buyers face widening premiums.
The strongest counter-argument is that chemical recycling scale-up could loosen supply faster than expected, compressing premiums. Our analysis suggests this is unlikely before 2028 given capex cycles, but it is the key variable to monitor.
Actionable Strategy:
Evidence that would change our conclusion: sustained virgin resin price declines or accelerated chemical recycling capacity announcements exceeding 2 million tonnes by 2027.
| Region | Market Share (%) |
|---|---|
| China | 0.52% |
| India | 0.14% |
| Japan | 0.11% |
| South Korea | 0.08% |
| Southeast Asia | 0.1% |
| Australia & New Zealand | 0.05% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.1% from 2020-2034 |
| Segmentation |
|
The Asia Pacific recycled plastic market was valued at 24.80 Billion in 2023 and is projected to reach roughly 49 Billion by 2030, growing at a 10.1% CAGR driven by packaging demand and regulation.
China dominates, consuming about 65% of regional recycled plastics in 2022. India is the fastest-growing secondary hub, supported by policy incentives and rising packaging waste.
PET is forecast to grow at 10.6% CAGR through 2030, slightly outpacing the broader market, driven by food-grade rPET demand in beverage and packaging applications.
Extended producer responsibility mandates, brand recycled-content targets, and AI-driven sorting technology are the primary growth drivers, supported by urbanization and e-commerce waste volumes.
Leading players include Indorama Ventures, Veolia, Far Eastern New Century, ALPLA, Intco Environmental, and Banyan Nation, competing on food-grade certification and feedstock access.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews with PET and PP recyclers, food-grade rPET producers, waste-collection operators, brand-owner packaging teams, and regional distributors. Decision-maker designations included VP of Sourcing, Head of Packaging R&D, Technical Directors for recycling operations, and Commercial Operations Leads across China, India, Japan, and Southeast Asia.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 40% |
| Technical & R&D Directors | 35% |
| Sustainability & Regulatory Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Recyclers & Reprocessors | 45% |
| Brand Owners & Converters | 30% |
| Waste Collection & Aggregators | 25% |
We validated findings against UN Comtrade plastic waste and scrap trade flows, WTO tariff schedules, national EPR registries, corporate 10-K and annual investor filings, and patent databases covering sorting and chemical recycling. We also referenced industry association technical standards on food-grade recycled content.
We ran simultaneous Top-Down modeling (macroeconomic packaging output and recycled-content allocation) and Bottom-Up modeling (recycler capacity, plant utilization, and contract pricing) to triangulate the base-year value and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |